brand
ADEDUNTAN: BANKS, CUSTOMERS MUST APPROACH 2023 WITH PARTNERSHIP MINDSET

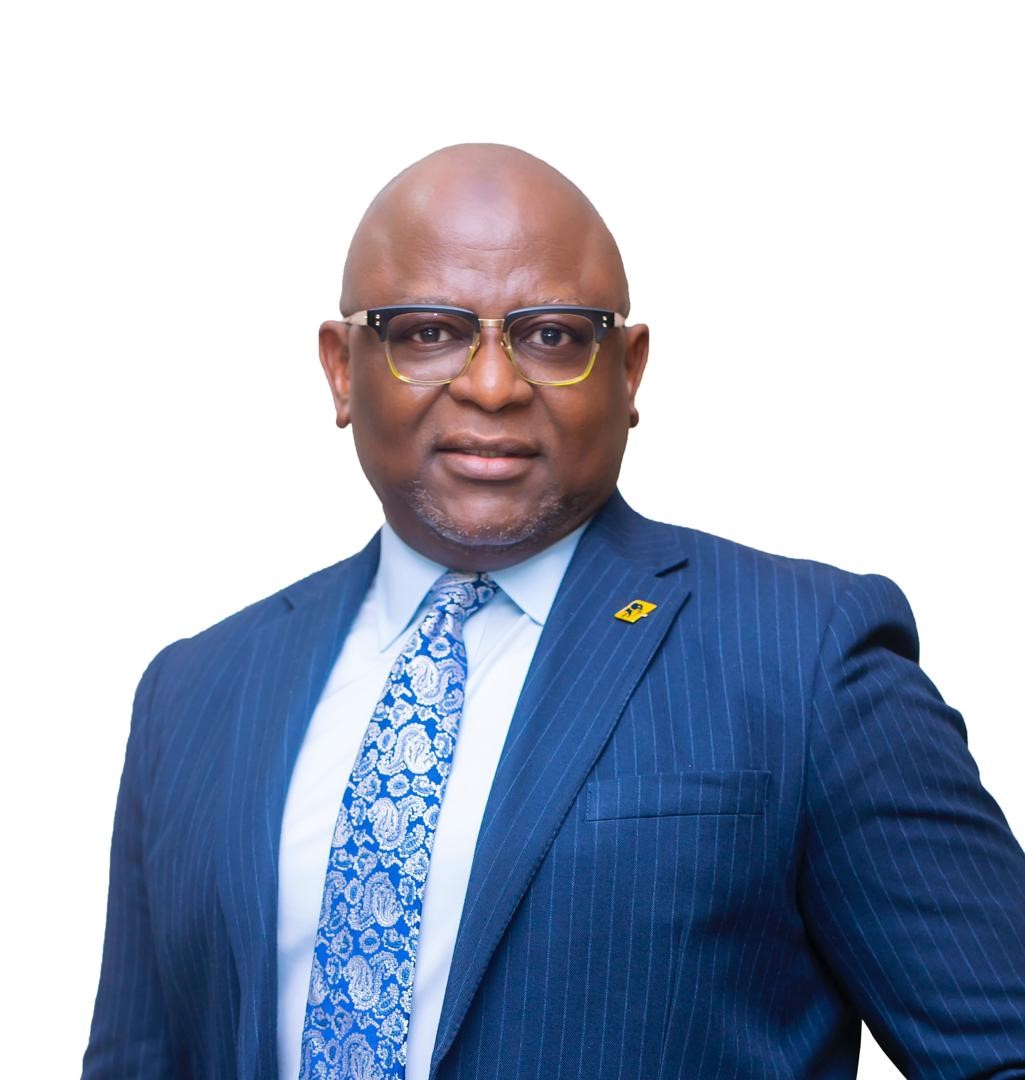
 The Managing Director/Chief Executive Officer of First Bank Nigeria Limited, Dr. Adesola Adeduntan, in this interview with THISDAY reviewed the performance of the global economy in 2022 and advised businesses and their bankers to approach 2023 with a partnership mindset to ensure that a win-win outcome is achieved despite the anticipated macroeconomic challenges. Excerpts:
What are your forecasts and anticipations for the global economy in 2023?
I would like to start by noting that 2022 was indeed a turbulent year for the global economy. In 2022, the global economy witnessed record high inflation rates with the attendant high cost of living across several economies. The elevated inflationary rates were attributed to the aftereffects of the Covid-19 pandemic as well as the Russian-Ukraine crisis. In its last World Economic Outlook report, the IMF projected a 2.7 per cent global growth rate in 2023, lower than the 3.2 per cent in 2022. The 2023 projection will be the weakest global growth profile since 2001 except for the global financial crisis year and the acute phase of the Covid-19 pandemic in 2020. In my view, in 2023, we will likely witness slower growth across several global economies due to lingering trade tensions as the impact of the Russia-Ukraine crisis will still weigh heavily on global trade flows. However, we may witness a decline in commodity prices as more import-dependent countries explore alternative sourcing options for these commodities. Inflationary pressures will however reduce as the impact of rising monetary policy rates continues to yield expected outcomes. The removal of COVID-19 restrictions in China should lead to a boost in global economic output. Oil prices are expected to remain largely elevated as tensions between Russia and Ukraine lingers, so energy prices will remain high. The transition to other sustainable forms of energy may also be accelerated by the prolonged crisis.
Given the tepid growth associated with the global economy in 2022, developing countries have been having difficulties in refinancing their foreign debt, do you see a gloomy impact on the economies of the developing countries in 2023 as a result?
With slowing growth and elevated inflation rates, the sustainability of foreign debts, especially for developing nations, is likely to call for a re-evaluation by lenders given the increased likelihood of default. When this is juxtaposed with the higher interest rate environment at which these debts are likely to be refinanced, you will observe a scenario where further strain is exerted on the debt repayment capacity of these economies. However, this situation does not necessarily translate to an automatic economic doom for developing nations. The actual impact on each developing economy will depend on the economy’s level of fiscal discipline and revenue generating capacity. Developing nations who are able, in the short term, to increase revenues either from taxes or sale/refinancing of idle/sub-optimal assets will be able to negotiate reasonable refinancing terms from lenders and prevent further economic turmoil. Nonetheless, all concerned nations need to take the issue of debt sustainability more seriously by limiting fiscal wastages, reducing inefficiencies, growing revenues, and aggressively working down unsustainable debt-to-GDP levels that may worsen the impacts of external shocks.
Do you think that the corporate default and NPL would increase in 2023 due to the current economic hheadwing
Expectedly, rising cost of debt and contracting demand will exacerbate the challenges that businesses will face in 2023, particularly for players operating in small-margins sectors of the economy. Locally, the surging inflation rate is sure to reduce disposable income of most consumers and demand for non-essential goods and services may dip. To prevent rising non-performing loans (NPLs), businesses and their bankers will have to collaborate more and ensure timely flow of information to prevent surprises. Banks on their part will have to improve monitoring of their loan portfolio to quickly identify early warning signals for attention before a full-scale loan deterioration. Overall, businesses and their bankers must approach 2023 with a partnership mindset to ensure that a win-win outcome is achieved despite the anticipated macroeconomic challenges.
With the tightening financial conditions which has partly led to slow global economic growth, what opportunities do you think exist in 2023 for players in the financial services industry?
Despite the expected macroeconomic challenges in 2023, there are also emerging business and revenue opportunities that can be exploited by discerning players in the financial services industry. Specifically, the following areas will provide significant opportunity to players in the financial services industry:
Payments: The Central Bank of Nigeria’s renewed drive on cashless policy has provided an opportunity for players in the financial services industry to enhance existing digital product offerings and create more attractive product offerings that will further reduce frictions in the payment process. This will help to reduce the financial exclusion gap, increase fees and commissions revenues, and improve overall viability and stability of the financial ssystem
Digital Security: Increasing adoption of digital payments platforms will necessitate increased requirement for the security of payment channels. Thus, opportunities exist for players in the financial services industry to leverage robotics and artificial intelligence to improve security protocols on digital payment channels.
M & A Opportunities: with the anticipated pressures on earnings, opportunities exist for big and liquid players to gain additional scale and market share through outright acquisition of fringe players with the right strategic fit. There is also an opportunity for two or more small and/or medium size players to merge their operations/businesses to obtain scale advantage.
Partnerships across Segments: The growing number of Fintechs and licensed Payment Service Banks also presents an opportunity for improved partnerships across various categories of players in the financial services industry for both mutual and industry-wide benefits.
Consumer Lending: Tightening financial conditions of the average household will create opportunities for consumer loans in several variants such as buy-now-pay-later (BNPL), salary advance, consumer asset finance, etc. The industry is already witnessing a rising trend in the creation of digital consumer loan product offerings. This is likely to intensify in 2023.
What are the key events that will shape 2023 domestic economic outlook and how strategically positioned is FirstBank to manage the challenges and opportunities?
Three key events will shape the 2023 macroeconomic outlook of Nigeria: The outcome of the 2023 general elections and peaceful political power transition; government’s ability to curb crude oil theft and increase production to meet OPEC quota; and successful removal of petrol subsidy. For us at FirstBank, we are strategically positioned to take advantage of and harness the opportunities that the three key events will bring as well as successfully ride the waves of any challenges that may arise. For over 128 years, FirstBank has built the capabilities and competencies required to succeed and thrive in any macroeconomic situation. As a Bank, our belief and commitment to the domestic economy is unwavering – FirstBank is truly woven into the fabric of the society.
How will you define the trends we saw in the banking sector landscape in 2022?
2022 was quite an eventful year and some visible trends emerged. I would like to classify the trends as follows:
Financial System Trends: The Monetary Policy Committee (MPC) raised the monetary policy rate and the cash reserve ratio, cumulatively, by 500 basis points to 16.5 per cent and 32.5 per cent, respectively as a way of enforcing liquidity tightening measures to curb rising inflation. In the same vein, the interest rate on savings accounts was restored to the pre-pandemic levels of 30% of MPR within the year thereby increasing the interest expense profile of banks. In addition, the paucity of foreign exchange exerted considerable pressure on banks’ foreign currency (FCY) trade lines in the course of the year, forcing banks to explore alternative ways to meet customers’ foreign currency needs, including deliberate focus on supporting and promoting non-oil export businesses and transactions.
Technological Trends: The banking sector witnessed an increase in technological innovations, as the industry strived to meet the ever-evolving customer needs. In Nigeria, FirstBank was at the forefront of the technological trend, as we successfully launched a Digital Experience Center, a fully automated branch to meet our customer needs, while providing a unique and wholesome experience. FirstBank also launched robotics process automation initiative, FirstRobotics, that uses artificial intelligence and machine learning to handle high volume transactions The industry also witnessed increasing collaboration of banks and fintechs in 2022; enhanced digital product offerings, especially the rise in digital loans and advances; and an overall increase in acceptance of digital product offerings by banks and other financial services players.
Customer Trends: In 2022, we witnessed an increasing shift in emphasis from consumer banking to lifestyle banking in a bid to capture more of the customers’ journey. This shift has been hugely supported by technology as customer trends can now be easily identified, and new product offerings developed to meet customer needs. The emigration trend witnessed in the past year also led to a boost in the industry’s diaspora customer base, leading to increased focus on meeting the needs of this peculiar customer segment.
Employee Trends: The banking industry, probably like any other industry in Nigeria, has seen significant attrition in the number of employees due to increased relocation to other countries (popularly known as Japa) in 2022. This has impacted the industry’s skill base and execution capabilities especially in critical areas of the industry. While this may be a national challenge, more creative ways must be explored to retain scarce talents for national development.
The Central Bank of Nigeria and the Federal Government have set a target of 95 per cent financial inclusion by 2024, how realistic is this target and what role will First Bank be playing to support the government achieve this target?
Financial inclusion is usually seen as the gateway to economic prosperity as it signals the first step in the journey to financial freedom. In 2012, the Central Bank of Nigeria (CBN) had unveiled its National Financial Inclusion Strategy with the principal goal of reducing the nation’s financial exclusion rate to 20 per cent of the adult population by 2020. Although this goal was not achieved (as financial exclusion rate stood at 35.9 per cent at the end of that period), the nation had nonetheless made giant strides in raising financial inclusion levels from that take-off point. As such, while the CBN’s revised target of 95 per cent financial inclusion rate by 2024 may be audacious, it is achievable given the level of financial awareness that has already been created in previous years which has raised financial literacy among the average citizenry. In addition, in view of the additional investments and infrastructural base that is available in the country, more mileage can be made now than ever before. It should also be noted that the Central Bank of Nigeria has been deliberate in pursuing its financial inclusion agenda through the licensing of several players/operators in the financial services industry, including fintechs, mobile money operators, Payment Service Banks (PSBs), Microfinance Banks/institutions, new deposit money banks (DMBs), etc. As such, several players are making various attempts at solving the same problem which will significantly increase the likelihood of success. As the foremost financial institution in Nigeria, FirstBank has always collaborated with the Central Bank and the Nigerian government to push several national initiatives, particularly as it relates to the financial services industry. Specifically, FirstBank’s Firstmonie Agent Network is fully aligned with improving financial inclusion in Nigeria. With over 196,000 agents spread across 772 Local Government Areas (LGAs) in Nigeria and many of the agents operating from 512 LGAs without a FirstBank branch, the Bank has been a clear partner to the Central Bank of Nigeria in improving financial inclusion in the country. FirstBank’s USSD (*894#) product, which is demographically positioned for the unbanked, has over 14 million users with more than 261 million unique transactions, worth over NGN1.1 trillion processed on the platform. FirstBank has been at the forefront of increasing financial inclusion in Nigeria and will continue to play its part until every adult in Nigeria is adequately banked.
What is your take on two recent policies of the CBN – the naira redesign and the cash withdrawal limits?
The CBN as the apex regulator of the financial services industry has overall responsibility to ensure the soundness of the nation’s financial systems. In discharging this responsibility, it develops policies that are meant to strengthen the monetary environment and stimulate further economic development of the country – the recent naira redesign and cash withdrawal limits policies are part of its core mandate. As noted by the CBN, the naira redesign will improve both the integrity of the local legal tender and the efficiency of its supply, thus addressing a situation where 80 per cent of currency in circulation is outside the banking system. To aid its implementation, the CBN has also suspended charges on cash deposits to encourage everyone to deposit old naira notes in the Banks. The new N200, N500 & N1000 notes which came into circulation on 15th December 2022 will co-exist with the old notes until 31st January 2023 when the old notes will cease to be legal tender in Nigeria.
Similarly, the cash withdrawal policy which will limit weekly cash withdrawals by individuals and companies to N500,000.00 and N5,000,000.00 respectively, is expected to accelerate Nigeria’s transition to a digital economy. The policy which comes into effect from January 9, 2023, will present the added advantage of bringing more people into the banking system thus improving financial inclusion. At FirstBank, we view both policies as business enablers with bright prospects and we are poised to take maximum advantage of the opportunities they bring to improve our service offerings and the overall experience of our customers.
FirstBank has a lot of Firstmonie agents scattered around the country, how will the cash withdrawal limit affect their operations?
As at November 2022, FirstBank has over 196,000 Firstmonie agents spread across 772 Local Government Areas (LGAs) in Nigeria. These agents have also processed over 1.16 billion transactions valued at N26.52 trillion. About 45 per cent of our Firstmonie Agent network are in rural areas, 18 per cent located in semi-urban areas and only 37 per cent are in urban areas. Beyond Cash-in-Cash-Out (CICO) transactions, these agents also render other services such as account opening, airtime purchase, bill payment, government-revenue collection, transfer and disbursement, mobile-money (wallet creations, deposits, withdrawals), bank verification number (BVN) enrollment and other non-bank ecosystem value-added support services, in line with CBN’s guideline for Mobile Money and Agent Banking businesses. These services have helped to bring banking services closer to local communities thereby empowering them and facilitating their economic development. Through Firstmonie, FirstBank provides convenient low-cost financial access for millions of Nigerians in rural areas. Therefore, given the spread of our agent banking network and the scope of services they offer, the cash withdrawal limit is not likely to have an adverse effect on their operations. In reality, we see it as an enabler that will bring more people into the banking system. The new cash withdrawal limit will help to drive the penetration and uptake of digital/mobile wallet offerings in the industry.
FBN Holdings doubled its Q3 2022 profit to N105 billion and the performance by the bank was the major contributor, can you take us through the drivers of the impressive Q3 result?
FirstBank’s Q3 2022 results reflect the robustness of our business model and go-to market approach even in a challenging business and operating environment. The impressive profitability performance was driven by the resilient execution of our strategy and transformation program. Specifically, FirstBank delivered a 42.4 per cent year-on-year (yoy) increase in interest income on the back of yield optimisation on existing assets and addition of about N700 billion to the risk asset portfolio. Also, the bank recorded a decent 6.8 per cent growth in fees and commission within the period driven by significant improvements in LC commissions, account maintenance charges etc. The bank also recorded over 47 per cent y-o-y increase in other operating income within the same period. Overall, I would say that the results are a clear outcome of the collective efforts and resilience of the entire staff and the Board of Directors of the FirstBank Group in deliberately executing on our transformation agenda. We remain confident that our growth trajectory is sustainable, and we are focused on delivering on our 2020 – 2024 strategic ambition of accelerated growth in profitability through customer-led innovation and disciplined execution.
What is the level of non-performing loans and what has the bank been doing to reduce it?
FirstBank Group has achieved great strides in reducing its NPL from double-digit in 2016 to below regulatory benchmark of five per cent in Q3 2022, which attest to the fact that the bank is strong and resilient. FirstBank has, in the recent years, built an enduring risk culture and governance systems, as well as strengthened its risk management infrastructure through technology, process automation and specialised ttraining
Few years ago, FirstBank embarked on a business expansion drive within the continent, can you take us through the performance of your subsidiaries in the continent?
FirstBank embarked on its African expansion in 2011. Today, the Bank is present in six other African markets namely: Ghana, Senegal, Sierra Leone, The Gambia, Democratic Republic of Congo, and Guinea. As part the 2020 – 2024 strategic plan, FirstBank refreshed its vision to be “Africa’s Bank of First Choice” to serve as an anchor for its renewed African expansion drive. As such, the Bank is exploring entry into additional high-impact African markets. While the growth journey of each African subsidiary is different, we are extremely proud of the investments that we have made in these markets and the positive contributions we are beginning to see from each subsidiary. Overall, I would like to note that all our African subsidiaries are making positive contributions to the Group in terms of profitability.
How is the bank positioning to take advantage of the AfCFTA?
The African Continental Free Trade Area (AfCFTA) agreement has created the largest free trade area in the world (measured by the number of participating countries) as it involves most of the 55-member countries of the African Union with a combined Gross Domestic Product (GDP) of $3.4 trillion and connects 1.3 billion people across the continent. According to the World Bank, the AfCFTA has the potentials to lift 30 million people out of extreme poverty and raise the incomes of 68 million others who live on less than $5.50 per day. It also has the potentials to drive $292 billion in income gains for participating members. FirstBank is already actively playing in seven African countries with plans to enter additional high-impact African markets in the short to medium term. The bank has also institutionalised a collaboration framework across all operating jurisdictions to ensure clients operating in multiple African jurisdictions can be effectively served across the network. The bank has developed special products (known as First Global Transfer) to facilitate regional payments for our pan-African clients in addition to our online and digital platforms. On the part of the customers, FirstBank has conducted several non-oil export seminars to raise awareness levels on the opportunities presented by AfCFTA and equip our clients with the right knowledge to exploit these opportunities. As a bank, we view AfCFTA as an enabler of our corporate vision and we will continue to ensure the right investments are made to capture the opportunities it presents.
Your UK subsidiary recently marked its 40th anniversary, what was the journey like in that 40 years and looking ahead, what should customers be expecting from FirstBank in UK?
FirstBank’s foray into the United Kingdom (UK) forty years ago is a clear demonstration of uncommon foresight by the leadership of the Bank. Given the burgeoning trade relations between Nigeria and the then European Union (which included the UK) and the growing status of London as a leading global financial center, the decision to establish a subsidiary of FirstBank in the UK could not have been better made. Since commencement of operations in the UK, FBNBank UK has provided a bridge for Nigerian firms with interests in the UK to achieve their financial goals and meet their banking needs. FBNBank UK has provided trade and correspondent banking relationships that have facilitated the achievements of several Nigerian and indeed other African entities’ trade objectives. This is in addition to offering other services such as advisory, mortgage and investment products to its clientele base. FBNBank UK has also provided access to foreign capital markets to African firms and countries to raise much-needed capital that have contributed to the economic transformation of the African continent. As we look to the future, customers of FBNBank UK can be assured of the same excellent services they have become accustomed to with more innovative products that will help them solve their emerging needs.
We saw the licencing of a few banks in 2022 and the industry becoming more competitive, why should your customers continue to bank with FirstBank?
Indeed, the industry has changed and will continue to evolve at a faster pace with the competitive landscape becoming more challenging because of the inter-play of several actors – new banks, fintechs, etc. However, customers will continue to gravitate towards institutions that provide the best digital banking services that address their changing needs for convenience, speed, and security. With over 128 years’ experience in this market, we believe that FirstBank is well positioned to continue to delivery excellent customer experience and thrive. Our customers can bank on our commitment to continuously re-invent our processes and products to meet both their present and future financial needs. The bank will intensify ongoing efforts to simplify banking for every customer segment leveraging cutting-edge digital capabilities and platforms that make banking more seamless. Combining our deep local knowledge of this market with our unmatched physical presence, FirstBank customers will always have an edge over their competitors. Our rich bouquet of products and service offerings also guarantees there will always be the right product for every customer, with each customer interaction constantly made better through data-driven insights. Our “You First” brand promise to our customers is a commitment that will always keep us on our toes until every customer’s financial needs are excellently satisfied. Overall, to the customers, we commit to provide the best value proposition and deliver exceptional customer experience.
FirstBank has made good progress in positively impacting the communities where it operates. Can you speak about some of these?
At FirstBank, we are committed to nation-building and have been driving sustainable social, economic and environmental growth for over 128 years of our existence. Our community development initiatives are anchored on our strategic Education, Health and Welfare pillars. Our engagement in sustainable business practices is based on our promise of enhancing social and economic development as well as contributing to environmental sustainability for the present and future generation.
Our key programmes include Infrastructure Development programme; Endowment programme; Future First (Financial Literacy, Entrepreneurship and Career Counseling); E-Learning Initiative; SPARK (Start Performing Acts of Random Kindness) and CRS Week. First Bank Infrastructural Development programme is aimed at promoting infrastructure development under its identified areas of support. This includes providing infrastructure facilities in schools, hospitals and environmental infrastructure projects. This is in recognition of the importance of these facilities in improving the quality of life. We have built over 16 infrastructure projects which include universities and secondary and primary schools. The FutureFirst programme in partnership with Junior Achievement Nigeria has impacted Over 1,000,000 people across the regions of the country including Lagos, Port Harcourt and Abuja with knowledge of financial literacy and entrepreneurship. Over 175,000 students have benefitted from the E-learning initiative thus far. This include 20,000 indigent students that have received free low-end devices preloaded with accredited content. SPARK which was introduced in the maiden edition of the Corporate Responsibility & Sustainability (CR&S) week in 2017 espouses reigniting our values which appear to be eroding fast.
The initiative focuses on creating and reinforcing an attitude of going beyond just meeting the material needs of people who are unable to help themselves to showing compassion, empathy, affection. In 2022, over 8 million people were impacted including students underprivileged including widows in 8 countries including United Kingdom, Ghana, DRC, Guinea, Sierra Lone, Senegal & Nigeria. We had partnerships with over 100 Charities / NGOs including LEAP Africa; International Women Society; UNGC; UN Women; Junior Achievement Nigeria. In addition, one of our long-term approaches to sustainability includes minimising the bank’s direct and indirect impact on the environment. So, beyond our education and health interventions, the bank has been employing international best practices tools to manage risks in the lending process in accordance with our subsisting Environmental Social and Governance Management System. Over N6.2 trillion worth of transactions were screened for ESG risks. We are partnering at the moment with the National Conservation Foundation on the Green Recovery Nigeria (GRN), as part of the Bank’s climate initiative which includes driving afforestation and reforestation.
brand
AUBA Commences Comtempt Proceedings Against WEMPCO Directors over Alleged Disobidence of Court Order
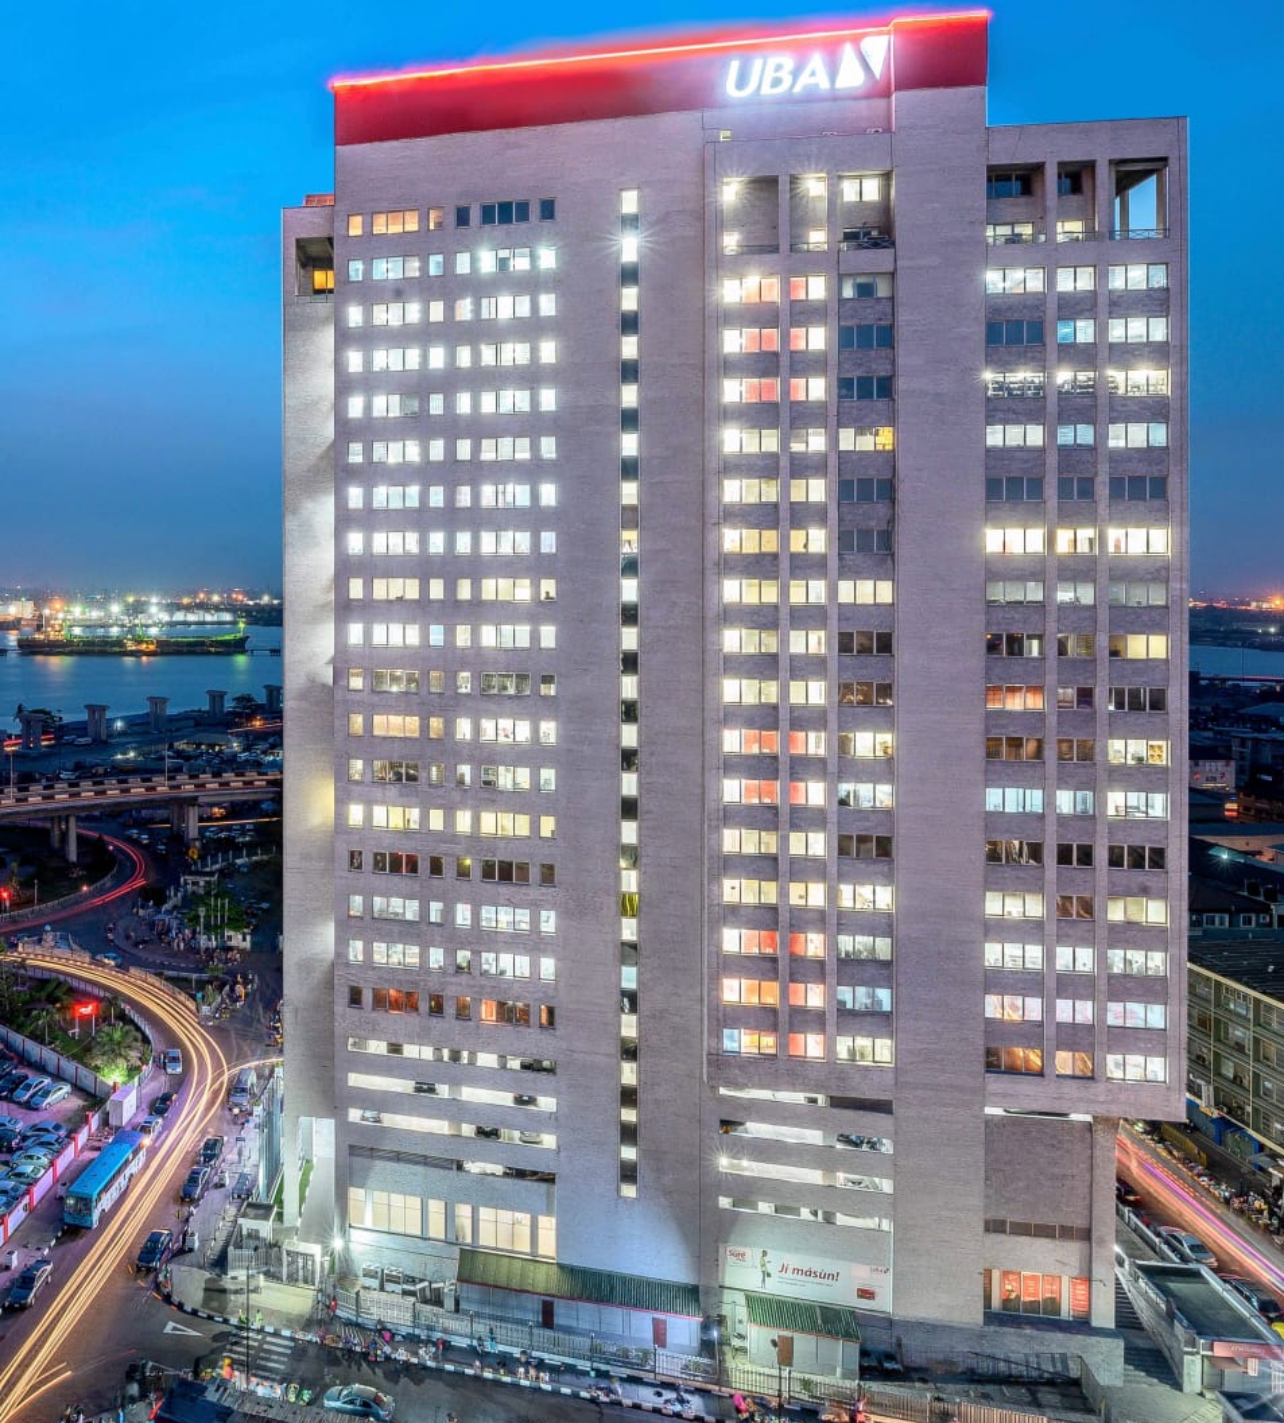
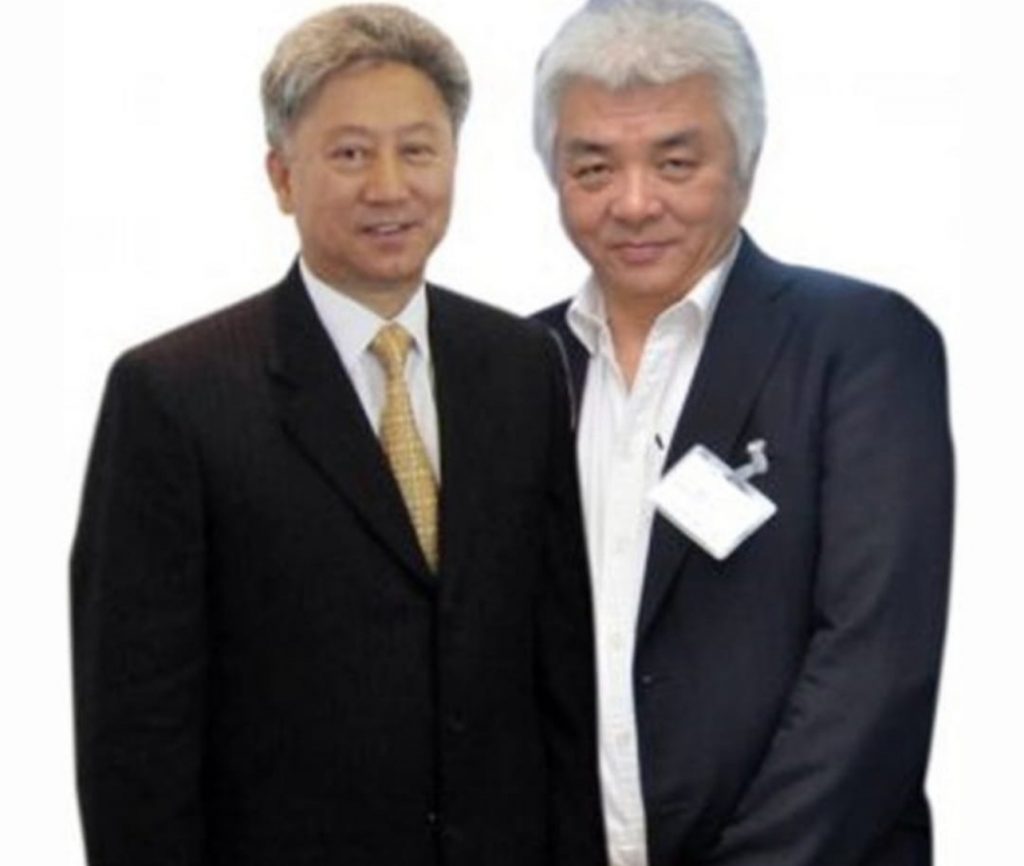
Mr. Lewis Tung and his brother Robert Tung
The Federal High Court, presided over by Honourable Justice Aluko, has granted an application by United Bank for Africa (UBA) Plc for substituted service of Form 49 on directors of Wempco named as alleged contemnors in the case of UBA v. Wempco.
The application forms part of proceedings seeking to determine whether the named individuals disobeyed an order of the court and whether they should be committed to prison for contempt.
The directors named as alleged contemnors are Lewis Shui Ngor Tung, Phillip Shui Chei Tung, M.A. Ola Yusuf, Tung Lawrence Blake, Aali Aare Hadji Tokunbo, Paul Shui Po Tung, Tung Robert, C.L. Ip and Taiwo Alli.
In advancing the application, counsel to UBA argued that service of Form 49 on the alleged contemnors was necessary to enable them to appear before the court and show cause why an order of committal should not be made against them.
He also argued that the Directors of Wempco and some members of staff took illegal steps in an attempt to disobey the Order of Court.
The court’s decision to grant substituted service provides a procedural step towards bringing the notice to the attention of the individuals concerned in accordance with the court’s directions.
Form 49 is a notice requiring an alleged contemnor to show cause why an order of committal to prison should not be made against them for alleged disobedience of a court order.
The Federal High Court had earlier made an Order of Mareva Injunction and appointed a Receiver/Manager over some of the Assets of Wempco following the indebtedness of Wempco to UBA in the sum of N61,445,695,993.76 (Sixty One Billion FourHundred and Forty-Five Million Six Hundred and Ninety Five Thousand, Nine Hundred and Ninety Three Naira, Seventy Six Kobo).
 A Lagos State High Court, last Thursday, granted interim preservative orders of Mareva Injunction against Vitol SA – a Switzerland based Energy Trading company, and four other shipping companies in favour of United Bank for Africa Plc.
The bank alleged Vitol of wrongful release of cargoes of petroleum products which were consigned to the order of United Bank for Africa Plc in the Bills of Lading.
Addressing the Court, Bode Olanipekun, SAN, lead counsel for United Bank for Africa, urged the Court to grant the interim preservative orders against Vitol and the other shippers.
In a ruling on the application, the presiding judge, Honourable Justice K. A. Jose (Mrs.) granted three prayers in UBA’s application, including requests to restrain the dissipation of assets and dealings with funds up to the disputed amount by Vitol S.A.
“Prayers 1–3 are granted as prayed against the 2nd Respondent only,” the judge ruled.
The application was brought pursuant to Order 43 Rule 1 of the High Court of Lagos State (Civil Procedure) Rules 2019 and the Lagos State High Court Practice Direction No. 2 of 2019.
UBA is seeking to contend in the substantive proceedings that Vitol SA and the owners of the vessels, are liable for alleged conversion, misrepresentation and negligence arising from the non-delivery of the petroleum products.
UBA also cited 34 financial institutions and public agencies, including commercial banks, merchant banks, microfinance banks, the Nigerian Ports Authority and the Nigeria Customs Service, in connection with the application.
In an affidavit supporting the application, UBA’s Group Head of Recoveries and Remedial Management, Anthony Chilaka, stated that the bank issued a letter of credit for the benefit of Vitol SA to facilitate a petroleum products transactions.
UBA alleged that the cargo was transported to Nigeria and that the vessels’ masters issued several bills of lading.
The bank further alleged that Vitol subsequently endorsed the bills of lading “to the order of” UBA and handed over the original copies to it.
UBA maintained that the endorsement entitled it to take possession of the cargo upon completion of the voyage.
However, Chilaka stated that the bank had not received the gasoil despite the completion of the voyage.
“The applicant has not been given possession of the gasoil despite completion of the voyage,” the affidavit stated.
UBA alleged that the cargo was instead, applied to the use of another party, contending that the respondents’ failure to deliver it amounted to conversion and negligence.
The bank argued that the respondents had obligations arising from the transaction and the endorsement of the shipping documents, which it claimed were not fulfilled.
The bank alleged that the cargoes associated with those transactions were also diverted to the use of other parties after their voyages, rather than delivered to UBA.
brand
BANKING ON HER TOMORROW: ZENITH BANK EMPOWERS 300 GIRLS WITH EDUCATION, KNOWLEDGE AND CONFIDENCE
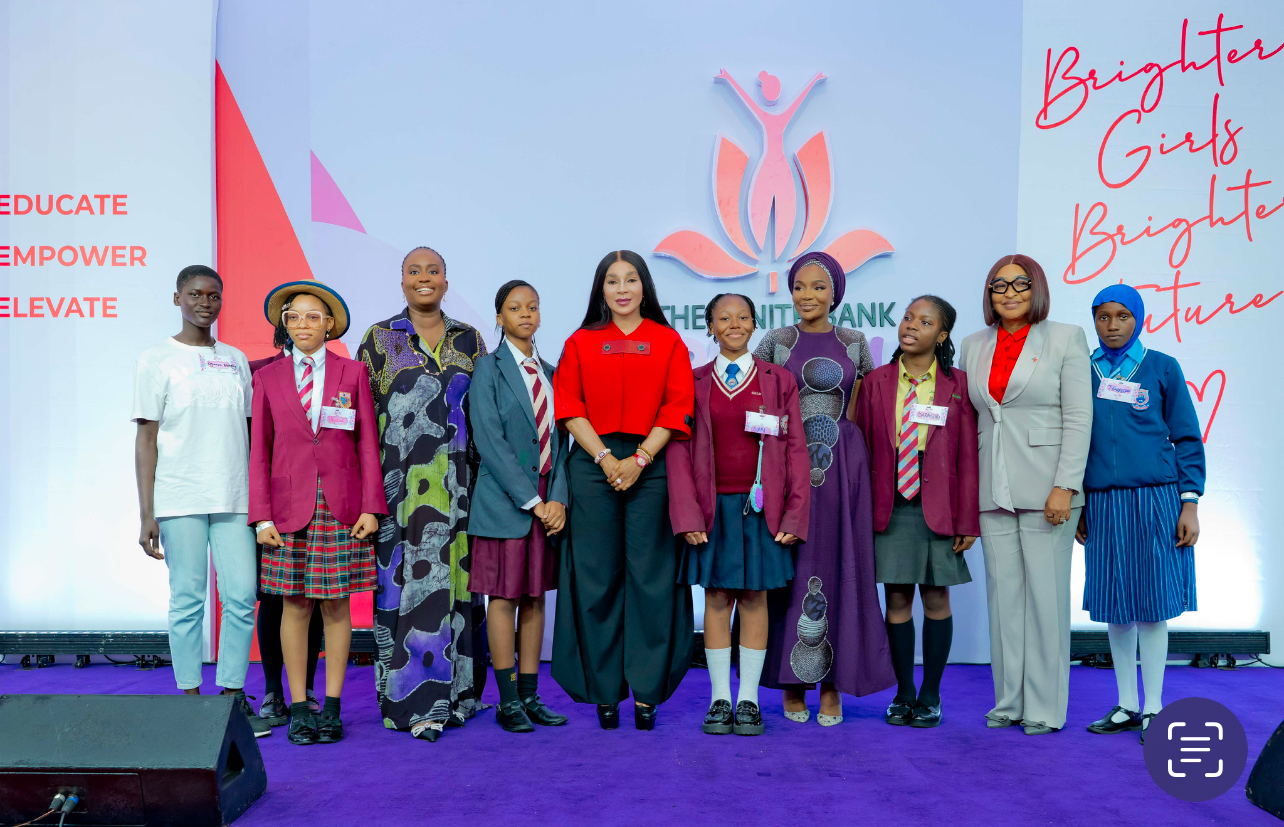
Zenith Bank Plc has launched the maiden edition of its Girl-Child Empowerment Programme, themed “Banking on Her Tomorrow,” bringing together 300 schoolgirls aged 13 to 17 from selected schools across Lagos for a day of learning, mentorship and personal development.
Held on Monday, October 12, 2026, at the Civic Centre, Victoria Island, Lagos, the programme featured sessions on finance and investment, etiquette and personal development, social media ethics, and social relationships and interactions, equipping participants with practical knowledge and skills for their personal, educational and future career journeys.
The initiative, a brainchild of the Bank’s Group Managing Director/Chief Executive Officer, Dame (Dr.) Adaora Umeoji, OON, reflects Zenith Bank’s commitment to nurturing the potential of young girls and helping them make informed choices about their futures.
In her welcome address, Dame (Dr.) Umeoji urged the participants to believe in their abilities, pursue their ambitions and remain focused and disciplined. Drawing on examples of young girls who have achieved remarkable feats, she challenged them to look beyond their present circumstances and envision the women they aspire to become.
“To all my amazing young ladies here today, each of you possesses gifts, talents, and ideas that are capable of revolutionising the world. You can revolutionise the world with your ideas,” she said.
The GMD/CEO further encouraged the girls to explore their interests and resist societal limitations, stressing the importance of taking ownership of their futures.
“Never allow gender or age to limit your goals. Whatever interests you today, explore it. Whatever you choose to pursue in life, give it your best shot,” she said.
Delivering the keynote address, Her Majesty, Olori Atuwatse III, Queen Consort of the Warri Kingdom, encouraged the girls to embrace their identities, develop resilience and use their abilities to make a positive difference in the lives of others.
Using the mangrove tree as a metaphor for resilience, she reminded the participants that challenges need not define their futures and that their worth extends beyond academic results and external expectations.
“Every time you affirm the truth about who you are, you are building confidence. Every time the tide of life goes out and you are still standing, you are building resilience. And every time you use your gifts for another person, you are discovering your purpose,” Olori Atuwatse III said.
The programme featured interactive sessions led by accomplished professionals and personalities:
Ayanime Edem, founder of The Elite Finishing School and modern etiquette educator, discussed confidence, communication, self-presentation and etiquette.
Nigerian actress and content creator Bukunmi Adeaga Ilori, popularly known as Kie Kie, addressed responsible social media use, authenticity and digital boundaries.
Representing Zenith Bank, Thelma Okonye and Adesola Adeyemo introduced the girls to saving, responsible money management and investment, highlighting the importance of developing sound financial habits early.
While Nigerian filmmaker, creative executive and educator,Praise Onyeagwalam, Director Pink, led a session on healthy relationships, self-awareness and effective communication.
The sessions encouraged active participation, giving the girls opportunities to ask questions and engage with the speakers on issues relevant to their experiences and aspirations.
The programme also featured competitions, with cash prizes totalling over ₦1 million awarded to winners. The participants received books to encourage reading and personal growth, while musical performances by Nigerian singers Qing Madi and No. 11 added to the lively atmosphere. The event was hosted by Temi Badru, public speaker, communications coach and lawyer, with Darasimi Destiny Nadi serving as mini host.
Delivering the closing remarks, Executive Director, Zenith Bank Plc, Dr. Mrs. Adobi Nwapa, highlighted the GMD/CEO’s vision for the initiative and the Bank’s commitment to sustaining its impact.
“The programme is the vision of our GMD/CEO, who conceived and championed it, demonstrating her unwavering commitment to the empowerment of the girl child. Through her leadership, she has shown the girls what is possible when a woman dares to lead. At Zenith Bank, our commitment to the girl child extends beyond today, and we will continue to nurture their aspirations through this annual initiative,” she said.
Dr. Nwapa thanked the speakers and participants for contributing to the programme’s success and encouraged the girls to apply the lessons learnt, remain confident and pursue their aspirations with determination.
The initiative builds on Zenith Bank’s longstanding commitment to advancing opportunities for women and girls through programmes including its annual International Women’s Day Seminar, the Zenith Women’s Basketball League, the Women of Honour Awards in partnership with the Ford Foundation, the Pad-a-Queen Initiative and Z-Woman, which supports women-owned businesses through business support and access to credit at discounted rates.
Through “Banking on Her Tomorrow,” Zenith Bank is extending this commitment to a younger generation, equipping girls with the knowledge, skills and confidence to pursue their ambitions and contribute meaningfully to their communities and society.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title