brand
ADESOLA ADEDUNTAN, CEO, FIRSTBANK – HOW TO DO WELL BY DOING GOOD

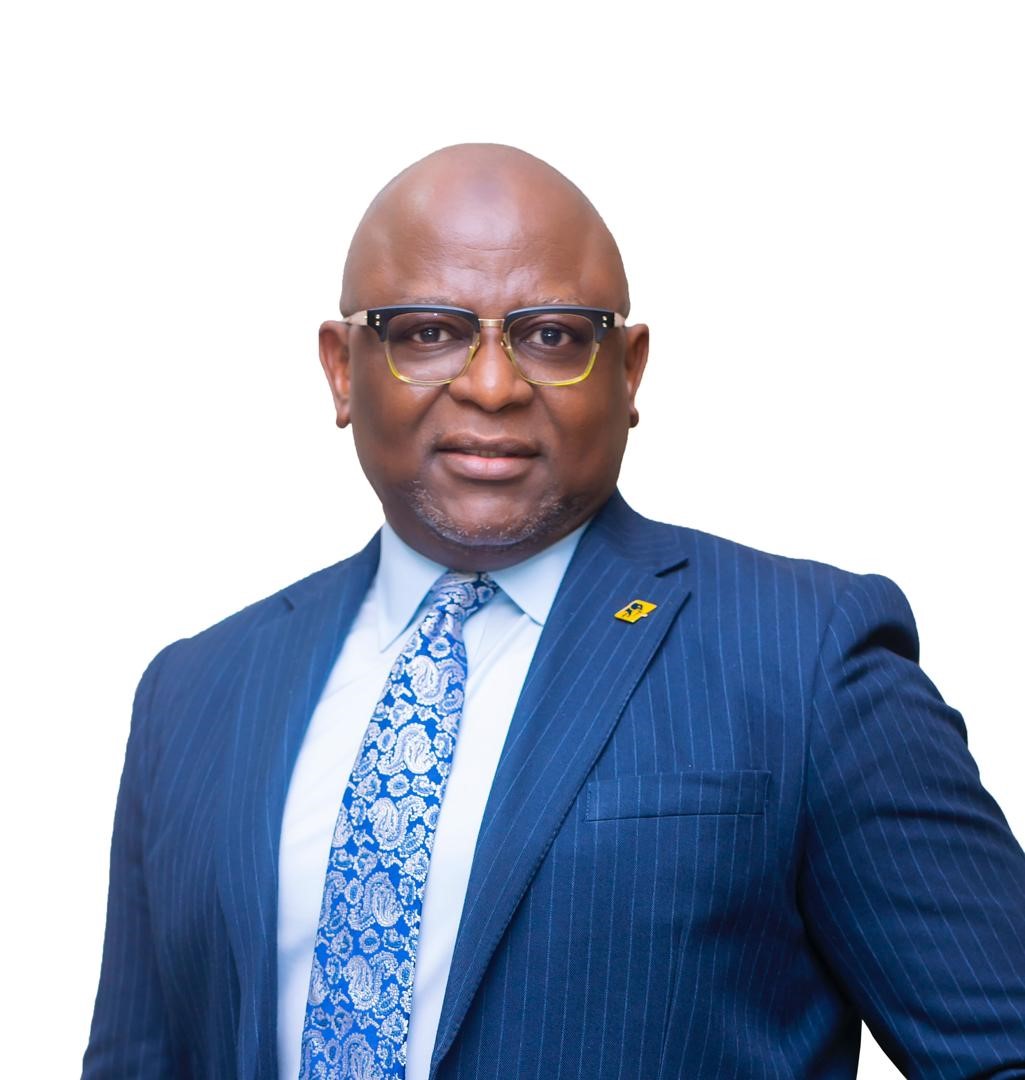
I travel to meet Dr Adesola Adeduntan in Edinburgh, where he has been invited to give a keynote address at the Edinburgh School of Business about the role of financial institutions in driving financial inclusion.Fittingly, as you land in Edinburgh, you are greeted by billboards from different investment funds advertising their credentials in responsible and sustainable investment and how environmental, social and governance (ESG) considerations underpin their activities.
With economists and politicians questioning capitalism and the Western liberal model, today the emphasis is very much on a stakeholder-based approach, whereby growth and prosperity is more equally attributed and takes into consideration the needs of the wider community. Sustainable investment has become de rigueur among corporate jargon.
Dr Adesola Kazeem Adeduntan, CEO of First Bank of Nigeria, is a veteran in the Nigerian banking and corporate world. His overriding message, clearly expressed throughout his interview responses, and also at the various talks he gave during the day (at the Business School and at a law firm), is on the importance of doing good if you’re to do well – financially – in Nigeria and indeed, Africa.
A telling sign
FirstBank is actually the oldest bank in Africa. It was established in Lagos in 1894 as the Bank of British West Africa. Last year it celebrated its 125th anniversary. It is also the biggest bank in Nigeria in terms of assets and branch network.
For Adeduntan, a veterinary doctor by training, it becomes clear, once we have settled down for our discussion, that the institution’s longevity is a telling sign: it not only proves the bank’s resilience, it also shows that it has the right structures in terms of governance and the right business model, with the country’s development at its core. The theme of the anniversary celebrations was about how the bank has been woven into the fabric of Nigerian society.
The clear message to the industry is that while it is possible to make a quick buck, you can only enjoy the sort of longevity it has if you conduct your business with the interests of the country at heart.
Nonetheless, it’s apparent Adeduntan does not want to dwell too long on past glories. Using the analogy of a car, he says that there is a reason why the windshield is large whilst the rear-view mirror is small.
The challenge of fintech
As in most sectors, traditional ways of doing business have been coming under increasing disruption from ever-evolving technology. The banking industry is no exception and seems to be under siege from an expanding fintech onslaught.
I ask him if he is worried that non-financial companies will be entering the banking sector, especially given the recent change in regulation by the Central Bank that allows non-traditional finance institutions, namely mobile operators, to enter the fray.
He says he is not worried as his bank has one of the best defined strategies when it comes to financial inclusion and that it has the largest digital banking network in Nigeria.
Much of this has been developed through the bank’s FirstMonie Agents system: 46,000 agents represent the bank across the country. Currently, 9m customers transact on their USSD platform (by mobile phone, both smart and analogue) in addition to 3m customers transacting on the FirstMobile platform.
The agent network, the biggest of its kind in the country, enables the bank to provide services to the most remote rural communities; and because it doesn’t need to have an extensive branch network, it means that these services can be supplied at a fraction of the cost of a ‘legacy’ banking model.
Financial deepening
Adeduntan prefers to use the phrase ‘financial deepening’ when talking about the unbanked. Financial inclusion has increased from the low 20s to approximately 40% in Nigeria over the past seven years and is expected to double to the mid-80s within the next five years.
He says ‘financial deepening’ occurs when financial inclusion starts playing an important role in economic development. It’s about layering additional products on the current agency banking network – services such as micro-credit, micro-insurance and micro-pension.
The aim is to provide value-added services whilst at the same time increasing the savings rate; this aspect, which is critical in driving investment rates, has been one factor behind Asia’s rapid growth.
It is in this area, he says, that the bank has a vital role to play and a distinct advantage over new entrants. Technology, he emphasises, will play a crucial part in broadening financial inclusion. In addition, it is important to partner and collaborate with different stakeholders such as NGOs and other organisations dealing with the bottom of the pyramid, to help them reach out to different groups and also improve financial literacy.
Last year saw a boom in venture capital investment into Nigeria. For example, $400m was invested in a number of fintech start-ups during November alone. Is he not worried that these fintech players, with their lower cost base and ability to use technology, AI and big data to overcome traditional hurdles, are going to take the majority share of the pie when it comes to servicing the unbanked?
He says that will only be the case if the banks do not manage to reinvent themselves. In Edinburgh, he actually spent a large part of his day visiting tech hubs around the university in the city and speaking to fintech companies. FirstBank, he adds, has a number of partnerships with fintechs as well as its own Digital Laboratory developing new solutions for the bank.
Nevertheless, he firmly believes that the ‘legacy banks’ will still continue to play a very central role, especially “in this part of the world where banks are quite dominant and they have significant buying power”.
In terms of settlements and deposits, he sees many of these new players as partners they can work with, even if in some areas they will be competitors.
Scope for growth
Despite the impressive strides made by the banking sector in Nigeria, Adeduntan believes there is still a massive scope for growth for the sector. He points out that none of the country’s top banks have made the Top 10 Banks in Africa list, despite Nigeria being the continent’s largest economy.
He thinks that with the signing of the African Continental Free Trade Agreement, “we are entering a very interesting period for the banking sector, not only in Nigeria but Africa in general”.
On the domestic front, does he expect further consolidation? “Within certain thresholds,” he answers. “Anything that would allow the strengthening of the entire banking sector, I am sure the Governor of the Central Bank would be positive about.”
He also points to demographics and the high rate of the unbanked as great opportunities for the growth of the sector continentally. “According to UNICEF, two billion babies will be born in Africa in the next 30 years,” he says. “And in places like DRC [where FirstBank has a presence] financial penetration is as low as 5%.” Put the two sets of figures together and, in theory at least, you get vast opportunity. But he adds the all-important caveat that demographics are only good if managed properly.
Supporting national champions
It hasn’t all been plain sailing for the bank, however. Adeduntan inherited a bank with several large exposures in the oil & gas and energy sectors, at a time when the oil & gas prices fell considerably, resulting in the devaluation of the naira against the dollar.
He says his management weathered the storm, reduced NPL levels to under double digits, and has strengthened the risk infrastructure, thus enabling the bank to better deal with cyclical downturns in future.
Discussing the role of large companies in the commercial landscape, Adeduntan says it is essential to have big banks like FirstBank, just as it is vital to have national champion companies that have the scale and wherewithal to make transformative investment. Such companies require financial institutions of similar scale to support them. The Dangote Group’s investment into what will become the continent’s largest oil refinery is a case in point, he adds.
Role of the Central Bank
We move on to the regulator and the role of the Central Bank. Does he think that it is too interventionist, dictating how much banks should lend, where they should place their assets?
Adeduntan refused to be drawn into criticism of the regulator, with whom he says he, and other bank CEOs, have a strong relationship. But he did say that the role of a central bank in the development of an emerging economy is clearly different from the role of a central bank in a developed economy.
“It is not unusual that the Central Bank intervenes in critical sectors allied to the loan to deposit ratio. It’s about economic growth; it’s about development; it’s about channelling credit in sectors that are very important for the national economy.
“Let us take agriculture – again, we are one of the biggest lenders into that sector. We found the Central Bank intervention in some of those critical sectors extremely useful and not just for us as a bank, but for the country as a whole. When you look at intervention in agriculture, you have to put it in the context of the size of the population. Nigeria is a country of 200m people today. The business of feeding 200m people is a strategic business. Everything that is being done to ensure that at least we are self-sufficient in food production is strategically important. We find the Central Bank intervention in those areas quite useful and of national importance.”
He reflected the positive attitude of many Nigerian entrepreneurs to the country’s future. He says he has a lot of time for the Economic Advisory Council – composed of credible business leaders and economists – that has been put together by President Muhammadu Buhari. And despite reports that the government is not economy-minded, he thinks that it is a pro-business government.
Ethical banking
It is nearly 10.00 in the evening when we finish our talk, his day having started at 07.30am. We go back to sustainability and the role of financial services to make sure they are lending to institutions that are ethical about their business and operating in a sustainable manner.
He says that the journey has started even if it is still early days. “But ultimately,” he says, “this is where we are headed. The Nigerian Sustainable Banking Principle speaks to this particular question. I think it’s evident from the points that I’ve made today, you can say that FirstBank is a bank that is happy to forego a few basis points in terms of its net margins, if that means it is contributing to development in a more ethical and sustainable way.
“We’ve always made a point that profitability is very important for us at FirstBank, but economic growth and national development is equally very important and speaks to the sustainability question.”
brand
GTCO Plc Releases 2026 Half Year Audited Results …….. Reports Profit Before Tax of ₦603.03billion,Pays Interim Dividend of ₦1
 Guaranty Trust Holding Company Plc (“GTCO” or the “Group”) has released its Audited Consolidated and Separate Financial Statements for the period ended June 30, 2026, to the Nigerian Exchange Group (NGX) and London Stock Exchange (LSE).
The Group posted a profit before tax of ₦603.03 billion, driven by strong performance recorded on the interest and trading income lines, which grew y-o-y by 7.5% and 24.7%, respectively. The strong earningsrecorded was moderated by a ₦46.2 billion fair value loss recognized in H1–2026, limiting y-o-y growth in PBT to 0.4%.
The Group grew across its asset lines, reinforcing a balance sheet that is well structured, liquid and diversified. This growth was recorded in each jurisdiction where we operate a banking franchise, and across our Payments, Pension and Funds Management businesses.”
Group’s Total assets and shareholders’ funds closed at ₦18.6trillion and ₦3.3trillion, respectively. Capital Adequacy Ratio (CAR) remained very strong, closing at 34.9% (Bank 29.2%), and asset quality improved as evidenced by IFRS 9 Stage 3 Loans which closed at 3.5% and 4.6% % at both Bank and Group Level in H1-2026 (Bank -3.4%, Group 5.0% in FY-2025). Cost of Risk (COR) improved to 0.6% from 2.2% during the same period.
The Group’s Loan book (net) grew marginally by 0.5% from ₦3.13trillion as of December 2025 to ₦3.15trillion in June 2026, converse for improved performance on Deposit liabilities which grew by 10.3% from ₦12.87trillion to ₦14.19trillion during the same period.
Commenting on the results, the Group Chief Executive Officer of Guaranty Trust Holding Company Plc (GTCO Plc), Mr. Segun Agbaje, said; “Our half year results speak to the strength of what we have built: a resilient franchise, a strong balance sheet and a business that no longer depends on banking alone. Fair value movements weighed on reported earnings, but the core business held firm. Interest and trading income grew, deposits strengthened, and asset quality improved at Group level. The priority now is to execute with discipline and grow responsibly. Digital is our lever for scaling across Banking, Payments, Pension and Funds Management, and for building a more diversified and resilient financial services group.”
Overall, the Group continues to post one of the best metrics in the Nigerian Financial Services Industry in terms of key financial ratios i.e., Pre-Tax Return on Equity (ROAE) of 35.9%, Pre-Tax Return on Assets (ROAA) of 6.6%, Capital Adequacy Ratio (CAR) of 34.9% (Bank: 29.2%) and Cost to Income ratio of 31.5%.
GTCO Plc is a leading financial services group with operations across Africa and the United Kingdom. Renowned for its strong corporate governance, innovative financial solutions, and customer-centric approach, the Group provides a wide range of banking and non-banking services including payments, funds management, and pension fund administration. The Group is committed to delivering long-term value to stakeholders while driving growth and development across its markets
 The road to the 2026 Zenith Bank NBBF Women’s Basketball League title reaches its defining stage as the nation’s top eight teams converge on the Indoor Sports Hall of the National Stadium, Surulere, Lagos, from September 28 to October 3, 2026, for the highly anticipated national Finals.
Emerging from fiercely contested Atlantic and Savannah Conference campaigns, Nigeria Customs, AS Sky Queens, Titans, Air Warriors, MFM, First Bank, Victoria Queens,and Bayelsa Blue Whales have earned their place in the final battle for national honours.
And there is plenty to look forward to.
Last year’s champions, Dolphins Basketball Club, who lifted the trophy after defeating First Bank in the final, will not be in the mix this year after failing to make the top 4 of the Atlantic Conference, leaving the title firmly up for grabs and setting the stage for a new champion to emerge.
But the trophy will be contested by teams with plenty of championship pedigree.
First Bank, last year’s finalist and the most successful team in the history of the competition, arrives with a record nine league titles, while MFM will be looking to draw on its recent dominance after winning back-to-back championships in 2023 and 2024. With both sides among the Final 8, history, experience and ambition will collide as the battle for the crown unfolds.
It is a level of competition that reflects the growth of a league that has, for more than two decades, provided a platform for Nigeria’s best female basketball talents to emerge, compete and develop. At the heart of that journey has been Zenith Bank, the sole sponsor of the National Women’s Basketball League since 2005.
Through its partnership with the Nigeria Basketball Federation (NBBF), Zenith Bank has consistently supported the development of women’s basketball, helping to provide and sustain a competitive platform where talents can be discovered, nurtured and prepared for the highest levels of the sport.
The league has also served as an important pathway to theNational Women Basketball team, D’Tigress, with several players who have featured prominently for Nigeria emerging from the domestic competition. Beyond the national team, the league continues to contribute to youth development by giving young female athletes the opportunity to build confidence, skill, discipline, teamwork and professional sporting careers.
Now, the spotlight turns to Lagos. Which team will grab theopportunity to write a new chapter in the history of Nigerian women’s basketball?
Eight teams. One destination. One crown.
For Zenith Bank, the sponsorship of the Women’s Basketball League represents more than support for a sporting competition. It reflects the Bank’s broader commitment to creating platforms that provide opportunities, develop potential and make a meaningful difference in the lives of young Nigerians.
This commitment extends across several areas of community development, with notable initiatives including:
Through these initiatives and its longstanding support for women’s basketball, Zenith Bank continues to demonstrate that its commitment to society goes beyond banking, with a focus on creating opportunities and contributing to the development of communities and the next generation.
I
Nigerians at home and in the diaspora seeking to participate in the landmark Initial Public Offering (IPO) of Dangote Petroleum Refinery and Petrochemicals can subscribe conveniently through Zenith Bank, a receiving bank for the historic transaction and a designated electronic application channel for the offer. Subscription is open through the Zenith Bank website, the Zenith mobile app, internet banking, USSD, corporate internet banking and any Zenith Bank branch nationwide.
Across all of these channels, anchored by Zenith Bank’s network of 456 branches and 84 cash centres, investors enjoy a secure, fast and reliable route into the offer from anywhere in the world, at any hour. Whether the application begins on a phone in London, a laptop in Houston or across the counter of a Zenith banking hall in Lokoja, the path to ownership opens with a few taps and carries the investor smoothly through to completion. Every subscription is linked to the investor’s Bank Verification Number, a seal of identity and security that accompanies each application from submission to allotment. It is service the Zenith way: first-time and seasoned investors alike enjoy a straightforward and fully protected process, and the quiet confidence that their stake in history is processed through Zenith Bank.
Applications open on Monday, 14 September 2026 and run for 30 days, closing on Tuesday, 13 October 2026. According to the prospectus, the shares are offered at ₦525 each, with a minimum subscription of 10 shares, or ₦5,250. The offer seeks to raise ₦2.15 trillion, the largest equity offering ever undertaken on the African continent, and the prospectus further provides that retail investors who subscribe and hold their shares may qualify for bonus shares under the Retail Investor Incentive Programme, subject to regulatory approvals.
Zenith Bank stands ready to make participation effortless for investors who choose to take part. Nigeria’s largest bank by Tier-1 capital and the country’s most profitable bank, Zenith has built its reputation on combining scale with innovation, and that strength is now at the service of every investor in this offer. This is proven ground for the bank: Zenith Bank’s own most recent public offering was executed mainly through digital channels, a demonstration of digital readiness built on the bank’s robust digital infrastructure. That infrastructure has since been strengthened further through a comprehensive technological overhaul, positioning Zenith to serve its retail customers with the same excellence long enjoyed by its corporate clients, precisely the capability an offer of this scale demands.
Within the wider transaction, Quantum Zenith Capital & Investments Limited serves among the joint issuing houses, while Zenith Bank itself provides the secure and dependable channels through which applications are received and processed. Having successfully taken its own landmark offer to the market through digital channels, Zenith brings that same tested infrastructure and experience to the largest equity offering in African history. It is the same combination of financial strength, digital excellence and customer devotion that has earned Zenith Bank recognition year after year as one of Africa’s foremost financial institutions, trusted by millions of customers and by the corporates and governments behind the continent’s biggest transactions.
For over three decades, Zenith Bank has been the trusted gateway to Nigeria’s defining financial moments, and its channels are open for this one. Investors who wish to participate can fund their Zenith Bank account and subscribe through any of the bank’s platforms before the offer closes on 13 October 2026.
Please note that the details of the offer are provided in the prospectus and guided by extant regulations. Zenith Bank serves as a Receiving Bank and electronic application channel for this offer. Investors are advised to carefully read the Prospectus and, where appropriate, seek independent professional advice before making any investment decision.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 entertainment2 years ago
Ashny Set for Valentine Special and new Album ‘ Femme Fatale’
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title