brand
Emefele, Olugbemi, Akinwuntan Insist Banks Must Play a Critical Role to Restore Stability to Nigeria’s Economy

Banking stakeholders have in unison insiisted that banks must play a critical role to restore the Nigerian economy from the negative effects of COVID-19. Speaking at the Chartered Institute of Bankers of Nigeria (CIBN) 13th Annual Bankers Conference in Abuja, the bank chiefs that included Godwin Emefiele, Governor Central Bank of Nigeria, Bayo Olugbemi, President/Chairman of Council, CIBN and Patrick Akinwuntan, Chairman of the Chartered Institute of Bankers (CIBN) Consultative Committee organizing the 13th Annual Bankers Conference and Managing Director Ecobank Nigeria noted that that it is imperative from an economic as well as a security perspective that banks work to support growth in sectors that have significant growth potential. These sectors they noted include Agriculture, Information Communication Technology and Infrastructure Finance amongst others.
In his presentation, the CBN Governor Godwin Emefiele said that our banking and financial system can enhance the resilience of the Nigerian economy, in the face of external shocks. According to Emefiele “we have witnessed the disruptions COVID-19 has had on global supply chains and food supply. If measures had not been taken earlier to improve cultivation and processing of staple crops in Nigeria prior to the onset of the pandemic, we would have had to deal with a major food crisis in the country. The banking sector therefore has a significant role to play as a facilitator of growth through its intermediation function”. He stated that “over the next 4 years, the banking sector should consider ways under which it could increase its loans to the agriculture sector from 4 percent to 10 percent by 2024”.
Further the apex bank Governor noted that “opportunities in the agriculture sector that banks should explore include addressing some of the existing gaps in the agriculture value chains, such as storage centers, transport logistics, and technology platforms, that can enable rural farmers to sell their produce directly to the markets. More importantly, he said the “agricultural sector also offers significant opportunity for the nation to earn foreign exchange through the exports of processed agricultural products. With declining foreign exchange earnings from crude oil, banks should consider supporting agro processing companies that are export oriented. These measures would help to improve productivity of farmers, increase our foreign exchange earnings, reduce post-harvest losses, while supporting the growth of other sectors of our economy such as manufacturing, and transportation”. He noted
According to Emefiele, another sector which has emerged as a significant source of resilience in mitigating the impact of Covid-19 on the economy, is Information and Communications Technology (ICT). He said in the “second quarter of 2020, the ICT sector made contributions of over 17.8 percent to GDP growth, 20 percent higher than its contributions a year earlier. It is important that we leverage ICT as an enabler for growth in key sectors of the economy”. He said “ICT start-ups are emerging to support SMEs, farmers, and in providing quality learning to students affected by the shutdown in schools. It is important that the banking sector consider viable IT firms in these areas that have the potential to not only serve the needs of the local market but are also able to export ICT related services to countries across the world”.
In his address, Bayo Olugbemi, President/Chairman of Council, CIBN, noted that “given the recent disruption caused by the impacts of the Covid-19 Pandemic, the role of banks have become more important now than ever before. According to him this year’s edition of the Conference aims to uncover and articulate the roles of the banking and finance sector in achieving a sustainable future for the country. He said the conference gives everyone the opportunity for an assessment of inclusive banking and the way forward, articulation of the risks of facilitating a sustainable future and positioning of banks in tackling risks, discussion on how Fintech is shaping the future through innovation and disruption, discussion on Green Banking and Economic Growth and the Impact of Finance on Emerging Sectors, spotlighting MSMEs, Manufacturing, Creativity and Agriculture Industry amongst others.
For Patrick Akinwuntan Nigeria need to move to the level of wealth creation, not just talking of poverty aliviation because we have the human capital and natural resources. We must therefore levarage technology, levarage access to fianance to be able to sopport the developing economy. He noted that the banks needs to support those who needs to grow their businesses, support those who need to invest in productive capacity. This according to him are some of the purpose of the 2020 annual conference, a message the institute is bringing to Nigeria. Further the Ecobank Nigeria Managing Director, reiterated that banks are unleashing digital platform to take financial services to the underbanked. He said the banks are determined to place Nigeria at the forefront of economic development in Africa.
The 2020 Annual Bankers conference themed; “Facilitating a Sustainable Future: The Role of Banking and Finance” has prominent bankers; major economic players; captains of industry; regulators; policy makers; members of the academic community and other stakeholders in the banking and finance industry in attendance.
The CIBN had adopted a hybrid approach for the two day event taking place simultaneously, at the Transcorp Hilton Hotel, Abuja and the Bankers’ House, Adeola Hopewell Street, Lagos and through Zoom teleconferencing. I n line with the theme, participants are evaluating the role of the Banking and Finance Industry in engendering an inclusive sustainable growth as well as offering a direction on how to reposition the Industry for relevance in the new world order, by leveraging on digitalization to boost Nigeria’s economy.
Leading financial institution, Fidelity Bank Plc, has partnered with the Federal Ministry of Humanitarian Affairs and Poverty Alleviation to provide support to vulnerable households in Abuja through its Food Bank programme.
Launched in April 2023, the Fidelity Food Bank is one of the bank’s flagship Corporate Social Responsibility (CSR) initiatives. The programme seeks to combat hunger and malnutrition by supporting communities affected by food insecurity. Since its introduction, more than 300,000 food packs have been distributed to beneficiaries across Nigeria’s six geopolitical zones.
Speaking at an event held recently in Abuja to commemorate the 2026 International Day for the Eradication of Poverty, the Managing Director and Chief Executive Officer of Fidelity Bank Plc, Nneka Onyeali-Ikpe, represented by the bank’s Divisional Head of Public Sector, Richard Madiebo, said the bank’s interventions extended beyond food distribution to entrepreneurship support and other empowerment programmes designed to help individuals and families achieve economic independence.
According to Onyeali-Ikpe, Fidelity Bank’s commitment to community development spans approximately three decades, reflecting its longstanding dedication to improving the wellbeing of its host communities.
“Fidelity Bank has always aligned its CSR programmes with the needs of its host communities. We understand the importance of private sector participation in addressing poverty and promoting inclusive development.
“We have delivered 2,000 food packs to residents of Abuja. There are several other initiatives that the ministry and the bank are discussing, and we will allow the ministry to provide further details at the appropriate time,” she said.
Also speaking at the event, the Minister of Humanitarian Affairs and Poverty Reduction, Bernard M. Doro, commended Fidelity Bank for contributing to efforts to improve the welfare of vulnerable Nigerians. He also called for stronger collaboration between the government and the private sector to address multidimensional poverty.
According to Doro, with 63 per cent of Nigeria’s population living in multidimensional poverty, a significant proportion of citizens remains excluded from economic activity, limiting businesses’ access to potential customers and employees.
“When 63 per cent of the population lives in multidimensional poverty, a substantial number of people are excluded from economic participation. This also means that businesses are unable to reach a large segment of their potential customers.
“Our responsibility as a ministry is to unlock partnerships with the private sector. Such collaboration is critical to expanding economic opportunities and bringing more people into productive economic activities. We are pleased that Fidelity Bank is fully committed to this effort,” Doro stated.
The minister urged stakeholders to move beyond declarations and ensure that poverty reduction initiatives deliver measurable and sustainable improvements in the lives of vulnerable households.
Ranked among the best banks in Nigeria, Fidelity Bank Plc is a full-fledged Commercial Deposit Money Bank serving over 9.1 million customers through digital banking channels, its 255 business offices in Nigeria and United Kingdom subsidiary, FidBank UK Limited.
The Bank is a recipient of multiple local and international awards, including the 2024 Excellence in Digital Transformation & MSME Banking Award by BusinessDay Banks and Financial Institutions (BAFI) Awards; the 2024 Most Innovative Mobile Banking Application award for its Fidelity Mobile App by Global Business Outlook; and the 2024 Most Innovative Investment Banking Service Provider award by Global Brands Magazine. Additionally, the Bank was recognised as the Best Bank for SMEs in Nigeria by the Euromoney Awards for Excellence and as the Export Financing Bank of the Year by the BusinessDay Banks and Financial Institutions (BAFI) Awards.
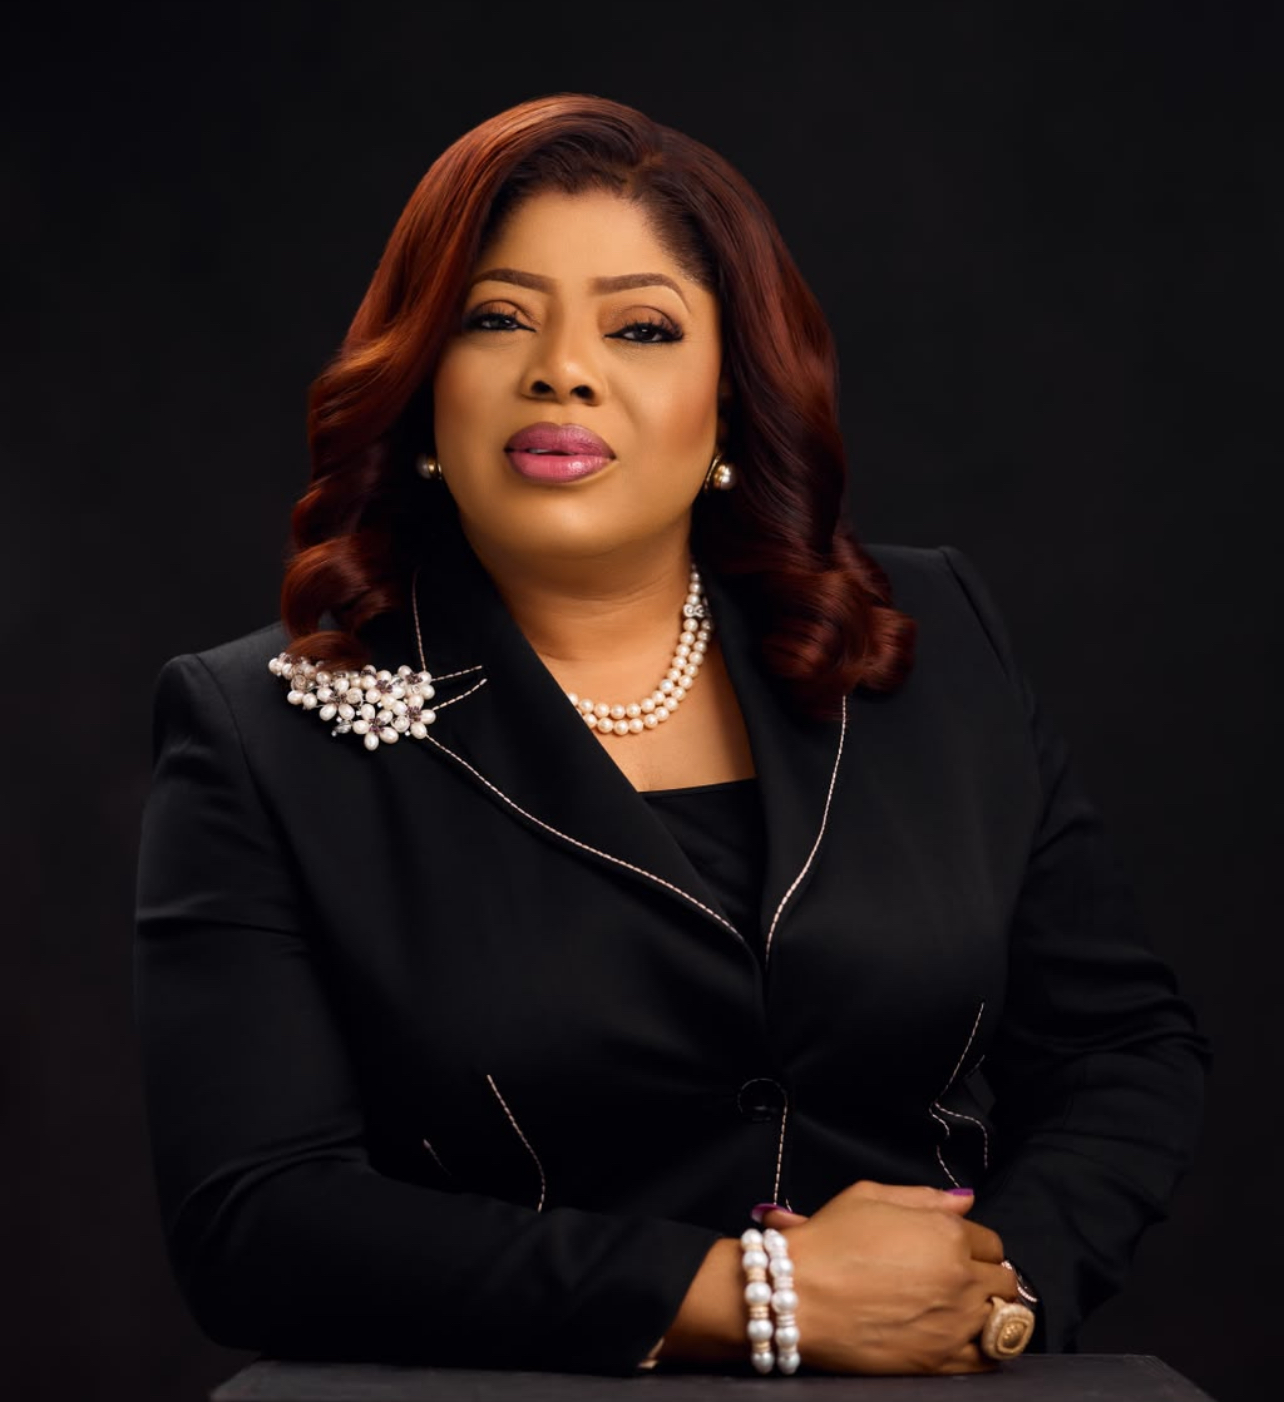
LAGOS, NIGERIA – Fidelity Bank Plc has successfully redeemed its 5-Year US$400 million Senior Unsecured Notes at maturity, reaffirming its commitment to meeting its obligations to investors and reinforcing its track record in the international debt capital markets.
Issued on 28 October 2021, the 5-year Eurobond matured on 28 October 2026 and carried an annual coupon of 7.625 per cent, payable semi-annually. Fidelity Bank met all scheduled coupon payments throughout the life of the instrument and has now fulfilled its final repayment obligation in full, covering both principal and accrued interest.
The redemption was funded from internally generated liquidity as part of the Bank’s forward-looking liquidity management strategy. Through a dedicated sinking fund, Fidelity Bank progressively provided for the maturing obligation, enabling the Bank to meet its commitment while maintaining business-as-usual operations and compliance with applicable regulatory liquidity requirements.
Commenting on the development, the Managing Director and Chief Executive Officer of Fidelity Bank Plc, Dr/Mrs Nneka Onyeali-Ikpe, said the successful redemption reflected the Bank’s disciplined approach to financial management and its commitment to delivering on its obligations.
“This successful redemption demonstrates the strength of our franchise, the discipline of our balance sheet management and our commitment to honouring our obligations to investors and other stakeholders. We anticipated this maturity from the outset and planned accordingly, which reflects our commitment to responsible financial management,” Onyeali-Ikpe said.
The redemption further strengthens Fidelity Bank’s record in the international debt capital markets. The 2021 issuance marked the Bank’s third Eurobond transaction, following earlier issuances in 2013 and 2017, wherein the Bank raised $300 million and $400 million respectively. The 2021 offer attracted investor orders exceeding US$700 million, reflecting strong demand for the Bank’s international debt offering.
The successful Eurobond redemption follows the completion of Fidelity Bank’s recapitalisation programme ahead of the regulatory deadline. The Bank’s capital-raising efforts increased its eligible regulatory capital to approximately ₦533 billion, exceeding the ₦500 billion minimum capital requirement for banks with international authorisation.
The completion of these milestones underscores Fidelity Bank’s strong capital position, prudent liquidity management and disciplined approach to financial execution. It also reinforces the Bank’s capacity to meet its financial obligations while pursuing its strategic growth objectives across domestic and international markets.
…….GTBank customers can now pay with it and businesses on HabariPay’s Squad gateway can now accept it.
Guaranty Trust Holding Company Plc (“GTCO” or “the Group“) today announced that two of its subsidiaries are live with Google Pay on the day it launches in Nigeria. Customers of Guaranty Trust Bank Limited (“GTBank”) can add their GTBank debit cards to Google Wallet and pay with Google Pay online, in Nigeria and internationally. Businesses that use Squad, the payment gateway run by the Group’s payments subsidiary HabariPay, can now offer Google Pay to their customers at checkout.
The Group is therefore present at both ends of the same transaction: with the person paying and with the business being paid.
For GTBank customers, the change is simple. They add their GTBank debit card to Google Wallet once. After that, they choose Google Pay at checkout, pick the card and confirm, without typing a card number, expiry date or CVV again. Google Pay replaces the card number with a secure digital token, so the merchant does not receive the actual card details. The card can be used wherever Google Pay is accepted online, including for subscriptions, travel bookings, food delivery, bills and digital services.
For businesses on Squad, “Pay with Google Pay” now sits at the top of the Squad checkout, alongside card, bank transfer, USSD, bank payments and Squad’s buy-now-pay-later options. A customer with a card in Google Wallet selects Google Pay, chooses the card, confirms, and is returned to the merchant’s site once the payment is verified. Google Pay is switched on by default for every business on Squad, and a merchant can choose to turn it off. Merchants set up for international payments can accept Google Pay from customers anywhere in the world, which opens Nigerian businesses to buyers abroad, including the diaspora. Fewer fields mean fewer points at which a customer can abandon a purchase, which matters most to the small and growing businesses that make up much of Squad’s merchant base.
Commenting on the launch, the Group Chief Executive Officer of GTCO, Mr Segun Agbaje, said: “Most failed online payments are not refused, they are abandoned. Somewhere along the way the customer gives up, and the business never learns about the sale it lost. As a customer centric Financial Services Group, we are committed to ensuring that we continue to deliver payment solutions that make transacting safe and simple for our various customer Groups. With Google Pay, what matters to us is that we are ready on both sides from the first day: a GTBank customer can pay with it, and a business on Squad can accept it.”
He added: “This is what a group structure is for. Our Bank and our Payments Business were built to do different jobs, and today they meet at the same checkout. We will keep putting the full weight of the Group behind those small moments where people decide whether paying digitally is worth the effort. When it is, everyone in the transaction wins: the customer, the merchant and the wider economy that depends on both.”
The Managing Director of HabariPay, Mr Eduofon Japhet, said: “For a merchant, every extra field at checkout is a reason for a customer to leave. Squad businesses now get Google Pay inside the checkout they already use, so their customers can pay in a few taps with a card they have already saved. A merchant set up for international payments can now be paid with Google Pay by a customer anywhere in the world, with nothing new to integrate.”
Availability. GTBank customers can add an eligible GTBank debit card through the Google Wallet app on Android or through their Google Account. From today, Google Pay is on by default for all businesses on the Squad payment gateway, and merchants can choose to turn it off. Squad merchants set up for international payments can accept Google Pay from anywhere in the world. More information is available at www.gtbank.com and www.squadco.com.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title