brand
FBNHOLDINGS: SETTING THE TONE FOR GENDER INCLUSIVENESS, BALANCE IN BOARDROOM


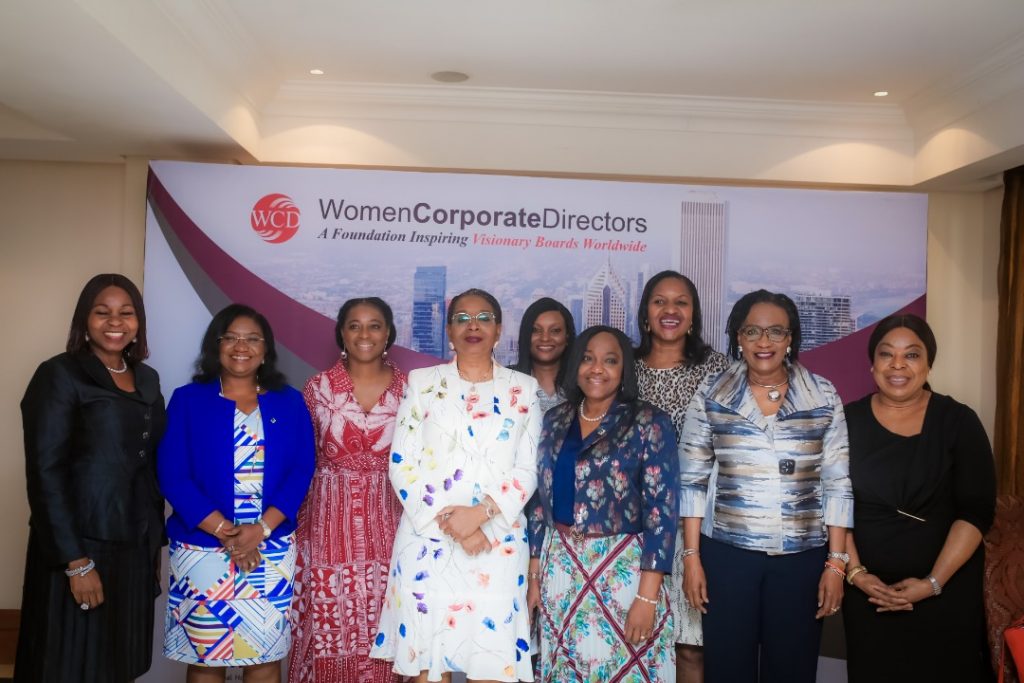
Bashirat Odunewu, Group Executive, Energy and Infrastructure, FirstBank; Cecilia Akintomide (OON), Independent Non-Executive Director, FBNHoldings; Folake Ani-Mumuney, Chairman, FBNInsurance Brokers/Group Head, Marketing & Corporate Communications, FirstBank; Ibukun Awosika, Chairman, First Bank of Nigeria Limited; Fiona Ahimie, Managing Director, FBNQuest Securities Ltd; Oluwande Muoyo, Independent Non-Executive Director, FBNHoldings; Ijeoma Nwogwugwu, Managing Director, ARISE News Channel Africa; Otunba Debola Osibogun, Non-Executive Director, FBNHoldings and Oyinkan Adewale, Independent Non-executive Director, FBNQuest Merchant Bank in a group picture at the Women Corporate Directors (WCD) Foundation, Nigeria Chapter, meeting hosted by FirstBank, to promote female leadership in management.
In many parts of the world, including Nigeria, women often face the barriers of discrimination and persistent gender inequalities which deny them access to key positions in the corporate world as well as access to finance or the formal economy.
Women make up almost half of the world’s working-age population of nearly 5 billion people. But only about 50 percent of those women participate in the labor force, compared with 80 percent of men, according to a report by the International Monetary Fund (IMF).
The IMF’s research highlights how the uneven playing field between women and men imposes large costs on the global economy. Early IMF studies on the economic impact of gender gaps assumed that men and women were likely to be born with the same potential, but that disparities in access to education, health care, and finance and technology; legal rights; and social and cultural factors prevented women from realizing that potential.
Nearly 70 UK companies have been told to employ more women in senior roles. Domino’s Pizza, JD Sports and Greene King are among those that have called out by financial trade sector body The Investment Association and the Hampton-Alexander review, a diversity study backed by the government.
The number of women holding the most senior jobs in the boardrooms of Britain’s biggest companies has fallen, according to a report that criticises the lack of progress made by businesses in getting more women to the top.
Analysis from Cranfield University, as part of its 20th FTSE Women on Boards Report, shows a sharp drop in the number of women occupying chief executive (CEO), chief financial officer (CFO) or other executive roles on FTSE 250 boards, and static numbers at FTSE 100 companies.
Women constitute almost half of the Nigerian’s population and its workforce. Yet the kind of work they do, the condition under which they work, and their access to opportunities for advancement at work place differ from that of men. Women are often disadvantaged in access to employment opportunities and in conditions of work as compared to men. In addition, many women forgo or curtail employment because of family responsibilities. The removal of obstacles and inequalities faced by women is advantageous to an economy’s development. For example, the Beijing Declaration affirms a national commitment to the inalienable rights of women and girls and their empowerment and equal participation in all spheres of life including the economic domain.
Also, Goal 8, target 8.5 of the Sustainable Development Goals (SDG) is to achieve full and productive employment and decent work for all women and men (including for young people and persons with disabilities), as well as equal pay for work of equal value by 2030.
According to a report by the National Bureau of Statistics (NBS) the percentage of men employed in the State Civil Service from 2014 to 2015 was higher than the percentage of women for both senior and junior positions.
The average percentage of women employed in the State Civil Service from 2010 to 2015 in each category (junior and senior) was 38.16 per cent, while it was 68.84 per cent for men.
Also, men dominated employment in federal MDAs while women on grade level 01 –17 plus Special grade level was 34.67, 35.08 and 32.79 per cent for 2015, 2016 and 2017 respectively.
In the financial services sector, the Central Bank of Nigeria (CBN) had in 2014 directed that 40 per cent of banks’ top management and 30 per cent of board directors should be women.
Reports revealed that that women constitute only 22.3 per cent of the total board appointments in Nigerian banks, while their counterparts make up 77.7 per cent since 2014.
However, FBNHoldings, Nigeria’s leading financial holding company and parent company to FirstBank is no doubt exemplary at representing the change, thus demonstratively redefined the Women in Business trajectory with women occupying various leadership positions, positioning the financial group powerhouse as a leading institution at driving Gender Balance in the Boardroom.
Leading the pack of women in the board across the group structure which comprises FirstBank and its subsidiaries , FBNQuest is Ibukun Awosika whom has been Chairman of FirstBank since 2016. Prior to being the Chairman, she was a Non-Executive Director. since 2016 . The representation further cuts across the group entity of its parent company, FBNHoldings. Other companies across the group, FBNQuest and FBNInsurance are also not left out.
Otunba Debola Osibogun, Non-Executive Director, FBNHoldings; Cecilia Akintomide (OON), Independent Non-Executive Director, FBNHoldings; Oluwande Muoyo, Independent Non-Executive Director, FBNHoldings; Dr. Omobola Johnson, Non-Executive Director, FBNQuest Merchant Bank; Oyinkansade Adewale, Non-Executive/Independent Director, FBNQuest Merchant Bank.
Others are Kehinde Adenrele, Chairman, FBNInsurance, Folake Ani-Mumuney,Chairman, FBNInsurance Brokers; Ijeoma Agboti, Non-Executive Director, FBNQuest Capital; Funke Feyisitan Ladimeji, Non-Executive Director, FBNQuest Asset Management; Titi Adebiyi, Independent Director, FBN General Insurance and Margaret Dawes, Non-Executive Director, FBNInsurance.
With such an admirably notable representation, it is no surprise that only recently, Women Corporate Directors (WCD) – Nigerian Chapter – had FirstBank host its meeting, held on Thursday, 3 October 2019 with 60 female directors and leaders of various organisations across various industries in attendance. These women discussed pertinent corporate issues with a view to promote the continued influence of women in Business and the economy, also ensuring that the needed balance on the home front is bolstered. The keynote speaker is Osagie Okunbor, managing director SPDC & Country Chair, Shell Companies in Nigeria.”
FBNHoldings recognition of female impact in its business operations at management level no doubt sets the tone for other institutions across other industries to promote women inclusiveness in management, thereby instrumentally shaping gender balance in the business atmosphere, thus influencing ethical practices in a cultured way worthy of consistently reiterating the recognition of female at impacting the economy and National Income as a whole. This in no small measure transcends to the political space, the cornerstone of legislative impact in the economy and business activities as a whole.
Godwin Emefiele, governor of the CBN, said recently that the Apex bank had made remarkable progress in closing the gender gap in the Bank.
“It is heartening that today, women represent 29.0 per cent of CBN staff and 29.0 percent of directors are women. Eight departmental directors and one Director General of WAMZ as against 26.0 per cent of staff and 25.0 percent of directors in 2014. Similarly, three out of 11 board members are women (27 percent)”, Emefiele said at the 2019 CBN Commemoration of the International Women’s Day (IWD) in March, 2019.
Leading financial institution, Fidelity Bank Plc, has partnered with the Federal Ministry of Humanitarian Affairs and Poverty Alleviation to provide support to vulnerable households in Abuja through its Food Bank programme.
Launched in April 2023, the Fidelity Food Bank is one of the bank’s flagship Corporate Social Responsibility (CSR) initiatives. The programme seeks to combat hunger and malnutrition by supporting communities affected by food insecurity. Since its introduction, more than 300,000 food packs have been distributed to beneficiaries across Nigeria’s six geopolitical zones.
Speaking at an event held recently in Abuja to commemorate the 2026 International Day for the Eradication of Poverty, the Managing Director and Chief Executive Officer of Fidelity Bank Plc, Nneka Onyeali-Ikpe, represented by the bank’s Divisional Head of Public Sector, Richard Madiebo, said the bank’s interventions extended beyond food distribution to entrepreneurship support and other empowerment programmes designed to help individuals and families achieve economic independence.
According to Onyeali-Ikpe, Fidelity Bank’s commitment to community development spans approximately three decades, reflecting its longstanding dedication to improving the wellbeing of its host communities.
“Fidelity Bank has always aligned its CSR programmes with the needs of its host communities. We understand the importance of private sector participation in addressing poverty and promoting inclusive development.
“We have delivered 2,000 food packs to residents of Abuja. There are several other initiatives that the ministry and the bank are discussing, and we will allow the ministry to provide further details at the appropriate time,” she said.
Also speaking at the event, the Minister of Humanitarian Affairs and Poverty Reduction, Bernard M. Doro, commended Fidelity Bank for contributing to efforts to improve the welfare of vulnerable Nigerians. He also called for stronger collaboration between the government and the private sector to address multidimensional poverty.
According to Doro, with 63 per cent of Nigeria’s population living in multidimensional poverty, a significant proportion of citizens remains excluded from economic activity, limiting businesses’ access to potential customers and employees.
“When 63 per cent of the population lives in multidimensional poverty, a substantial number of people are excluded from economic participation. This also means that businesses are unable to reach a large segment of their potential customers.
“Our responsibility as a ministry is to unlock partnerships with the private sector. Such collaboration is critical to expanding economic opportunities and bringing more people into productive economic activities. We are pleased that Fidelity Bank is fully committed to this effort,” Doro stated.
The minister urged stakeholders to move beyond declarations and ensure that poverty reduction initiatives deliver measurable and sustainable improvements in the lives of vulnerable households.
Ranked among the best banks in Nigeria, Fidelity Bank Plc is a full-fledged Commercial Deposit Money Bank serving over 9.1 million customers through digital banking channels, its 255 business offices in Nigeria and United Kingdom subsidiary, FidBank UK Limited.
The Bank is a recipient of multiple local and international awards, including the 2024 Excellence in Digital Transformation & MSME Banking Award by BusinessDay Banks and Financial Institutions (BAFI) Awards; the 2024 Most Innovative Mobile Banking Application award for its Fidelity Mobile App by Global Business Outlook; and the 2024 Most Innovative Investment Banking Service Provider award by Global Brands Magazine. Additionally, the Bank was recognised as the Best Bank for SMEs in Nigeria by the Euromoney Awards for Excellence and as the Export Financing Bank of the Year by the BusinessDay Banks and Financial Institutions (BAFI) Awards.
LAGOS, NIGERIA – Fidelity Bank Plc has successfully redeemed its 5-Year US$400 million Senior Unsecured Notes at maturity, reaffirming its commitment to meeting its obligations to investors and reinforcing its track record in the international debt capital markets.
Issued on 28 October 2021, the 5-year Eurobond matured on 28 October 2026 and carried an annual coupon of 7.625 per cent, payable semi-annually. Fidelity Bank met all scheduled coupon payments throughout the life of the instrument and has now fulfilled its final repayment obligation in full, covering both principal and accrued interest.
The redemption was funded from internally generated liquidity as part of the Bank’s forward-looking liquidity management strategy. Through a dedicated sinking fund, Fidelity Bank progressively provided for the maturing obligation, enabling the Bank to meet its commitment while maintaining business-as-usual operations and compliance with applicable regulatory liquidity requirements.
Commenting on the development, the Managing Director and Chief Executive Officer of Fidelity Bank Plc, Dr/Mrs Nneka Onyeali-Ikpe, said the successful redemption reflected the Bank’s disciplined approach to financial management and its commitment to delivering on its obligations.
“This successful redemption demonstrates the strength of our franchise, the discipline of our balance sheet management and our commitment to honouring our obligations to investors and other stakeholders. We anticipated this maturity from the outset and planned accordingly, which reflects our commitment to responsible financial management,” Onyeali-Ikpe said.
The redemption further strengthens Fidelity Bank’s record in the international debt capital markets. The 2021 issuance marked the Bank’s third Eurobond transaction, following earlier issuances in 2013 and 2017, wherein the Bank raised $300 million and $400 million respectively. The 2021 offer attracted investor orders exceeding US$700 million, reflecting strong demand for the Bank’s international debt offering.
The successful Eurobond redemption follows the completion of Fidelity Bank’s recapitalisation programme ahead of the regulatory deadline. The Bank’s capital-raising efforts increased its eligible regulatory capital to approximately ₦533 billion, exceeding the ₦500 billion minimum capital requirement for banks with international authorisation.
The completion of these milestones underscores Fidelity Bank’s strong capital position, prudent liquidity management and disciplined approach to financial execution. It also reinforces the Bank’s capacity to meet its financial obligations while pursuing its strategic growth objectives across domestic and international markets.
…….GTBank customers can now pay with it and businesses on HabariPay’s Squad gateway can now accept it.
Guaranty Trust Holding Company Plc (“GTCO” or “the Group“) today announced that two of its subsidiaries are live with Google Pay on the day it launches in Nigeria. Customers of Guaranty Trust Bank Limited (“GTBank”) can add their GTBank debit cards to Google Wallet and pay with Google Pay online, in Nigeria and internationally. Businesses that use Squad, the payment gateway run by the Group’s payments subsidiary HabariPay, can now offer Google Pay to their customers at checkout.
The Group is therefore present at both ends of the same transaction: with the person paying and with the business being paid.
For GTBank customers, the change is simple. They add their GTBank debit card to Google Wallet once. After that, they choose Google Pay at checkout, pick the card and confirm, without typing a card number, expiry date or CVV again. Google Pay replaces the card number with a secure digital token, so the merchant does not receive the actual card details. The card can be used wherever Google Pay is accepted online, including for subscriptions, travel bookings, food delivery, bills and digital services.
For businesses on Squad, “Pay with Google Pay” now sits at the top of the Squad checkout, alongside card, bank transfer, USSD, bank payments and Squad’s buy-now-pay-later options. A customer with a card in Google Wallet selects Google Pay, chooses the card, confirms, and is returned to the merchant’s site once the payment is verified. Google Pay is switched on by default for every business on Squad, and a merchant can choose to turn it off. Merchants set up for international payments can accept Google Pay from customers anywhere in the world, which opens Nigerian businesses to buyers abroad, including the diaspora. Fewer fields mean fewer points at which a customer can abandon a purchase, which matters most to the small and growing businesses that make up much of Squad’s merchant base.
Commenting on the launch, the Group Chief Executive Officer of GTCO, Mr Segun Agbaje, said: “Most failed online payments are not refused, they are abandoned. Somewhere along the way the customer gives up, and the business never learns about the sale it lost. As a customer centric Financial Services Group, we are committed to ensuring that we continue to deliver payment solutions that make transacting safe and simple for our various customer Groups. With Google Pay, what matters to us is that we are ready on both sides from the first day: a GTBank customer can pay with it, and a business on Squad can accept it.”
He added: “This is what a group structure is for. Our Bank and our Payments Business were built to do different jobs, and today they meet at the same checkout. We will keep putting the full weight of the Group behind those small moments where people decide whether paying digitally is worth the effort. When it is, everyone in the transaction wins: the customer, the merchant and the wider economy that depends on both.”
The Managing Director of HabariPay, Mr Eduofon Japhet, said: “For a merchant, every extra field at checkout is a reason for a customer to leave. Squad businesses now get Google Pay inside the checkout they already use, so their customers can pay in a few taps with a card they have already saved. A merchant set up for international payments can now be paid with Google Pay by a customer anywhere in the world, with nothing new to integrate.”
Availability. GTBank customers can add an eligible GTBank debit card through the Google Wallet app on Android or through their Google Account. From today, Google Pay is on by default for all businesses on the Squad payment gateway, and merchants can choose to turn it off. Squad merchants set up for international payments can accept Google Pay from anywhere in the world. More information is available at www.gtbank.com and www.squadco.com.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title