brand
Breaking : CBN bows to pressure lifts ban on cement, 42 items and raises dollar supply

 The Central Bank of Nigeria has said it is raising dollar supply in the foreign exchange market, just as it also lifted the ban on 43 items that were previously not qualified for forex at the official market.
The decision came after the naira tumbled to 1,050/$ at the parallel market on Thursday, following pressure from international organisations and experts.
The CBN has finally succumbed to pressure and lifted the ban on the importers of 43 items restricted from accessing foreign exchange on its official platform.
It disclosed this in a statement titled, ‘CBN restates commitment to boost liquidity in forex market’, signed by the bank’s Director, Corporate Communications, Isa AbdulMumin, on Thursday.
“Importers of all the 43 items previously restricted by the 2015 circular referenced TED/FEM/FPC/GEN/01/010, and its addendums are now allowed to purchase foreign exchange in the Nigerian foreign exchange market,” the statement said.
The apex bank said it would continue to promote orderliness and professional conduct by all Nigerian foreign exchange market participants to ensure market forces determined exchange rates on a willing buyer – willing seller principle.
It added, “The CBN reiterates that the prevailing foreign exchange rates should be referenced from platforms such as the CBN website, FMDQ and other recognised or appointed trading systems to promote price discovery, transparency, and credibility in the FX rates.
“As part of its responsibility to ensure price stability, the CBN will boost liquidity in the Nigerian foreign exchange market by interventions from time to time. As market liquidity improves, these CBN interventions will gradually decrease.”
The statement said the CBN was committed to accelerating efforts to clear the FX backlog with existing participants and would continue dialogue with stakeholders to address the issue.
It stated, “The CBN has set as one of its goals the attainment of a single FX market. Consultation is ongoing with market participants to achieve this goal. Participants and the general public are to be guided by the above.”
Meanwhile, some Bureau de Change operators who spoke to The PUNCH on Thursday said the dollar traded between 1,025/$ and 1,050/$ in Lagos and Abuja.
A BDC operator in Lagos, Abguadi, said, “The dollar was bought at N1,025/$ and sold at N1,035/$ on Thursday.”
According to another BDC operator, Abdul, “We bought dollar for N1,015/$ and sold it at N1,035/$. The price has been rising.”
A BDC operator, Yusuf, said, “Some BDCs don’t even have access to the forex. Today, we bought the dollar and sold at 1,035/$ and 1,050/$.”
Another BDC operator in Abuja, Ibrahim Yahu, said as of the close of business on Thursday, they were buying at N1.030/$ and selling at 1,045/$.
A forex dealer identified simply as Suraju said, ‘’I buy at N1,030/$ and sell N1,035/$; It is just a difference of N5.’’
However, on the Investor & Exporter forex window, the naira appreciated slightly after closing at 759.20/$ from 766.41/$ on Wednesday.
But the new Governor of the Central Bank of Nigeria, Olayemi Cardoso, also says the new leadership team will review the CBN foreign exchange market policies, corporate governance practices, and monetary policies to reposition the apex bank to achieve its core mandates.
Already, he said the new team members, who resumed fully at the bank a few weeks ago following their confirmation by the National Assembly, were carrying out a comprehensive assessment of the challenges facing the central bank.
According to him, the ongoing assessment of the bank will lead to tweaking or jettisoning of some policies as part of a wide-ranging programme to reform the bank as a catalyst for economic growth and development.
This was contained in a document obtained by our correspondent on Thursday.
The document was titled, ‘Preliminary assessment of challenges facing the Central Bank of Nigeria.’
In the document, Cardoso outlined the challenges facing the CBN, introduced high-level proposals to address reformation challenges while examining the role of a refocused central bank in supporting the economic agenda of President Bola Tinubu.
In the paper, the new CBN governor raised several questions, ranging from how corporate governance failures in the CBN could be addressed, how public and financial systems’ stakeholder confidence could be restored in the autonomy and integrity of the CBN, as well as the need to refocus the central back to its core functions.
He also harped on what should be put in place to revert to evidence-based monetary policies, including the discontinuation of unorthodox monetary policies and foreign currency management, unorthodox use of Ways and Means spending, and developing control limits in the use of Ways and Means in financing public sector deficit.
On the backlog of FX demand, Cardoso emphasised the need for creative financing options for clearing the short to medium-term backlog.
The new central governor also plans to limit the CBN’s fiscal side interventions while proposing responses to addressing inflation and price stability issues.
Cardoso said, “These problem statements need in-depth review by the new Central Bank leadership team to determine what mechanisms are currently working, what can be tweaked or dispensed with and what new tools need to be introduced.”
On how the CBN can be refocused to support economic growth, he said, “The economic policy proposals of the administration identify a set of fiscal reforms and growth targets that will achieve $1.0tn GDP within eight years. In reviewing selected BRICS and MINT countries with large populations and similar developmental characteristics as Nigeria, it is interesting to identify macroeconomic indices that point to Nigeria’s economic trajectory, given the faithful implementation of the proposed economic reforms. In economies bigger than $1.0tn, these indicators include moderate inflation, sizable foreign reserves, and the capacity to rebound from a cyclical economic downturn quickly.”
He added, “Much has been made of past CBN forays into development financing, such that the lines between monetary policy and fiscal intervention have blurred. In refocusing the CBN to its core mandate, there is a need to pull the CBN back from direct development finance interventions into more limited advisory roles that support economic growth.”
He listed the advisory roles as the CBN acting as a catalyst in the propagation of specialised institutions and financial products that support emerging sectors of the economy, facilitating new regulatory frameworks to unlock dormant capital in land and property holdings, accelerating access to consumer credit and expand financial inclusion to the masses; de-risking instrumentation to increase private sector investment in housing, textiles and clothing, food supply chain, healthcare, and educational supplies; and exercising the CBN’s convening power to bring critical multilateral and international stakeholder participation in government and private sector initiatives.
In conclusion, Cardoso said, “It must be emphasised that CBN does not have a magic wand that can be waved at the current economic challenges. The problems facing the bank are large and complex. However, with focused leadership and sustained reforms, it is expected that over time, the country will see gains open economic spaces, attract new investments, create employment, and give our hardworking and talented compatriots an opportunity for a more prosperous future”.
Manufacturers back FG
Speaking exclusively with The PUNCH, the Director-General of the Manufacturers Association of Nigeria, Segun Ajayi-Kadir, commended the decision made by the CBN to lift the ban on imports of the blacklisted items.
According to him, about 200 association members have been adversely affected by the ban that Emefiele imposed.
He said, “We commend the CBN Governor for taking a very pragmatic and far-sighted decision on this matter. You will recall that when the last CBN governor imposed this list of items that are not valid for forex, the association indicated that it was not consulted, and that it was ill-advised. It was ill-advised in that the CBN did not correctly assess the relevance of those items.
“Some of those items represent raw materials that are not locally available, and when that was done, it put more than 200 of our members in jeopardy. It put their survival in jeopardy. Many of them suffered unprecedented low returns in their activities. We indicated that the affected operators needed to be consulted.”
Ajayi-Kadir, who warned that the apex bank had no business meddling in issues bordering on fiscal policy, demanded more reviews to be done to remove more bottlenecks that were imposed on manufacturers by the previous CBN leadership.”
Reacting, the President of the All Farmers Association of Nigeria, Kabir Ibrahim, said removing the forex ban on the items might not influence the seamless importation of food as countries were battling to achieve food sufficiency.
In a telephone interview, the president noted that the festive period would prove effective if the new policy is appropriate or not.
He said, “It is premature to say what will happen as this liberalisation does not mean seamless importation of goods and services as the entire global food system is going through challenges.
“There is no magic wand to stave off the current food inflation rate in Nigeria and it is pretty unwise to purchase grains. For instance, it will be at cross-purposes with any food pricing protocol.
“We should tarry awhile before making definite forecasts as to what will happen between now and Christmas.”
Speaking with The PUNCH, the Chief Executive Officer of the Centre for Promotion of Private Enterprise, Dr Muda Yusuf, said it was a welcome decision of the CBN to discontinue the forex exclusion policy on the 43 items. It is a move in the right direction. It is part of the policy normalisation process.
Yusuf said, “The exclusion of the 43 items was one of the drivers of distortions in the forex market. The exclusion of the items also contributed to the persistent divergence in rates between the official window and the parallel market.
“The exclusion also conflicted with extant trade policy as the items were not under import prohibition in the first place. It was an example of lack of policy coordination under the previous administration.”
Yusuf further stated that the new directive would improve transparency and disclosures in foreign exchange transactions.
Meanwhile, he noted that the CBN should avoid market suppression tendencies, especially outside the I&E window.
He stressed that all policy impediments to forex inflows should be removed.
He stated, “The fiscal authorities should continually monitor the economic landscape to shape the character of fiscal policy measures to regulate imports in line with comparative advantage principles.”
Meanwhile, he added, “We need to worry about the risk of an import surge and also need to upscale the use of fiscal policy measures to boost domestic production and productivity.”
The President, Association of Bureaux De Change Operators of Nigeria, Dr Aminu Gwadabe, said generally, it was a booster aimed at boosting confidence and eliminating uncertainties in the market.
He said, “It entails reforms, compliance with official market rates and liquidity interventions. We at ABCON will continue to partner with the apex bank in achieving its set goals.
“The unbanning of the 43 items will deepen the market and stimulate bilateral trade and inward-looking industrialisation strategies.”
He added, “My call to the CBN is to ensure speedy implementations of the policies. To enhance the buffers, the CBN should pursue a paradigm shift from demand to supply measures to boost the needed liquidity in the market.”
Gwadabe said the CBN should emphasise intervention in the retail end sector where the spikes were most pervasive through the effective pass-through of the BDCs to close the gaps between the official and unofficial exchange rates.
brand
FIDELITY BANK ANNOUNCES STANLEY CHIEDOZIEM AMUCHIE AS MANAGING DIRECTOR/CHIEF EXECUTIVE OFFICER
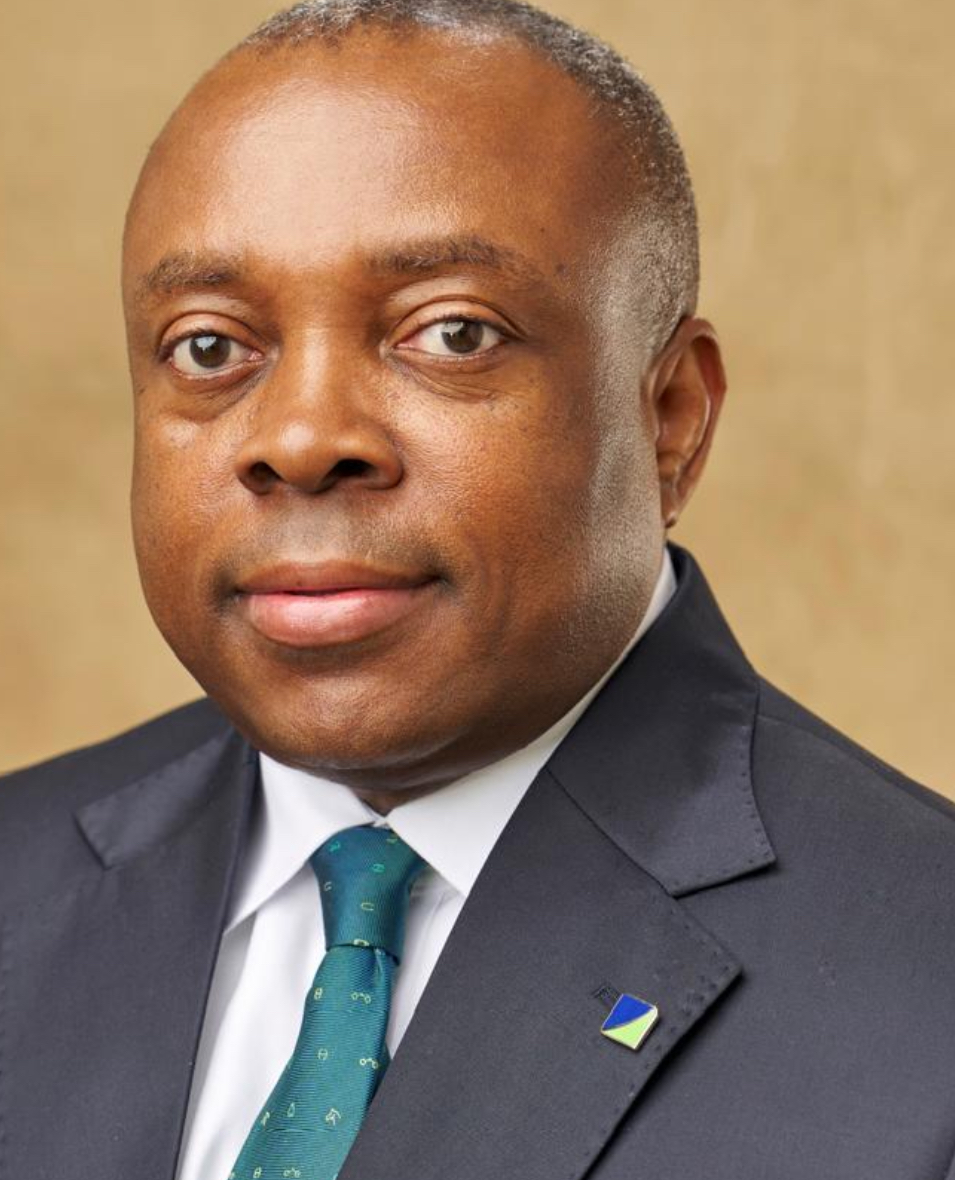
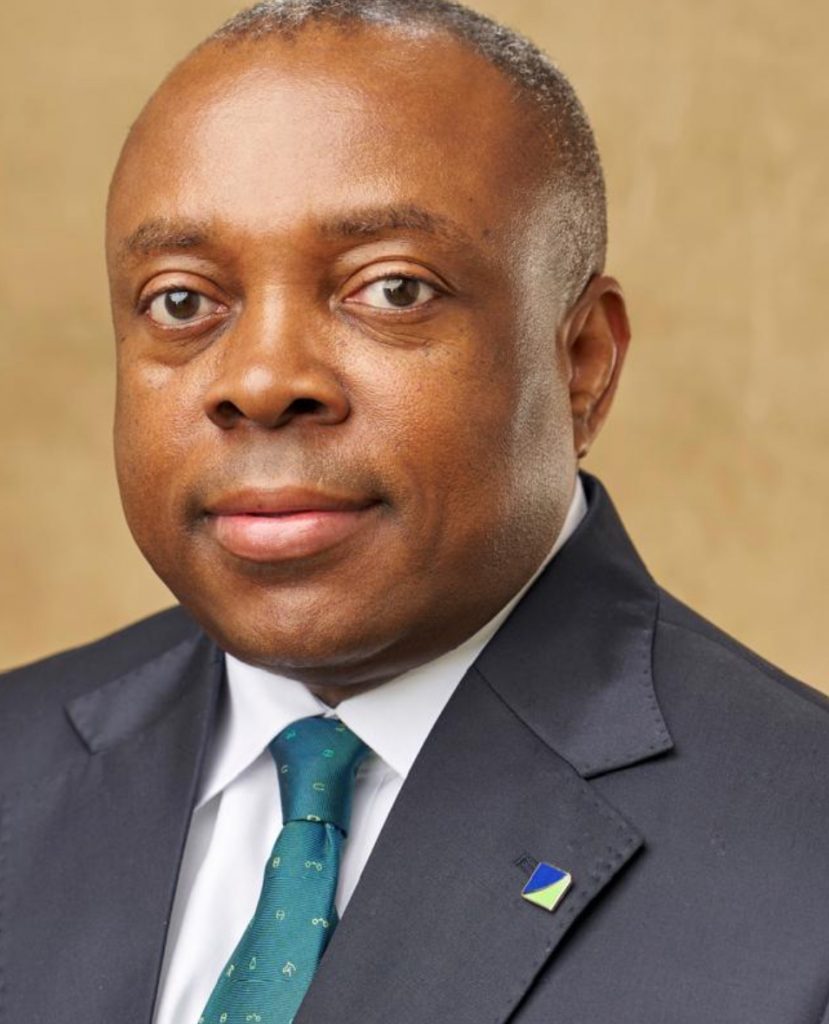
Fidelity Bank Plc is pleased to announce the confirmation of Mr. Stanley Chiedoziem Amuchie as its substantive Managing Director / Chief Executive Officer, following approval by the Central Bank of Nigeria (CBN) with effect from January 1, 2027.
Amuchie, who is currently an Executive Director and the Chief Operations and Information Officer of the tier-one lender, will succeed Nneka Onyeali-Ikpe, whose tenure as Managing Director and Chief Executive Officer ends on December 31, 2026.
Commenting on the appointment, the Chairman of the Board of Directors, Mrs. Amaka Onwughalu, said:
“We are delighted to confirm Stanley Amuchie as the substantive Managing Director / Chief Executive Officer of Fidelity Bank. His appointment reflects the Board’s confidence in his leadership capabilities, strategic insight, extensive industry experience and deep understanding of the Bank’s business. We are confident that he will provide the leadership required to consolidate our achievements and drive the Bank’s next phase of growth.
On behalf of the Board, I would also like to express our profound appreciation to the outgoing Managing Director / Chief Executive Officer, Dr. Nneka Onyeali-Ikpe, for her exemplary leadership, outstanding service and immense contributions to the growth and transformation of Fidelity Bank. Her tenure has been marked by strategic vision, bold leadership and a steadfast commitment to building a stronger, more competitive and resilient institution. Under her stewardship, the Bank recorded significant milestones, strengthened its market position and expanded its strategic reach. We are deeply grateful for her dedication and the enduring legacy she leaves behind.
As we begin this new chapter, we look forward to building on the strong foundation established under her leadership. The Board is fully committed to supporting Stanley as he leads the Bank towards greater innovation, operational excellence, sustainable growth and enhanced value creation for our customers, shareholders, employees and other stakeholders.”
Mr. Amuchie brings over 30 years of extensive experience in the financial services industry, with a distinguished track record of leadership, strategic execution, financial management and institutional transformation.
Prior to his confirmation, he served as Executive Director, Operations and Information Technology at Fidelity Bank, a position he assumed in January 2022. In this capacity, he played a significant role in strengthening the Bank’s operational capabilities, driving technology-led transformation and supporting its strategic growth ambitions.
Before joining Fidelity Bank, Mr. Amuchie had an accomplished career at Zenith Bank Plc, where he served in several senior leadership capacities, including Group Chief Financial Officer, reflecting his professional competence, leadership capabilities and contributions to the institution’s growth.
His professional accomplishments include playing a key role in Fidelity Bank’s acquisition of Union Bank UK, now FidBank UK, and contributing to the Bank’s successful $400 million Eurobond refinancing. His experience also spans capital raising, treasury management, financial strategy and international business expansion.
Mr. Amuchie holds a First Class degree in Industrial Chemistry and a Master’s degree in Corporate Governance. He is also a Fellow of the Institute of Chartered Accountants of Nigeria (ICAN) and an Honorary Senior Member of the Chartered Institute of Bankers of Nigeria (CIBN). He is currently pursuing a PhD in Management of Technology and Innovation.
His confirmation comes at an important stage in Fidelity Bank’s growth journey, as the institution continues to strengthen its market position, deepen customer relationships, accelerate digital transformation and expand its footprint in local and international markets.
The Bank is confident that Mr. Amuchie’s wealth of experience, strategic insight and deep understanding of its operations will provide strong leadership as Fidelity Bank advances its ambition of delivering sustainable growth and exceptional value to its stakeholders.
brand
ZENITH BANK USHERS IN YULETIDE SEASON WITH DAZZLING CHRISTMAS LIGHT-UP, MARKS 20 YEARS OF FESTIVE TRADITION
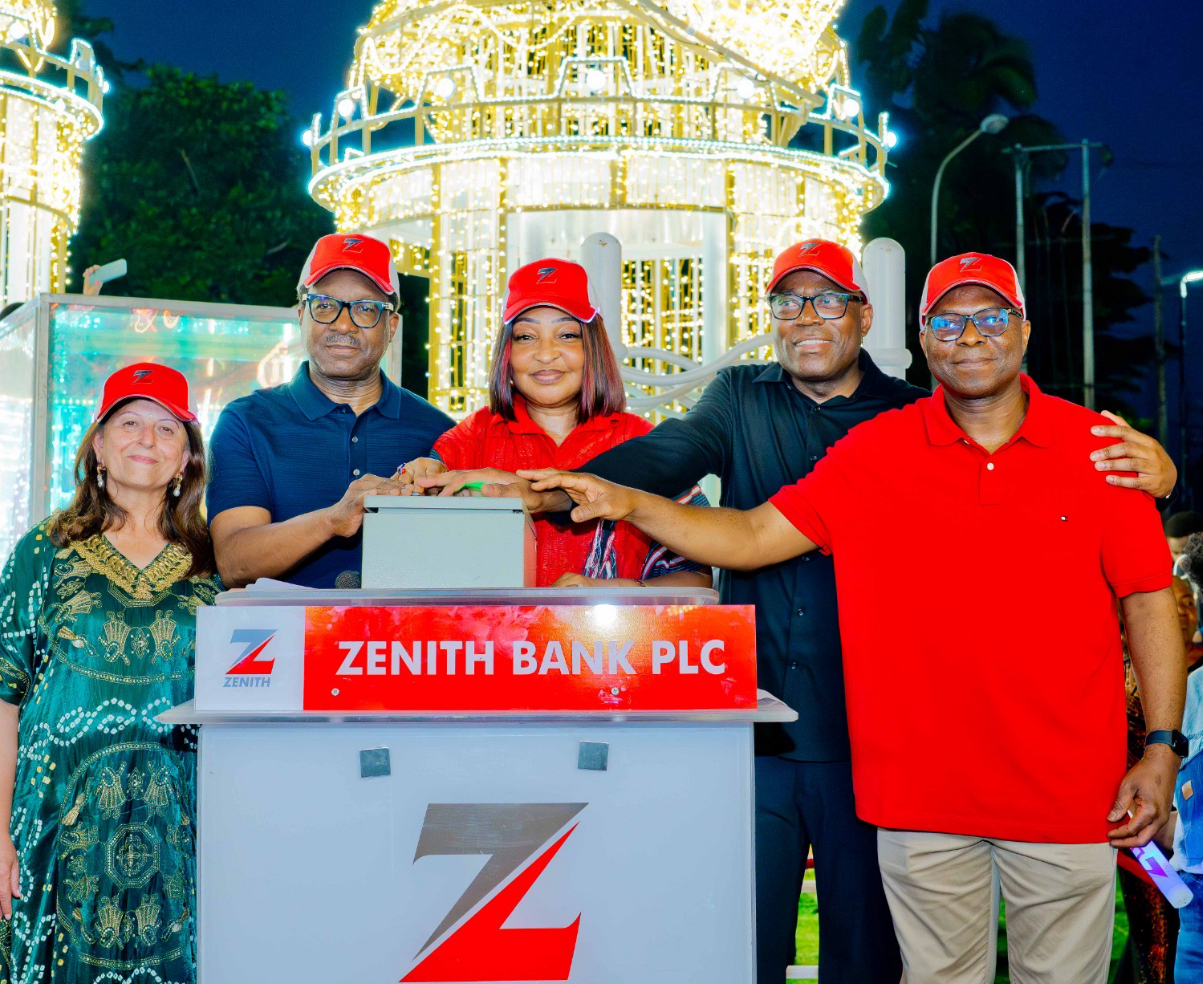
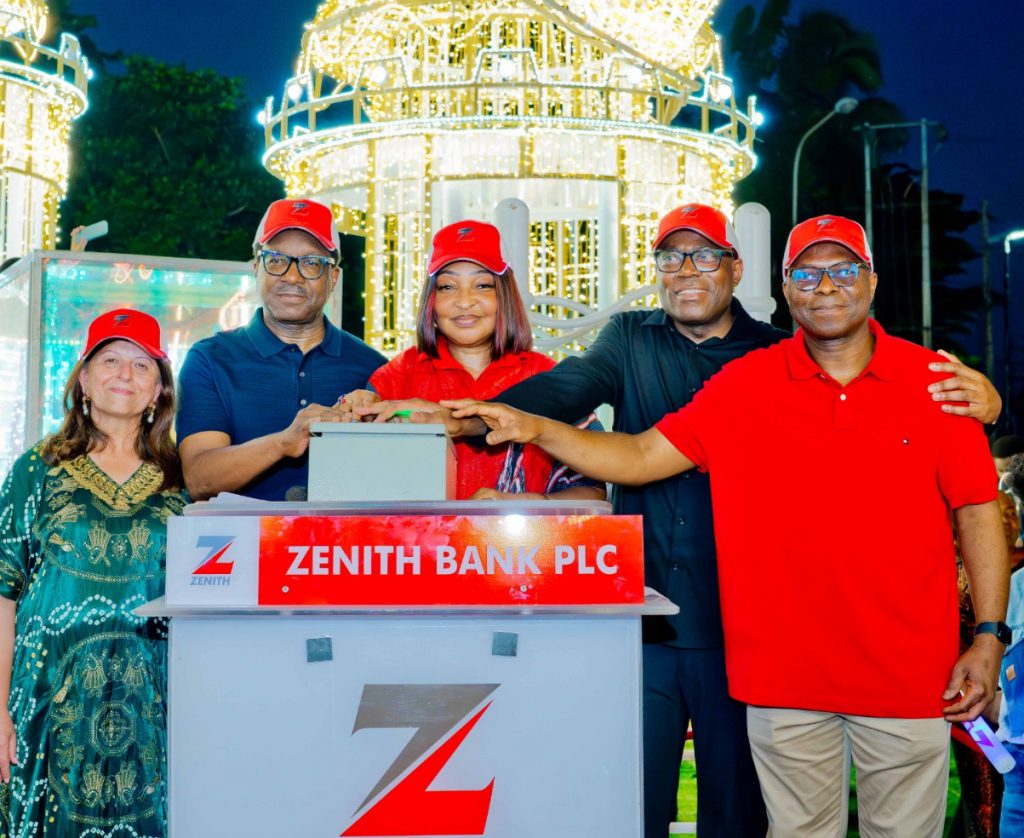
Zenith Bank Plc has once again transformed Ajose AdeogunStreet and Roundabout, home to its corporate headquarters in Victoria Island, Lagos, into a breathtaking spectacle of dazzling lights and festive splendour, marking the 20th anniversary of its iconic Christmas Light-Up tradition. The ceremony, held on Sunday, November 15, 2026, continued a cherished annual celebration that signals the beginning of the Yuletide season in Lagos.
Over the past two decades, the Christmas Light-Up has evolved into one of Lagos’ most anticipated festive attractions, drawing families, residents and visitors from across Nigeria and beyond, while reinforcing Zenith Bank’s enduring commitment to fostering community engagement and creating memorable experiences.
This year’s decorations feature captivating images of angels playing harps and trumpets, symbolising peace, hope, goodwill, harmony and the proclamation of good news. The elaborate installations reflect the spirit of Christmas and its enduring message of love, kindness and unity.
Speaking at the ceremony on behalf of the Group Managing Director/CEO of Zenith Bank Plc, Dame Dr. Adaora Umeoji, OON, Executive Director Adobi Nwapa reflected on the significance of the milestone, stating:
“This year’s ceremony is particularly special as we celebrate 20 years of this remarkable tradition. Two decades, ladies and gentlemen! That is 20 years of consistently bringing joy to the faces of Nigerians and sharing in the warmth, love and magic of Christmas.”
She further emphasised the Bank’s commitment to positively impacting its host communities, stating:
“At Zenith Bank, we believe that our responsibility extends beyond banking to making a meaningful difference in the lives of people and the communities we serve. This annual Light-Up reflects that dedication by bringing people together, creating lasting memories and spreading the joy of the festive season.”
Nwapa also conveyed warm greetings from the Bank’s Founder, Dr. Jim Ovia, CFR, and the Board, Management and Staff of Zenith Bank Plc. She expressed appreciation to the Lagos State Government, particularly His Excellency, Governor Babajide Sanwo-Olu, for its continued support of the annual celebration. Special recognition was accorded to Mrs. Kay Ovia, whose vision inspired the Christmas Light-Up, and Quantum Markets, the Bank’s longstanding partner, for its creativity and dedication to delivering spectacular decorations over the years.
The evening featured captivating performances by the Zenith Bank Choir and Nigerian music star Khaid, whose spirited performance added excitement and colour to the celebration. The event culminated in the ceremonial illumination of Ajose Adeogun Street, as an enthusiastic countdown spelling out “ZENITH” brought the Christmas lights to life.
The dazzling display, which has become a prominent feature of Lagos’ festive landscape, is expected to attract thousands of visitors from within the state and beyond throughout the Christmas and New Year celebrations, offering families and tourists an enchanting setting to enjoy the season and create lasting memories.
The Christmas Light-Up forms part of Zenith Bank’s longstanding commitment to corporate social responsibility, which remains integral to its operations and corporate philosophy. Through sustained investments in education, healthcare, infrastructure development, environmental sustainability and other community-focused initiatives, the Bank continues to demonstrate its dedication to improving lives, empowering communities and contributing meaningfully to Nigeria’s socioeconomic development.
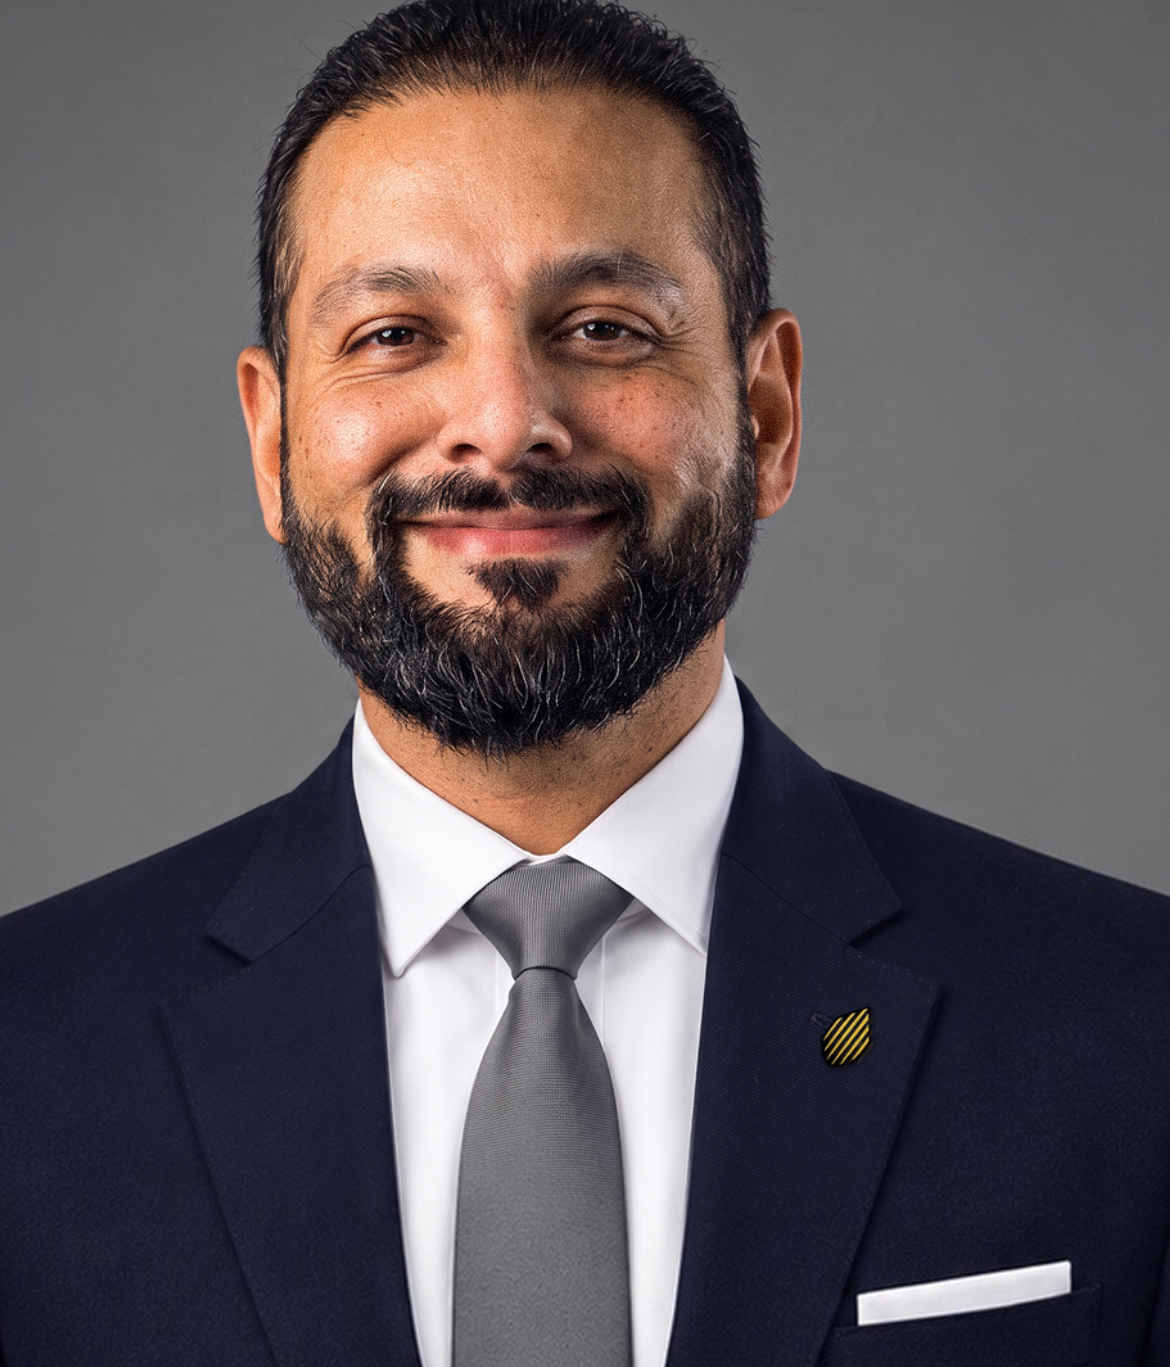
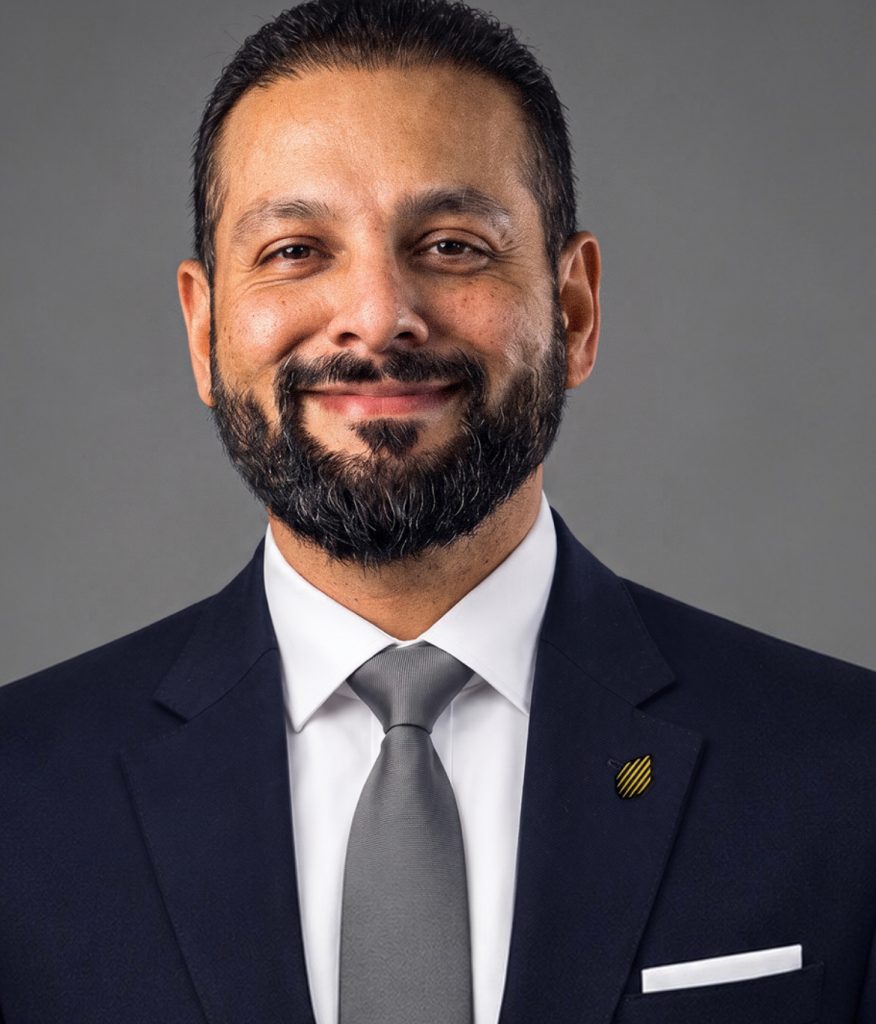 The Alternative Bank Limited (Alt Bank) has announced the appointment of Gul Khan as Managing Director and Chief Executive Officer following approval by the Central Bank of Nigeria (CBN). He succeeds Hassan Yusuf, the Bank’s founding Managing Director.
Khan brings more than 25 years of international financial services experience, having worked in Europe, America, Asia, Middle East & Africa. Most recently he served as Chief Executive Officer and Board Director of I&M Bank Kenya and was Group Head of Products for Airtel Money, the fintech business across 14 markets in Africa. He alsopreviously served as Global Head of Retail Banking and Wealth Management at HSBC Amanah, the Group’s non-interest banking business. His career also includes executive leadership roles with banks in UAE, Egypt and Qatar giving him experience across established banking institutions and technology-led financial services businesses.
Commenting on the appointment, Muhtar Bakare, Chairman of Alternative Bank, said “Gul’s expertise in non-interest banking and his leadership experience across African financial services position him well to lead Alternative Bank through its next phase of growth. The Board is confident in his ability to build on the Bank’s foundations and broaden its reach, while maintaining the strong governance and commercial discipline essential to long-term success.”
Khan will work with the Board and management team to guide the Bank’s next phase of growth. Outlining his priorities, he said:
“The opportunity is to make Alt Bank the preferred choice for consumers and businesses in Nigeria. That means understanding what customers need, whether acquiring productive assets or growing their businesses, and providing solutions that are relevant and they can use with ease. I look forward to working with colleagues to build on Alt Bank’s progress and earn our customers’ continued trust.”
Alt Bank met the CBN’s revised minimum capital requirement for national non-interest banks well ahead of the regulatory deadline. The Bank has also completed its migration to MIZAN, a core banking platform designed for non-interest financial institutions. Its strengthened capital base and investment in technology support its capacity to finance business growth and develop products that meet the needs of its customers.
The Alternative Bank is part of Sterling Financial Holdings Company Plc, a diversified Nigerian financial services group. Backed by the Group’s institutional strength, governance framework and commitment to innovation, the Bank continues to advance its mission of expanding access to non-interest financial solutions for individuals and businesses across Nigeria.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19