brand
Nigeria gets W’Bank $1.5bn for subsidy removal and an introduction of comprehensive tax policies

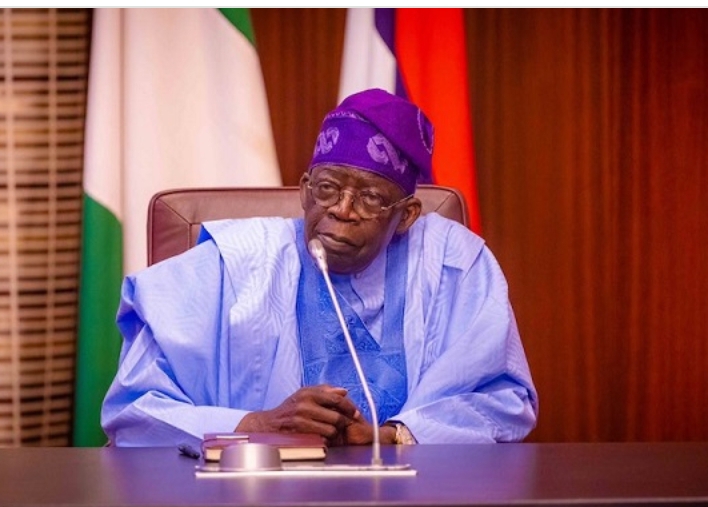
The World Bank has fully disbursed a $1.5bn loan to Nigeria following the Federal Government’s implementation of key reforms, including removing fuel subsidies and introducing comprehensive tax policies.
The loan, part of the Reforms for Economic Stabilisation to Enable Transformation Development Policy Financing initiative, is among the fastest disbursements Nigeria has received with both tranches released in less than six months.
According to a World Bank document obtained by our correspondence , the loan was approved on June 13, 2024, with the first tranche of $750m disbursed on July 2, 2024.
The second tranche, tied to the fulfilment of specific economic reform conditions, was disbursed in November 2024.
This rapid disbursement contrasts with other loan programmes, which typically experience delays due to slow or partial implementation of conditions.
For more context, another loan of $750m was approved on the same day (June 13, 2024) for the Accelerating Resource Mobilisation Reforms Programme for Results project in Nigeria.
The World Bank has only disbursed about $1.88m to Nigeria at the time of filing this story, which is less than one per cent of the total approved $750m for the ARMOR project.
Our correspondence further observed that the $1.5bn loan disbursed to Nigeria was structured in two tranches with different maturity periods.
The first tranche was a $750m credit from the International Development Association, featuring a 12-year maturity and a six-year grace period.
The second tranche, a $750m loan from the International Bank for Reconstruction and Development, has a 24-year repayment period with an 11-year grace period.
The World Bank document read, “This document summarises the progress made under the Reforms for Economic Stabilisation to Enable Transformation Development Policy Financing for the Federal Republic of Nigeria (Borrower or Recipient), which was approved by the Executive Directors on June 13, 2024.
“The DPF is a standalone operation comprised of two tranches: (1) first tranche comprising $750m credit from the International Development Association (Association) (Shorter Maturity Loan terms with 12-year maturity and grace period of 6 years, Credit No. 7567-NG); and (2) second tranche comprising $750m loan from the International Bank for Reconstruction and Development (Bank) (US dollar-denominated, commitment-linked loan with 24-year maturity and grace period of 11 years, Loan No.9683-NG).
“The Financing Agreement and Loan Agreement were signed and declared effective on June 19, 2024 and June 26, 2024, respectively. The first tranche was released on July 2, 2024.”
While the document itself did not clearly state when the disbursement for the second tranche was made, further findings by The PUNCH showed that Nigeria got a $750m disbursement from the World Bank in November.
According to the document seen by The PUNCH, a critical reform that unlocked the second tranche was the removal of fuel subsidies.
The World Bank commended the government for not only meeting the condition but exceeding expectations by fully deregulating the fuel market.
The document noted, “In terms of implementation, while the TRC [Tranche Release Conditions] formulation required introducing the change over a specified time-bound implementation period, the Borrower has moved ahead and made the change immediately, thereby overachieving the TRC in this respect.
“Effective October 2024, the price of PMS has been determined by the international market and the exchange rate set by the Central Bank of Nigeria.”
This move has allowed petrol prices to align with international market rates and exchange rates, effectively ending the implicit subsidies that had burdened public finances.
Fuel prices have increased more than fivefold since the reform process began in mid-2023, a change that has drawn both praise for its fiscal prudence and criticism for its impact on living costs.
In addition to removing fuel subsidies, the Federal Government introduced sweeping tax reforms aimed at improving revenue mobilisation.
The Nigeria Tax Bill 2024, submitted to the National Assembly, proposes a gradual increase in the Value Added Tax rate to 10 per cent by 2025, alongside measures to simplify tax compliance and expand input tax credits for businesses.
The document read, “The Borrower has successfully carried out the programme as outlined in the Letter of Development Policy, with progress along all areas supported by the DPF. Following the implementation of the reforms that constituted prior actions for the first tranche of the RESET DPF (disbursed on June 28, 2024), the Borrower continues to carry out the program as planned.
“The borrower has prepared and submitted to the National Assembly on October 3, 2024, a comprehensive package of tax reforms, which not only reform the VAT regime but also simplify tax policy laws and tax administration.
“Reforms have also been implemented to fully deregulate the fuel market, ensuring that retail prices are determined by market conditions and opening the sector to competition. The authorities are following through on their commitment to cease deficit monetization, relying instead on standard debt instruments to finance the deficit.”
There were three key conditions noted in the document, with the first being increasing net oil revenues.
For the first condition, the World Bank noted that there was a Presidential Executive Order that mandated that all fiscal transfers, including crude oil sales and gasoline imports, be executed at the prevailing market exchange rate, with Naira-based transactions starting in October 2024, effectively addressing implicit subsidies.
The second condition was to increase non-oil revenue, and in this regard, the government submitted a draft bill to the National Assembly proposing a VAT rate increase to 10 per cent in 2025, while also allowing input tax credits for capital and services.
The third condition is to ensure social protection delivery was strengthened, and the document noted the submission of an amendment bill mandating the use of the National Social Registry as the primary targeting tool for social investment programs.
The World Bank described the reforms as necessary for diversifying Nigeria’s revenue sources, given the country’s historically low tax-to-GDP ratio.
However, the tax bills have sparked controversy, with northern leaders arguing that the reforms could widen economic disparities between the north and the south.
The disbursement of the $1.5bn loan comes amidst widespread public dissent over the effects of the reforms.
The removal of fuel subsidies has led to soaring petrol prices, significantly increasing transportation and living costs.
Protests erupted in cities like Abuja, Kano, and Lagos, with citizens expressing frustration over rising economic hardships.
President Bola Tinubu and members of his cabinet defended the reforms, describing them as essential for Nigeria’s economic stability and growth.
Tinubu emphasised that the funds saved from the removal of subsidies would be redirected toward infrastructure development, social welfare, and economic diversification.
To mitigate the immediate impact of the reforms, the government has introduced relief measures, including direct cash transfers of N25,000 to 15 million vulnerable households.
However, only about four million households have benefited from this cash transfer programme, which is far below the target.
Also, efforts are underway to promote compressed natural gas as a cheaper alternative to petrol, with a target of converting over one million vehicles in three years to reduce transportation costs.
The World Bank praised the government’s swift and decisive actions, noting that Nigeria’s ability to meet the conditions for both tranches in record time reflects a strong commitment to economic transformation.
The global lender also acknowledged the government’s efforts in addressing structural inefficiencies, such as the high fiscal burden from subsidies and the challenges of revenue mobilisation, calling for sustained reforms.
Amid concerns over rising external debt and the debt service burden, the Federal Government, under the leadership of President Bola Tinubu, has secured loans worth $6.95bn from the World Bank in about 18 months.
The World Bank will decide on three major loan projects for Nigeria in 2025, totalling $1.65bn, as part of efforts to address critical developmental challenges in the country.
The loans, currently in the pipeline, will focus on internally displaced persons, education, and nutrition enhancement.
According to data from the external debt report released by the Debt Management Office, the World Bank’s share of Nigeria’s debt totals $16.32bn, with the majority owed to the International Development Association, which accounts for $16.32bn, which represents 38 per cent of Nigeria’s total external debt.
The International Bank for Reconstruction and Development, another arm of the World Bank, is owed $484.0m, or 1.13 per cent.
brand
FIDELITY BANK ANNOUNCES STANLEY CHIEDOZIEM AMUCHIE AS MANAGING DIRECTOR/CHIEF EXECUTIVE OFFICER
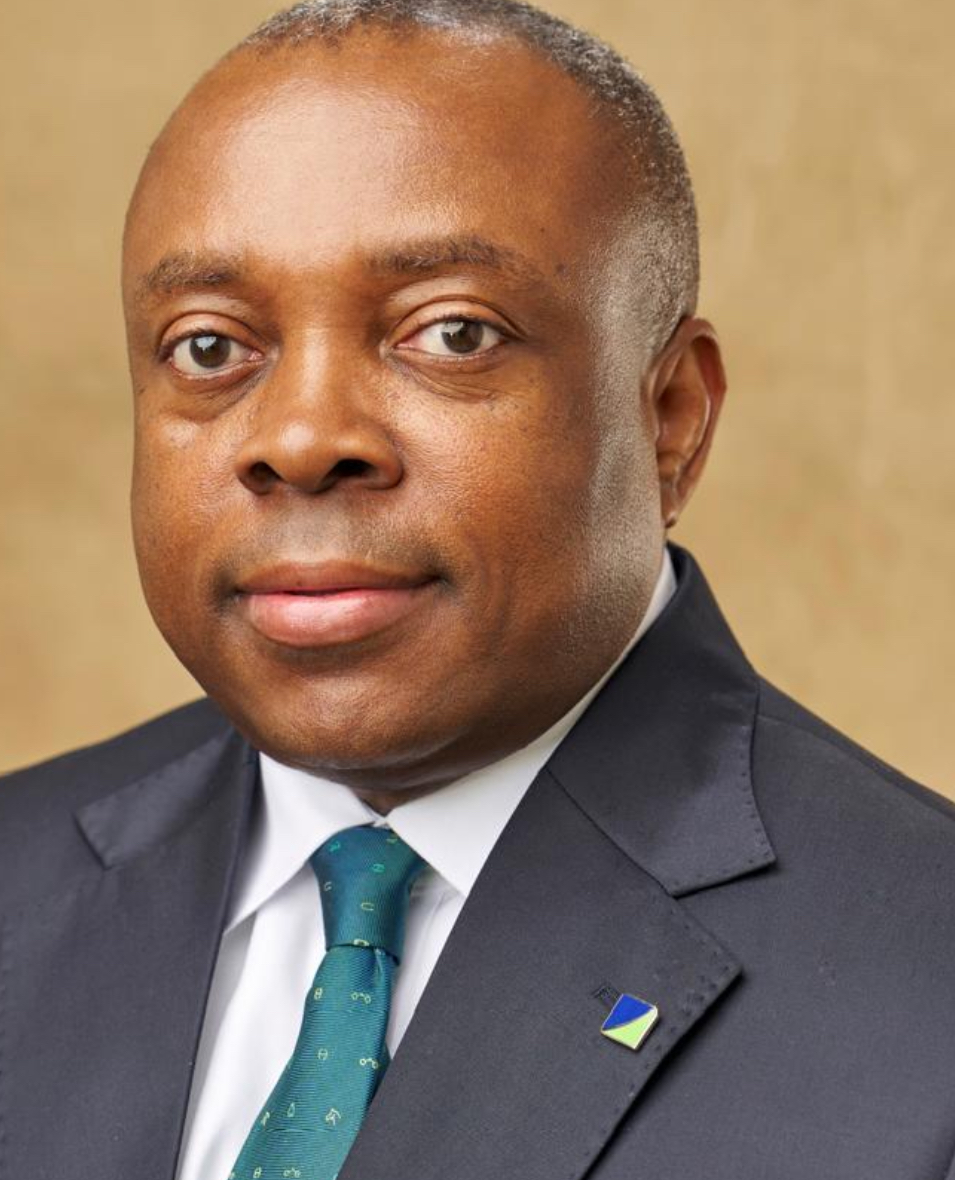
Fidelity Bank Plc is pleased to announce the confirmation of Mr. Stanley Chiedoziem Amuchie as its substantive Managing Director / Chief Executive Officer, following approval by the Central Bank of Nigeria (CBN) with effect from January 1, 2027.
Amuchie, who is currently an Executive Director and the Chief Operations and Information Officer of the tier-one lender, will succeed Nneka Onyeali-Ikpe, whose tenure as Managing Director and Chief Executive Officer ends on December 31, 2026.
Commenting on the appointment, the Chairman of the Board of Directors, Mrs. Amaka Onwughalu, said:
“We are delighted to confirm Stanley Amuchie as the substantive Managing Director / Chief Executive Officer of Fidelity Bank. His appointment reflects the Board’s confidence in his leadership capabilities, strategic insight, extensive industry experience and deep understanding of the Bank’s business. We are confident that he will provide the leadership required to consolidate our achievements and drive the Bank’s next phase of growth.
On behalf of the Board, I would also like to express our profound appreciation to the outgoing Managing Director / Chief Executive Officer, Dr. Nneka Onyeali-Ikpe, for her exemplary leadership, outstanding service and immense contributions to the growth and transformation of Fidelity Bank. Her tenure has been marked by strategic vision, bold leadership and a steadfast commitment to building a stronger, more competitive and resilient institution. Under her stewardship, the Bank recorded significant milestones, strengthened its market position and expanded its strategic reach. We are deeply grateful for her dedication and the enduring legacy she leaves behind.
As we begin this new chapter, we look forward to building on the strong foundation established under her leadership. The Board is fully committed to supporting Stanley as he leads the Bank towards greater innovation, operational excellence, sustainable growth and enhanced value creation for our customers, shareholders, employees and other stakeholders.”
Mr. Amuchie brings over 30 years of extensive experience in the financial services industry, with a distinguished track record of leadership, strategic execution, financial management and institutional transformation.
Prior to his confirmation, he served as Executive Director, Operations and Information Technology at Fidelity Bank, a position he assumed in January 2022. In this capacity, he played a significant role in strengthening the Bank’s operational capabilities, driving technology-led transformation and supporting its strategic growth ambitions.
Before joining Fidelity Bank, Mr. Amuchie had an accomplished career at Zenith Bank Plc, where he served in several senior leadership capacities, including Group Chief Financial Officer, reflecting his professional competence, leadership capabilities and contributions to the institution’s growth.
His professional accomplishments include playing a key role in Fidelity Bank’s acquisition of Union Bank UK, now FidBank UK, and contributing to the Bank’s successful $400 million Eurobond refinancing. His experience also spans capital raising, treasury management, financial strategy and international business expansion.
Mr. Amuchie holds a First Class degree in Industrial Chemistry and a Master’s degree in Corporate Governance. He is also a Fellow of the Institute of Chartered Accountants of Nigeria (ICAN) and an Honorary Senior Member of the Chartered Institute of Bankers of Nigeria (CIBN). He is currently pursuing a PhD in Management of Technology and Innovation.
His confirmation comes at an important stage in Fidelity Bank’s growth journey, as the institution continues to strengthen its market position, deepen customer relationships, accelerate digital transformation and expand its footprint in local and international markets.
The Bank is confident that Mr. Amuchie’s wealth of experience, strategic insight and deep understanding of its operations will provide strong leadership as Fidelity Bank advances its ambition of delivering sustainable growth and exceptional value to its stakeholders.
brand
ZENITH BANK USHERS IN YULETIDE SEASON WITH DAZZLING CHRISTMAS LIGHT-UP, MARKS 20 YEARS OF FESTIVE TRADITION
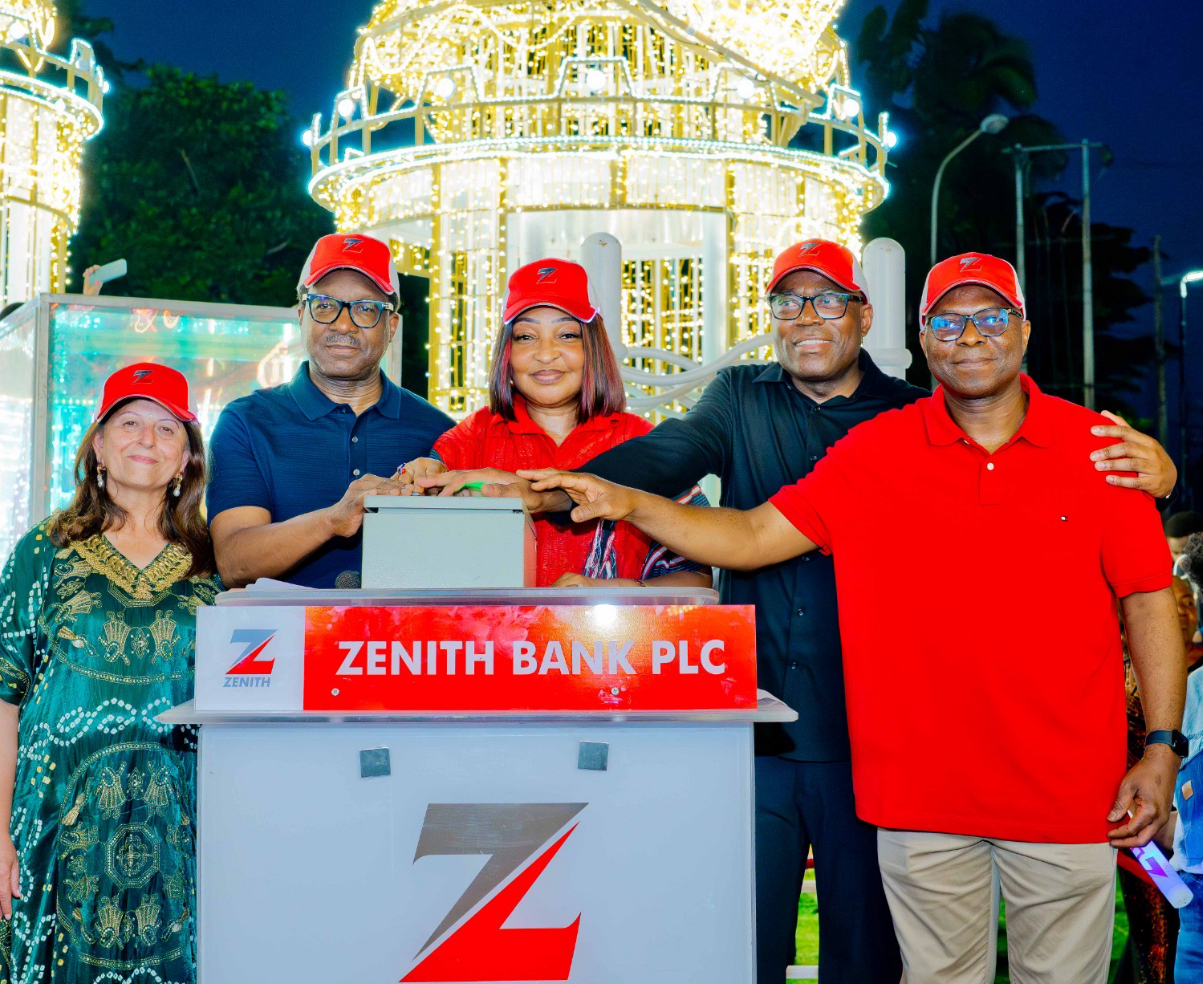
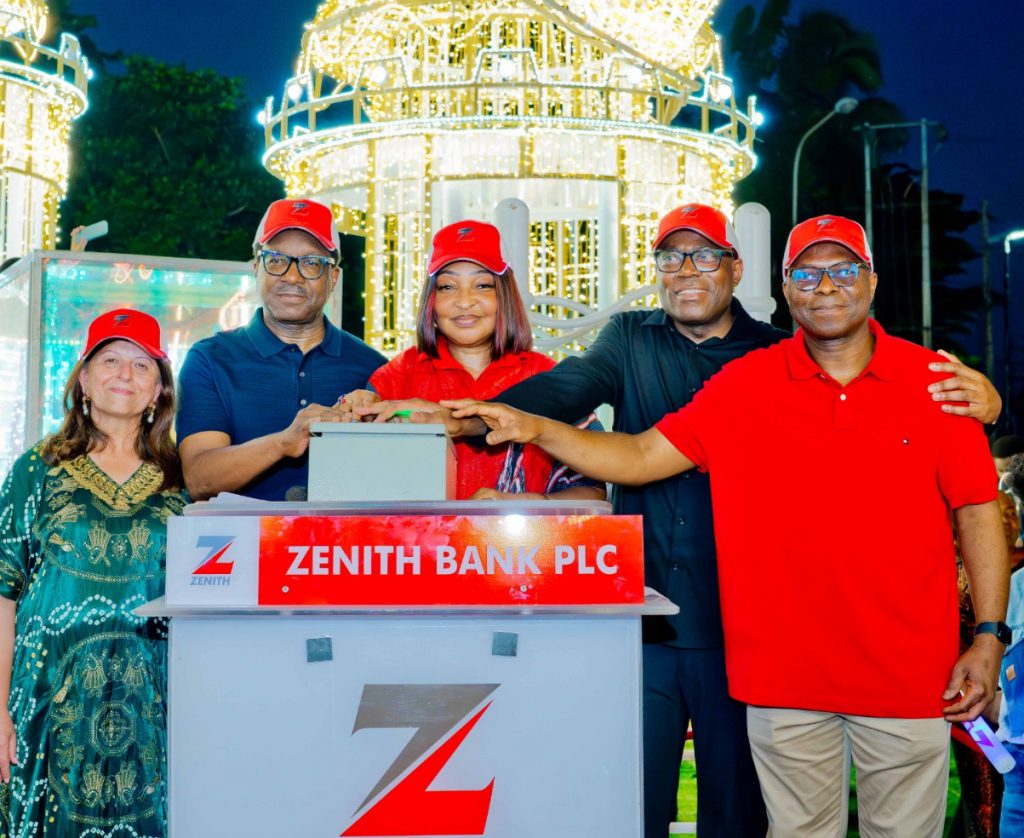
Zenith Bank Plc has once again transformed Ajose AdeogunStreet and Roundabout, home to its corporate headquarters in Victoria Island, Lagos, into a breathtaking spectacle of dazzling lights and festive splendour, marking the 20th anniversary of its iconic Christmas Light-Up tradition. The ceremony, held on Sunday, November 15, 2026, continued a cherished annual celebration that signals the beginning of the Yuletide season in Lagos.
Over the past two decades, the Christmas Light-Up has evolved into one of Lagos’ most anticipated festive attractions, drawing families, residents and visitors from across Nigeria and beyond, while reinforcing Zenith Bank’s enduring commitment to fostering community engagement and creating memorable experiences.
This year’s decorations feature captivating images of angels playing harps and trumpets, symbolising peace, hope, goodwill, harmony and the proclamation of good news. The elaborate installations reflect the spirit of Christmas and its enduring message of love, kindness and unity.
Speaking at the ceremony on behalf of the Group Managing Director/CEO of Zenith Bank Plc, Dame Dr. Adaora Umeoji, OON, Executive Director Adobi Nwapa reflected on the significance of the milestone, stating:
“This year’s ceremony is particularly special as we celebrate 20 years of this remarkable tradition. Two decades, ladies and gentlemen! That is 20 years of consistently bringing joy to the faces of Nigerians and sharing in the warmth, love and magic of Christmas.”
She further emphasised the Bank’s commitment to positively impacting its host communities, stating:
“At Zenith Bank, we believe that our responsibility extends beyond banking to making a meaningful difference in the lives of people and the communities we serve. This annual Light-Up reflects that dedication by bringing people together, creating lasting memories and spreading the joy of the festive season.”
Nwapa also conveyed warm greetings from the Bank’s Founder, Dr. Jim Ovia, CFR, and the Board, Management and Staff of Zenith Bank Plc. She expressed appreciation to the Lagos State Government, particularly His Excellency, Governor Babajide Sanwo-Olu, for its continued support of the annual celebration. Special recognition was accorded to Mrs. Kay Ovia, whose vision inspired the Christmas Light-Up, and Quantum Markets, the Bank’s longstanding partner, for its creativity and dedication to delivering spectacular decorations over the years.
The evening featured captivating performances by the Zenith Bank Choir and Nigerian music star Khaid, whose spirited performance added excitement and colour to the celebration. The event culminated in the ceremonial illumination of Ajose Adeogun Street, as an enthusiastic countdown spelling out “ZENITH” brought the Christmas lights to life.
The dazzling display, which has become a prominent feature of Lagos’ festive landscape, is expected to attract thousands of visitors from within the state and beyond throughout the Christmas and New Year celebrations, offering families and tourists an enchanting setting to enjoy the season and create lasting memories.
The Christmas Light-Up forms part of Zenith Bank’s longstanding commitment to corporate social responsibility, which remains integral to its operations and corporate philosophy. Through sustained investments in education, healthcare, infrastructure development, environmental sustainability and other community-focused initiatives, the Bank continues to demonstrate its dedication to improving lives, empowering communities and contributing meaningfully to Nigeria’s socioeconomic development.
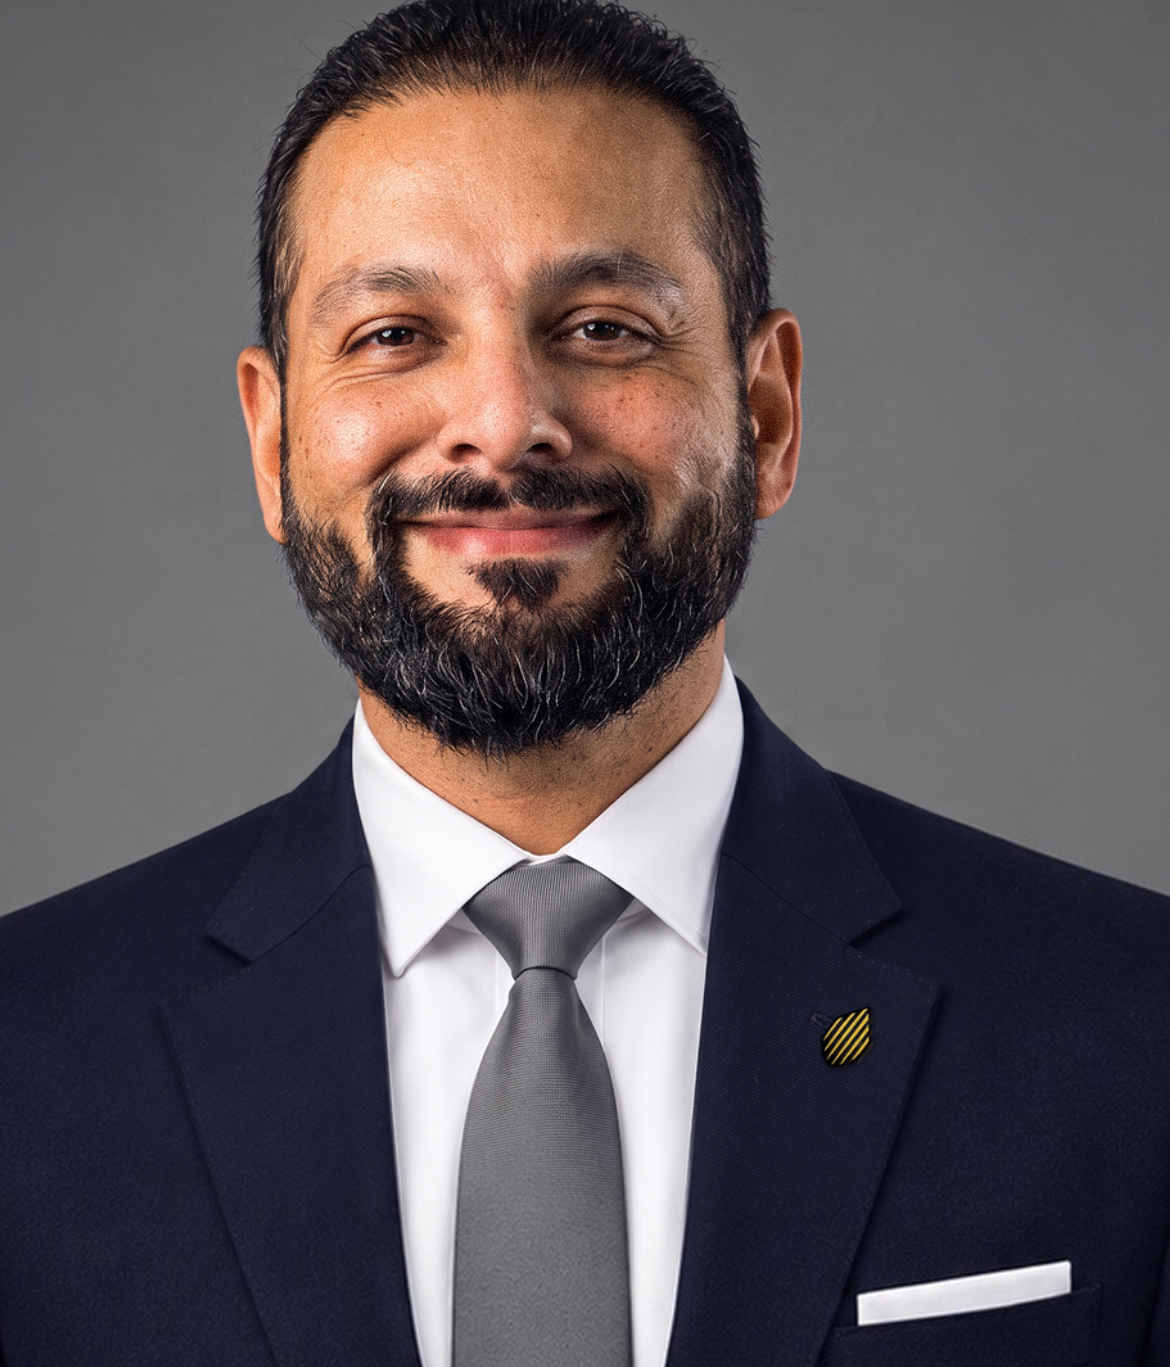
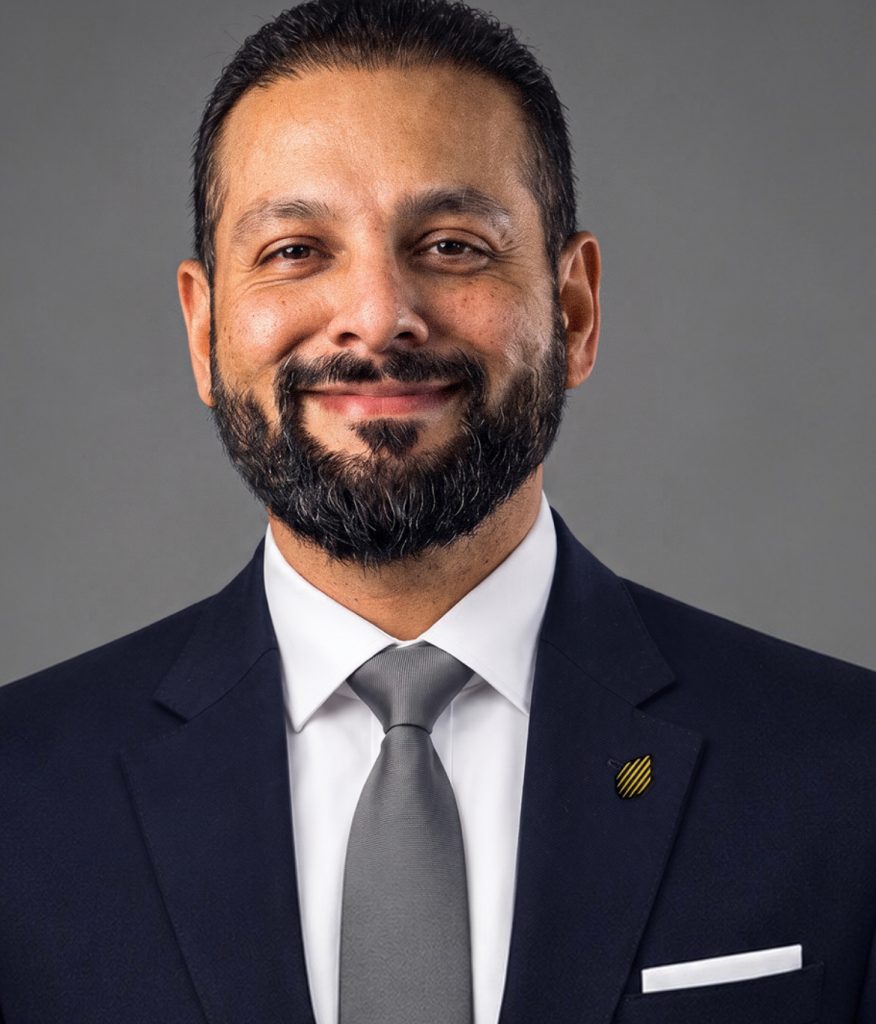 The Alternative Bank Limited (Alt Bank) has announced the appointment of Gul Khan as Managing Director and Chief Executive Officer following approval by the Central Bank of Nigeria (CBN). He succeeds Hassan Yusuf, the Bank’s founding Managing Director.
Khan brings more than 25 years of international financial services experience, having worked in Europe, America, Asia, Middle East & Africa. Most recently he served as Chief Executive Officer and Board Director of I&M Bank Kenya and was Group Head of Products for Airtel Money, the fintech business across 14 markets in Africa. He alsopreviously served as Global Head of Retail Banking and Wealth Management at HSBC Amanah, the Group’s non-interest banking business. His career also includes executive leadership roles with banks in UAE, Egypt and Qatar giving him experience across established banking institutions and technology-led financial services businesses.
Commenting on the appointment, Muhtar Bakare, Chairman of Alternative Bank, said “Gul’s expertise in non-interest banking and his leadership experience across African financial services position him well to lead Alternative Bank through its next phase of growth. The Board is confident in his ability to build on the Bank’s foundations and broaden its reach, while maintaining the strong governance and commercial discipline essential to long-term success.”
Khan will work with the Board and management team to guide the Bank’s next phase of growth. Outlining his priorities, he said:
“The opportunity is to make Alt Bank the preferred choice for consumers and businesses in Nigeria. That means understanding what customers need, whether acquiring productive assets or growing their businesses, and providing solutions that are relevant and they can use with ease. I look forward to working with colleagues to build on Alt Bank’s progress and earn our customers’ continued trust.”
Alt Bank met the CBN’s revised minimum capital requirement for national non-interest banks well ahead of the regulatory deadline. The Bank has also completed its migration to MIZAN, a core banking platform designed for non-interest financial institutions. Its strengthened capital base and investment in technology support its capacity to finance business growth and develop products that meet the needs of its customers.
The Alternative Bank is part of Sterling Financial Holdings Company Plc, a diversified Nigerian financial services group. Backed by the Group’s institutional strength, governance framework and commitment to innovation, the Bank continues to advance its mission of expanding access to non-interest financial solutions for individuals and businesses across Nigeria.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
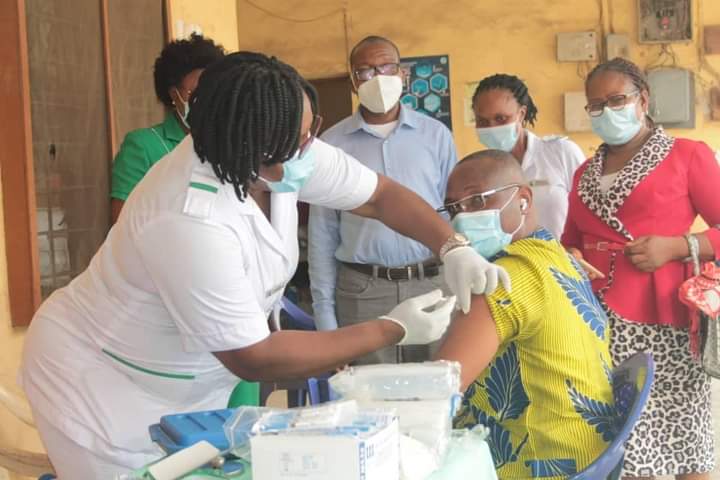
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news2 years ago
BREAKING: Tinubu swears in new NNPCL Board
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19