news
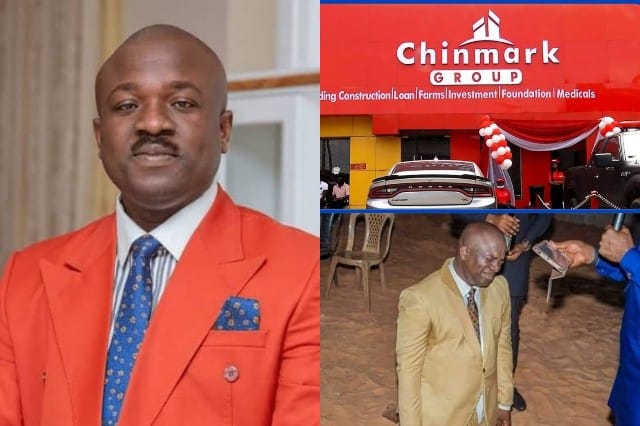
How Marksman Ijiomah CEO Chinmark Group, defrauded, Over 4000 investors

…I have been duped of my 20million, blocked from all channels— Udosen
…Chinmark defrauded, killed my father— another victim
…SEC declared Chinmark operations illegal
….Investors threaten to assassinate me over unpaid funds – influencer
Over 4000 indignant investors have called out the Chief Executive Officer, CEO, of Chinmark Group, Marksman Ijiomah, over unpaid funds invested in the company in spite of the many deadlines given for refund.
Involved in the situation include two social media influencer and brand ambassador for the “investment company”, Amanda Chisom; and another social media promoter of Chinmark, Harrison Gwamnishu.
For days, the aggrieved investors have launched trials on social media, dragging Chinmark, Ijiomah, Chisom, Gwamnishu and all other brand ambassadors who promoted the company on Facebook, Instagram, Twitter and other social media platforms since they began operations.
Newsthumb learnt that the investors made payments running into billions under a contractual agreement that the company would on a monthly basis pay a flavour-packed ROI to them.
In a press statement released on the 25th day of December, 2021 on its official website, SEC described Chinmark as an “illegal operator”, freezing its accounts.
The statement reads in part: “The Commission hereby notifies the investing public that neither FinAfrica Investment Limited nor Chimark Group is registered by the SEC and the Investment Scheme promoted by these entities are also not authorized by the SEC.
In a statement on his verified Facebook page, Chinmark CEO (Ijiomah) confirmed that his group received funds from “4,966 partners”, noting that “500 partners” have been paid so far but he had yet to publish the names of those that had received payment.
While he did not reveal the total amount received from all the investors, a receipt of a refund to an investor he posted on Facebook read N1.3m.
He, however, pleaded with the remaining 4,466 investors to remain calm, saying that the operational bank accounts of his company were frozen by the Securities and Exchange Commission.
He also noted that Chinmark has received “lots of petitions from government agencies by aggrieved partners”.
Ijiomah wrote, “From the proceeds of our business (Hospitality, Transportation, Food and Logistics) despite our operational bank accounts being frozen by Securities & Exchange Commission (SEC) on December 21, 2021 till date, we resumed payment to our partners on March 16, 2022; so far, out of 4966 partners, we have been able to pay 500 partners following an arithmetic order from our backlogs.
“In a bid to show transparency in our dealings as always, full names of paid partners ought to have been published today but several calls/messages/emails from our distinguished partners have further restricted us from doing this.
“Let me reassure you that your money is safe with us and we remain committed to repaying all partners soonest, update on partnership repayment will be provided always and your managers will call to follow up; until then, I would humbly request you to kindly bear with us.”
Amid the endless social media brawls one of the promoters of Chinmark on Facebook (Chisom) has said that aggrieved investors of the group have continued to issue threats over her life on the basis of unpaid funds.
In an official statement on her verified Facebook page, Chisom with over 165,000 followers wrote, “First of all, let me acknowledge my part in being one of those who brought Mr. Marksman Chinedu Ijiomah and his company to limelight, even before the company became registered as Chinmark Group Limited. For someone I have known from the days of his humble beginnings, I felt like I know him to an extent…
“I did my best both professionally and as an individual, to ensure that what is happening now would never have happened, by providing the right advice to the company at all times when I had the opportunity.
“In the build-up to this time, on the 13th of January 2022, I was instructed by the company via an email, to refrain from saying anything about the company on my page and that closes all channels of communication. All effort to find out what was happening was completely blocked.
“I received several warnings and threats from some individuals and investors who felt that my Facebook post on ‘due diligenc’ affected the fortunes of the company. The threats are so far-reaching, that some of these persons have clearly threatened to assassinate me, should anything happen to the company.
“I have informed the relevant authorities of the extent of my involvement with the company and pledged my co-operation in any investigation that may arise.”
Also, another promoter of Chinmark (Gwamnishu) with over 158,000 followers on Facebook said he has gathered about 1,000 investors, even as he assured them that their funds would be recovered.
In a statement on his verified Facebook page on Monday, he wrote, “From my own end as a friend to Chinmark Group and who also posted and shared his business on my page. Below are steps I’m taking to ensure partners don’t lose out completely.
“I was able to get about 1,000 Chinmark investors through a google link I created and today they will be added to a platform.
“A committee will be appointed by the partners to interface with the company. This is a one-on-one meeting where decisions will be taken.”
Some of the investors who made their stand known in different Facebook posts, said that the current reality is unbelievable and that they would engage whatever means possible in ensuring that they get back their money.
An Akwa-Ibom born, Mercy Udosen, who took to her Facebook page to lament on how she invested a whopping 20 million, said that she has been patient for a positive reply from Chinmark but to no avail she has been left totally disappointed and bewildered.
She bemoaned: “Marksman Chinedu Ijiomah chairman of Chinmark group I’m still a very patient girl and patiently waiting for you to do the needful.. you guys can’t just reach out to us since January with the notice that payments of our dividends will commence from 19th of March which I patiently waited cause In your word when paying you will pay for both January and February all for me to get another call yest 18th a day to when you promised to pay the 2 month failed payment telling me the option I have is to take a post dated cheque to cash In 8months time!.. this 8month you said without my monthly dividends being paid, sir isn’t that a joke? So you will keep my 20million naira for a year and do ur business without paying my monthly dividends??
“Please do the needful I beg you before I start mine… why can’t anyone be trusted in this country? You came on your page and posted that you have started paying investors which is not true and you deactivated your comment section so I couldn’t even write to counter your post. Sir I know I can find you down to dubai so don’t test my patience.
“So the other day I came on my Facebook page and I posted about Chinmark, and I said I was one of the investors of Chinmark group of company.
“Yes, I invested 20 million naira with Chinmark through my fiance and dividends was meant to be paid every month that’s 1 million naira to us and the only one we got was for December, that they paid us just once on the 30th of December, expecting our January and February payments, stories came up.
“First they called us on the 28th of February, and they informed us that they were having issues with SEC and you know payments is on hold, they can’t make payments and all of that of which I have been very, very understanding because I’m also a business person, but then you kept us waiting for this payment till February. I didn’t get anything. February nothing came and this is March you promised 19th of March, we’re going to pay me but nothing has come.
“Please say I’ve been so understanding I feel very bad with this news. You know, I tried as much as I could to make sure I did not join, you know, whatever rumours I saw on social media about you guys, but treating me like this is totally unfair. I’m demanding 50% of my capital, which is 10 million naira. And then you can give me a cheque of 10 million. You can’t just put my life on hold like that for Christ sake. There’s a lot of things I could as well use the money to do and then I’ll make returns. I’ll make profits for myself.
“People cannot just be trustworthy. How can you expect for Christ’s sake 20 millionaire you’re not even thinking of paying anything even on me that we are supposed to terminate our contracts which that money. I just wanted it to stay with you guys before I can figure out what to do with it.”
Another victim, Mark John (not real name), stated that Chinmark is the reason for the demise of his father, following the investment of his gratuity funds into Chinmark.
He said: “Chinmark made me lose my father cos he invested his gratuity in chinmark which she promoted… he die yesterday due to HBP cos of the breaking news that chinmark won’t pay…whoever knows Amanda should tell her to get ready for another burial in her family compound again this year cos am taking one of her family member down.”
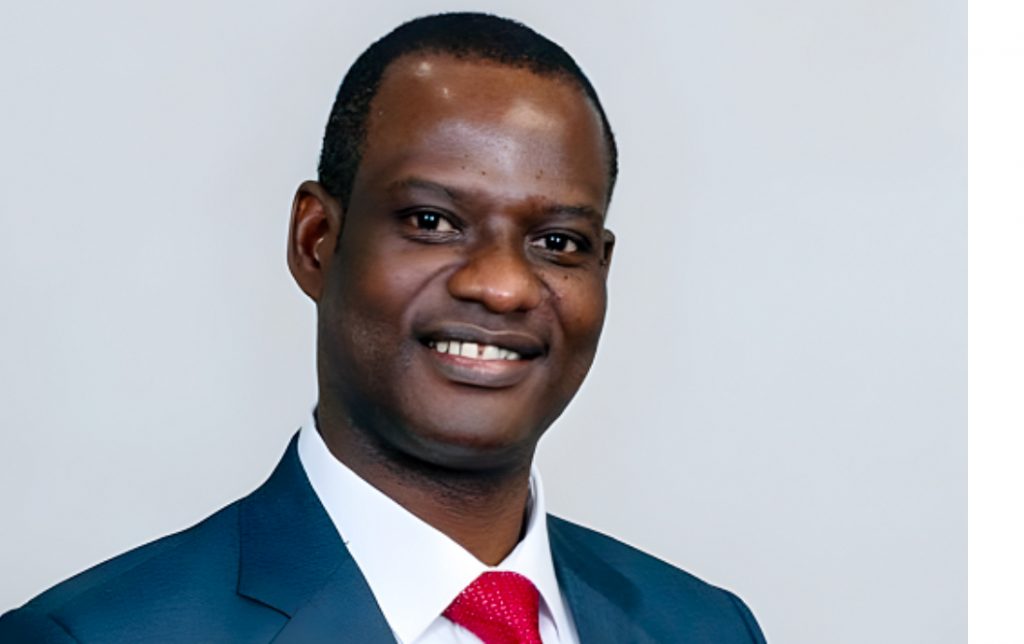
The Federal Government on Wednesday defended its $21.7bn supplementary external borrowing plan submitted to the National Assembly, describing it as a strategic investment programme rather than debt accumulation.
It revealed that the administration it succeeded had printed over N30tn, equivalent to more than $20bn at the time, and the country is still absorbing its inflationary impact.
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, made the claim when he briefed State House correspondents after the Federal Executive Council meeting presided over by President Bola Tinubu at the State House, Abuja.
Oyedele, who spoke on the state of the economy, had presented 10 memos, all of which were approved by the council.
The first, he said, was a €155.9m credit facility from Deutsche Bank and other banks to upgrade 132/33kV substations under the Presidential Power Initiative Phase One, which he said would improve power reliability for homes and businesses and lower energy costs. The second was a $970m syndicated term loan from Standard Chartered and the Africa Finance Corporation for rolling stock on the Karu–Maradi rail line, intended to boost freight, regional trade, and the Northern Economic Corridor while reducing logistics costs.
The third was a €76.8m credit from the ECOWAS Bank for Investment and Development to Bauchi State for a transport infrastructure development programme, covering rural and urban roads and farm-to-market access routes to support food security.
The fourth was an approval for non-intrusive inspection scanners for the Nigerian Customs Service to speed up cargo clearance, reduce smuggling and misdeclaration, and intercept contraband and small arms.
He explained, “As I said, there were 10 of them. I’ll just briefly speak to about four of them. One of them was a 155.9 million euro credit from Deutsche Bank and some other banks directed at upgrading about 132/33 kV substations and a few other ones. There are five of them, actually, five new ones under the Presidential Power Initiative Bash One. Essentially, this is a government intervention that will help ensure more reliable power for homes and businesses and lower energy costs.
“Another memo was with respect to a $970m syndicated term loan by Standard Chartered Africa Finance Corporation on rolling stock for the Karu-Maradi rail line. What is the essence of this? This will give us shipper freight, regional trade, the Northern Economic Corridor and lower prices for logistics, inflation and price levels.
“Another one was 76.8 million euros. This is from the ECOWAS Bank, and it is credit to Bauchi State for the Transport Infrastructure Development Programme, and this is going to help us with rural and urban roads, and to build farm-to-market access roads that will help with food security.
“And finally, council approved the investment in a non-intrusive inspection scanner for technical support, repairs, and maintenance to the Nigerian Customs Service. What is the essence of this? It will help with faster cargo clearance, less smuggling, and less misclassification. And we can then detect when some evil people want to bring in contraband and dangerous small weapons to our country.”
On the $21.7bn supplementary external borrowing plan, obtained by our correspondent from a presidential aide, Oyedele pushed back against critics who had described it as debt, insisting that the Tinubu administration was simply investing in critical infrastructure.
“So, another part of this presentation is on the borrowing plan that was presented to the National Assembly. Altogether, if you convert the euro amount and add it to the dollar amount, it comes to $21.7bn. And we’ve seen some people with commentary saying that we are borrowing X, Y, Z.
“I’m pleased and excited to inform you that actually this does not qualify as borrowing. This qualifies as investment, and I will explain that to you in the next few minutes. Now, so what is this all about? This is an amount or a plan.
“First and foremost, this is a plan. It doesn’t even mean that we borrow all of it. So it’s a plan. The average lifespan of the project under this plan is five years, by the way. So, this means countries need to plan. You can’t be doing everything based on spontaneity and randomness. Now, these amounts, about $10.6bn out of it, are for investment in transportation infrastructure,” he explained.
According to the document, the plan covers 46 projects across 11 sectors, with 29 on concessional or blended terms.
Transportation led with $10.6bn, including sections of the Lagos–Calabar and Sokoto–Badagry highways and the Kano–Kaduna Metro Rail. Ten flagship projects accounted for 58 per cent of the total, at $12.5bn.
The social sectors, agriculture, energy, social protection, climate, and education, totalling $4bn, will be funded entirely on concessional terms.
According to the document, about $7.9bn will come from multilateral and bilateral development partners, led by the World Bank with $5bn at an average rate of 2.1 per cent.
The remaining 11 lender groups include regional development finance institutions, export credit agencies, and commercial banks.
For the commercial component, the average indicative rate is 7.8 per cent, below the 9.1 to 9.6 per cent yield on Nigeria’s November 2025 Eurobond.
Oyedele attributed the gap to credit rating upgrades by Fitch, Moody’s, and S&P.
He noted that $4.8bn of the total was for subnational and agency borrowing, with $3.3bn going directly to states and $1.45bn channelled through agencies and development finance institutions including the Bank of Industry, Development Bank of Nigeria, Transmission Company of Nigeria, and electricity distribution companies.
“The Federal Government has the constitutional duty to be the interface for all external borrowing. So when people say we are borrowing $21.7bn, they need to know that a significant chunk is for states, the FCT, and agencies, not for the Federal Government alone,” he said.
Drawing a comparison with private sector financing, Oyedele argued that the plan would generate returns well in excess of its cost.
He argued, “If Aliko Dangote was going to save money to build his refinery, it would not have been built in his lifetime. He had to take the financing to make it happen. $20bn is now listed in less than four years, and the value has more than doubled. This is exactly what we are doing for our country.
“There are people who will tell you borrowing is bad. You just need to ask them: in which country on this planet do you run an economy without borrowing? To the extent that you borrow one naira to create value of more than one naira, you should please borrow more.”
On food price stability, which was adopted by the council as a priority resolution, Oyedele said the Federal Government was pursuing a national approach coordinated with state governments under the National Economic Council’s 90-day action plan.
“The short term is to ensure that in the coming months, leading up to the end of the year, the price of the most important staple items, rice, yam, beans, maize, remains stable or comes down,” he said.
He said the government would map the gap between local consumption and local production to calibrate targeted imports, adding that only unprocessed brown rice would be imported to preserve local milling jobs and processing capacity.
Over the medium and long term, the plan envisaged expanded irrigation farming to allow year-round agricultural production, improved crop yields through science, and significant reduction of post-harvest losses.
“We will not only be food sufficient; prices will be stable and affordable, and we will export, and a lot of it will be processed before we export. There is nothing that says people cannot be rich doing farming. This is the level we are getting into,” Oyedele said.
Speaking earlier, Oyedele contrasted the state of the economy in May 2023, describing Nigeria as having been weeks away from a full economic collapse when the Tinubu administration took office.
He said, “Inflation was at 22.41 per cent, and our reserve was net of $859m, not even enough to cover one month of imports. We had a spread between the official rate and the parallel rate of over 60 per cent premium, enabling round-tripping by the highly connected, while businesses, including manufacturers, could no longer access foreign exchange.
“We had printed altogether over N30tn to spend, and the impact of that amount, at the time, this was more than $20bn, is what we are dealing with today in inflationary pressure. Debt service at the time was consuming 97 per cent of revenue, nearly 100 per cent, and about 27 states could no longer reliably pay salaries. They were owing arrears of pension and gratuities.”
He said without the reforms, Nigeria would have slipped into hyperinflation and a full currency collapse far more severe than the devaluation that has taken place.
On petrol subsidy removal, Oyedele traced the policy to 1973, noting that a litre of premium motor spirit sold for six kobo then and N195 when the subsidy was removed in 2023, a 3,050-fold increase over 50 years that never resolved the underlying problem.
“Each time we increased the PMS price, Nigerian people suffered for it, but no benefit came. This is the first time in that half-century that the problem has now been solved, and the benefits are now accruing to our country,” he said.
The minister said growth had accelerated from 2.74 per cent in May 2023 to 4.43 per cent as of the second quarter of 2026, more than 60 per cent improvement, and Nigeria’s dollar-term growth rate in the first half of 2026 stood at 17 per cent, placing it among the world’s fastest-growing economies.
“This is the reason why we are classified by the IMF as one of the top 10 countries in the world contributing to global GDP growth,” he said.
On inflation, Oyedele said the September 2026 print of 14.63 per cent was down from 20.98 per cent a year ago and from a peak of about 34 per cent at the height of the inflationary pressure.
He added that month-on-month food inflation had fallen by 1.55 per cent, describing it as deflation in food prices.
Foreign reserves, he said, had risen to an 18-year high of over $55bn, with net reserves now exceeding $45bn, up from less than $1bn three years ago, a 45-fold increase.
The naira, currently trading between N1,330 and N1,350 to the dollar, was projected to appreciate further.
“Even the IMF estimates that the naira is about 25 per cent undervalued. So anybody who wants to bet against the naira should make provision for their losses. The currency to hold is the naira, even more than the US dollar or pound sterling,” Oyedele said.
He said the tax-to-GDP ratio rose from barely 7 per cent in 2023 to about 12.5 per cent at the end of 2025, while the debt service-to-revenue ratio fell from 97 per cent to under 60 per cent and was still declining.
Federation Account allocation grew 44 per cent from 2024 to 2025, with a projected 50 per cent growth from 2025 to 2026, and a real growth rate, stripping out inflation, of over 80 per cent across the two years.
Internationally, he said Fitch, Moody’s, and S&P had all upgraded Nigeria’s credit rating, with outlooks recently adjusted from stable to positive. Nigeria had also exited the Financial Action Task Force grey list and the European Union’s deficiency list, he added.
Responding to what he described as a recurring question about the gap between macroeconomic improvements and the lived experience of average Nigerians, Oyedele cited a series of direct interventions.
He stated, “To date, we have N372.6bn disbursed through NELFUND to more than 1.5 million students, which means their parents and guardians do not have to worry about tuition and stipend. We have more than 10 million households that have received cash transfers worth more than N600bn, and the target is to reach at least 15 million households,” he said.
Over 800,000 micro, small, and medium enterprises had received single-digit subsidised loans, mostly through the Bank of Industry, he added. Also, low-income earners earning up to N100,000 per month had been exempted from personal income tax, while small businesses with annual turnover of not more than N100m, representing about 97 per cent of over 40 million small businesses, were exempted from corporate income tax, VAT obligations, and withholding tax deductions.
The minister also noted that the capital market had grown from about N30tn to over N160tn, a more than fivefold increase in three years, and that more than 90 per cent of capital market investors were small investors who had been granted capital gains tax exemptions.
Council, he said, adopted a resolution to target single-digit inflation by the end of 2027 or earlier, stabilise and reduce food prices, and sustain fiscal discipline through the election cycle.
Oyedele’s defence comes amid criticism of President Bola Tinubu’s request to the National Assembly for approval of the loan plan.
The presidential candidate of the African Democratic Congress, Atiku Abubakar, the Makinde/Daura Campaign Council and others have criticised the Federal Government’s borrowing plan.
On Tuesday, Atiku urged the National Assembly to suspend consideration of the request until the Federal Government made public the projects the loans were intended to finance.
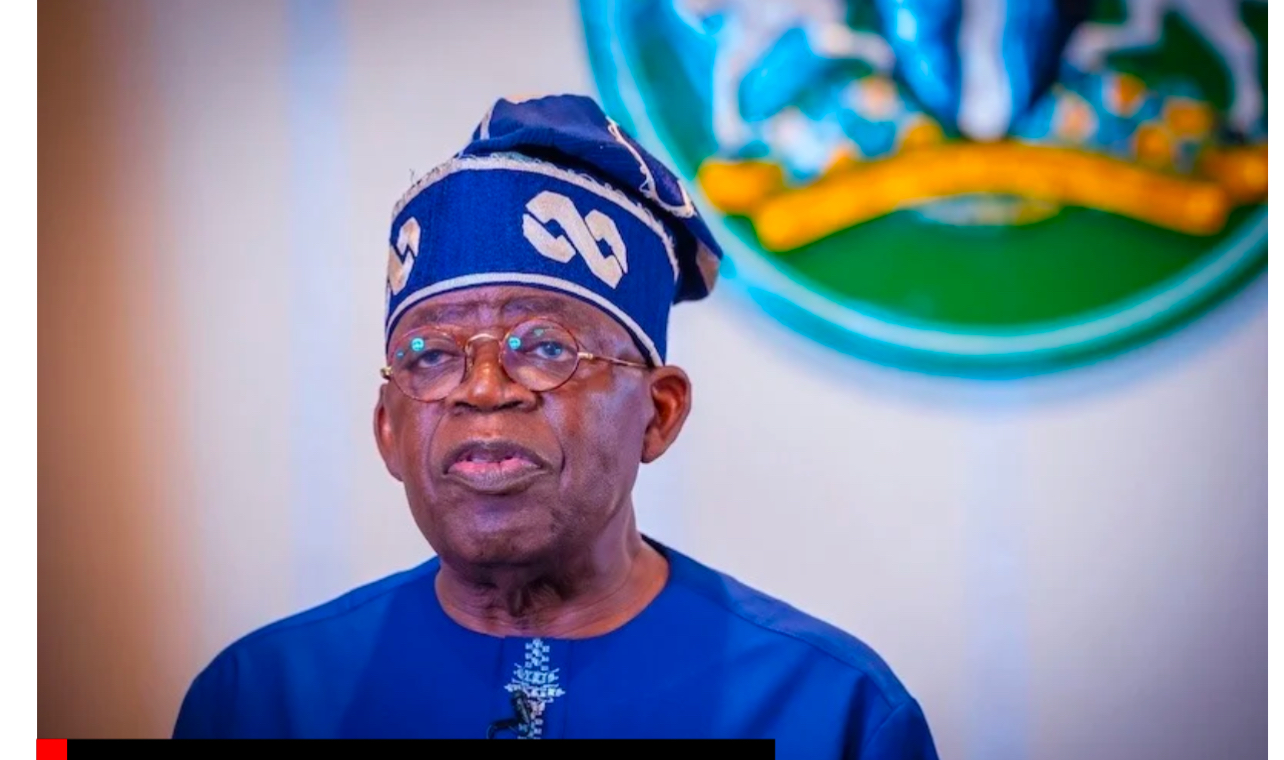
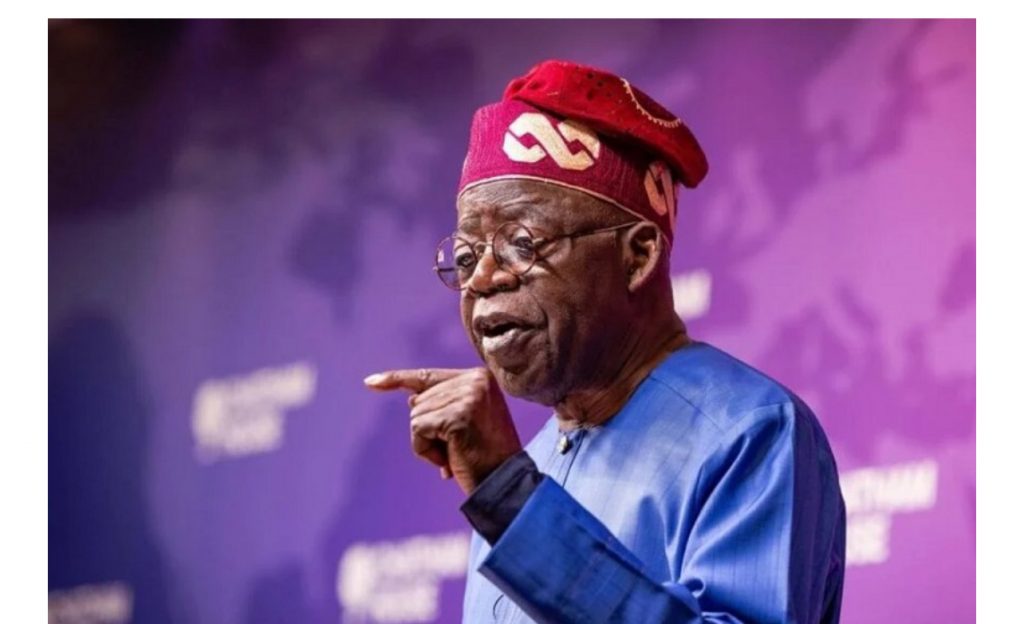
President Bola Tinubu has blamed his political opponents for hunger and poverty in Nigeria, saying his administration is working to address the challenges.
Tinubu spoke on Saturday at the All Progressives Congress presidential campaign flag-off rally at Ranchers Bees Stadium in Kaduna State ahead of the 2027 general elections.
“I have an argument. I hear my opponent talking about hunger, poverty. Who created it? They did! They created the hunger, they created the poverty. We are trying to eradicate it,” the President said.
He also defended his administration’s record on salary payments and praised governors for their performance.
Nigeria’s debt interest payments exceed revenue by ₦1.5 trillion
“We pay salaries regularly. Our governors are working. I am proud of them. They are developing,” he said.
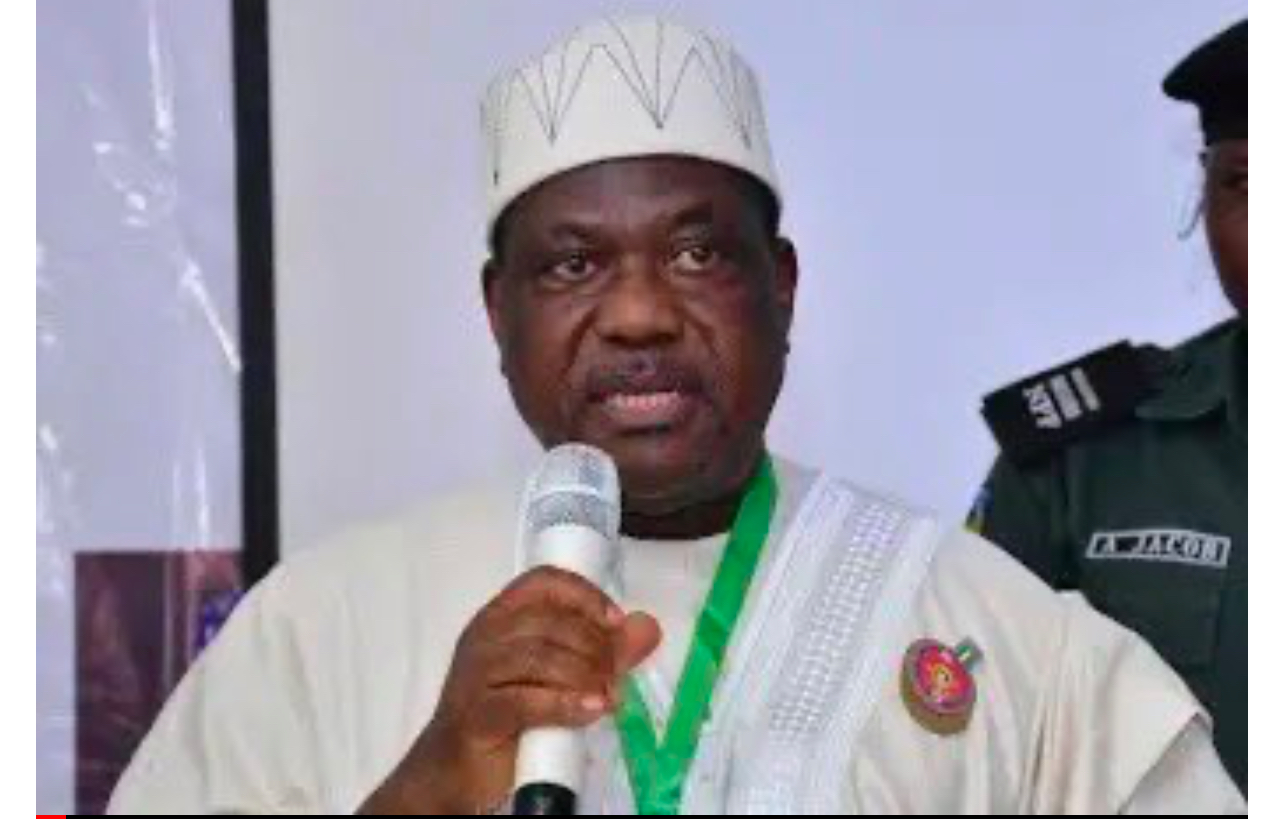
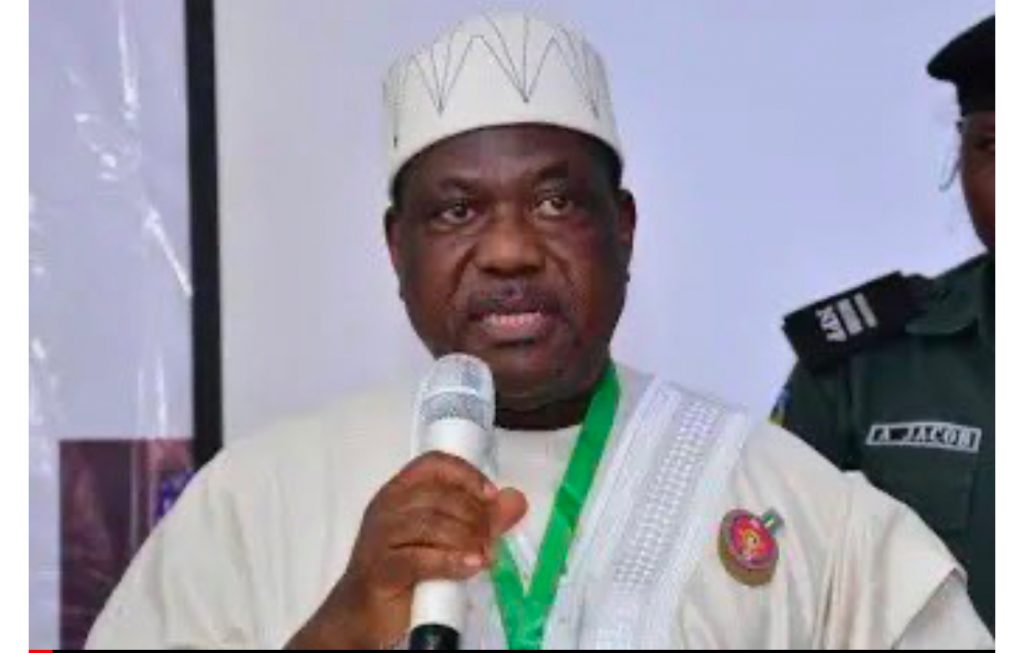 The Secretary to the Government of the Federation, Senator George Akume, has said the North should support President Bola Tinubu for a second term in 2027.
He insisted that any Northerner seeking the presidency in 2027 would be working against the region’s interests.
Akume said the North should allow Tinubu to complete his political project before considering another presidential bid in 2031.
The SGF stated this on Saturday while addressing Benue State indigenes resident in Kaduna ahead of the flag-off of the All Progressives Congress presidential campaign in the state capital.
He urged Northerners to remain united and resist political ambitions capable of dividing the region ahead of the 2027 general elections.
Add us to your Preferred Sources
“The North must remain united and focus on its collective interest rather than allow individual ambitions to divide us,” Akume said.
The former Benue State governor argued that the region needed to consider its long-term political interests and the implications of the 2027 presidential election for its future.
He said, “President Bola Tinubu should be allowed to complete his political project before the North considers its own presidential ambition in 2031.”
Akume also cautioned against attempts to divide Northerners along political, religious and personal lines, stressing that unity remained essential to the region’s political relevance.
“We must not allow political, religious or personal differences to undermine our common interests. The strength of the North lies in our ability to work together,” he said.
The SGF further called for peaceful coexistence and cooperation among Nigeria’s diverse ethnic and religious communities, saying national development depended on unity.
He urged the people to examine political developments carefully and avoid being misled by individuals whose ambitions might conflict with the broader interests of the region.
The meeting brought together Benue indigenes living in Kaduna and other political stakeholders to discuss issues affecting their community, political representation and engagement with leaders at the national level.
The APC presidential campaign flag-off in Kaduna is expected to bring together party leaders, supporters and political stakeholders from across the country.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
news8 years ago
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title