news
Just IN : Tinubu Approves Taiwo Oyedele as Chairman of Fiscal Policy and Tax Reforms Committee

President Bola Tinubu has approved the establishment of a Presidential Committee on Fiscal Policy and Tax Reforms.
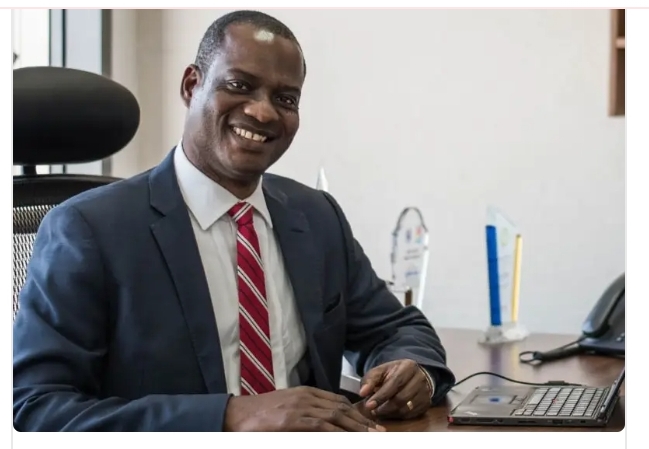
The committee according to a statement issued by Dele Alake, Special Adviser to the President on Special Duties, Communications and Strategy on Friday will be chaired by Fiscal Policy Partner and Africa Tax Leader at PriceWaterhouseCoopers (PwC), Mr. Taiwo Oyedele.
The statement said that setting up the committee was in consonance with President Tinubu’s promise to remove all barriers impeding business growth in Nigeria.
It explained that the committee will comprise experts from both the private and public sectors and have responsibility for the various aspects of tax law reform, fiscal policy design and coordination, harmonization of taxes, and revenue administration.
Explaining further, the Special Adviser to the President on Revenue, Mr. Adelabu Zacch Adedeji, said that President Tinubu recognizes the importance of a sound fiscal policy environment and an effective taxation system for the functioning of the government and the economy.
He said, ”Nigeria ranks very low on the global ease of paying taxes while the country’s Tax to GDP ratio is one of the lowest in the world and well below the African average.
”This has led to an overreliance on borrowing to finance public spending which in turn limits the fiscal space as debt service costs consume a greater portion of government revenue, annually resulting in a vicious cycle of inadequate funding for socio-economic development.
”While some incremental progress has been recorded over the years, the outcomes have not been transformative enough to change the narrative,” he said.
Adedeji outlined the key challenges in Nigeria’s tax system to include multiple taxes and revenue collection agencies, fragmented and complex tax system, low tax morale, high prevalence of tax evasion, high cost of revenue administration, lack of coordination between fiscal and economic policies, and poor accountability in the utilization of tax revenue.
The establishment of this committee reflects President Tinubu’s commitment to addressing these challenges and bringing about transformative reforms in fiscal policy and taxation.
The committee’s primary objective is to enhance revenue collection efficiency, ensure transparent reporting, and promote the effective utilization of tax and other revenues to boost citizens’ tax morale, foster a healthy tax culture, and drive voluntary compliance.
These efforts will not only improve Nigeria’s revenue profile but also create a more conducive and internationally-competitive business environment.
”Our aim is to transform the tax system to support sustainable development and achieve a minimum of 18% Tax to GDP ratio within the next 3 years without stifling investment or economic growth.
”It should be noted that this committee will not only advise the government on necessary reforms, but will also drive the implementation of such recommendations in support of the comprehensive fiscal policy and tax reform agenda of the current administration,” the SA on Revenue added.
Mr. Oyedele is said to be a highly accomplished professional with extensive expertise in fiscal policy, taxation, and economic matters. He currently serves as PWC Africa tax leader.
He is the Thematic Lead for the Fiscal Policy & Planning Commission and serves as the Chairman of the West Africa Debt Management Roundtable of the Nigerian Economic Summit Group (NESG).
He chairs the Taxation & Fiscal Policy Faculty Board of the Institute of Chartered Accountants of Nigeria (ICAN) and is a member of the Nigerian Taxation Standards Board.
He also serves as a member of the Ministerial Committee on the implementation of Nigeria’s National Tax Policy.
He is a member of the Global Tax Forum and has previously served as a member of the Global Governing Council of the Association of Chartered Certified Accountants (ACCA).
As an educator, Oyedele holds the position of Associate Professor at the Babcock University Business School.
He is an alumnus of the London School of Economics & Political Science, Yale University and Harvard Kennedy School Executive Education. He is a guest lecturer at the Lagos Business School and the Founder and President of Impact Africa Foundation.
By Cynthia Alo To prevent collapse of the manufacturing sector, job losses and more suffering for Nigerians at the bottom of the economy ladder, world’s leading management and financial consultancy, PricewaterhouseCoopers, PwC, has called on the Federal Government to improve the tough operating environment in the country before imposing the proposed…
news
Nigeria Emerges as Africa’s Biggest Climber in Investment Risk Ranking on Back of Tinubu’s Economic Reforms
Nigeria has emerged as the biggest climber in Africa’s latest investment risk ranking, rising four places to eighth position as economic reforms implemented by President Bola Tinubu improved the country’s relative attractiveness to investors, a new report by Bloomberg has stated.
Nigeria overtook Rwanda, Tanzania, Kenya and Namibia in the 2026 Bloomberg Economics Investment Risk-O-Meter, which assesses the relative investability of 19 African economies.
Bloomberg, in the report released on Monday, said Nigeria’s improvement was driven by stronger performance in three of the five indicators used in the assessment: economic strength, fiscal strength and external vulnerability.
“Nigeria was the biggest climber in a ranking of Africa’s most investable markets, propelled by President Bola Tinubu’s economic reforms, according to the findings of the latest edition of An Investor’s Guide to Africa.
“The continent’s biggest oil producer and refiner rose four places to eighth in the 2026 Bloomberg Economics Investment Risk-O-Meter, overtaking Rwanda, Tanzania, Kenya and Namibia as it improved in three of the five metrics assessed by the gauge: economic strength, fiscal strength and external vulnerability,” Bloomberg reported.
The development puts Nigeria among the biggest gainers on the continent, despite ongoing concerns about the country’s high public debt, cost of living, inflation, infrastructure deficit and foreign exchange pressures.
Mauritius emerged as the most investable African market in the latest ranking, while Botswana fell two places. South Africa, which topped the ranking in the previous edition, also dropped one place following a weaker economic growth outlook.
Nigeria’s improved position comes more than three years after Tinubu assumed office and embarked on a series of major economic reforms aimed at restructuring the country’s fiscal and monetary environment.
Add to Preferred Sources
Among the most significant measures were the removal of the petrol subsidy, reforms to the foreign exchange market and changes to electricity tariffs.
The Federal Government has repeatedly defended the reforms as necessary to address distortions that had weighed on public finances, discouraged investment and placed pressure on foreign exchange reserves.
However, the policies have also increased economic hardship for households and businesses, particularly through higher transport, food and energy costs. Despite the adjustment pains, Nigeria’s economy has continued to expand during the period under review.
Real Gross Domestic Product growth rose from 2.54 per cent in the third quarter of 2023 to 3.46 per cent in the fourth quarter of that year.
The economy subsequently grew by an average of 3.19 per cent in 2024 before accelerating to 3.85 per cent in 2025, its strongest annual performance within the period covered by the assessment.
Growth stood at 3.89 per cent in the first quarter of 2026, bringing the average quarterly growth between the third quarter of 2023 and the first quarter of 2026 to about 3.46 per cent.
The stronger growth performance has come alongside efforts by the government to increase revenue, reduce fiscal leakages and attract investment into critical sectors of the economy.
Nigeria’s improved position in the Bloomberg ranking, however, comes against the backdrop of a substantial increase in public debt.
Data from the Debt Management Office showed that Nigeria’s total public debt stood at N87.38tn as of June 30, 2023, shortly after Tinubu took office. By December 31, 2025, the figure had risen to N159.28tn. This represents an increase of N71.90tn, or about 82.3 per cent, in two and a half years.
The increase was driven by new borrowing, foreign exchange adjustments and the securitisation of certain legacy obligations, according to the DMO.
The development is significant for a country that has struggled for years to attract sufficient foreign capital because of concerns over exchange-rate instability, policy uncertainty, weak infrastructure, insecurity and limited fiscal space.
The reforms under the Tinubu administration have sought to address some of these constraints by allowing market forces a greater role in determining fuel prices, foreign exchange rates and electricity tariffs.
The foreign exchange reforms, in particular, were designed to reduce multiple exchange rates and improve transparency in the currency market, while the removal of the petrol subsidy was intended to reduce the government’s fiscal burden.
The electricity tariff reforms were also aimed at improving the financial viability of the power sector and encouraging investment by allowing electricity prices for some customer categories to better reflect supply costs.
Nigeria’s rise in the Bloomberg ranking therefore marks an improvement in its relative position among African investment destinations, even as investors continue to monitor the sustainability of its reforms, debt burden and economic growth.
President Bola Ahmed Tinubu is expected back in Abuja this evening after concluding a six-day stay in Lagos, the Presidency announced on Monday.
The President will depart Lagos for the Federal Capital Territory after a visit during which he participated in activities marking Nigeria’s 66th Independence Day anniversary and held other engagements. SahelSecurity Report
Tinubu arrived in Lagos on Tuesday, September 29, following his annual holiday in London and Paris.
While in Lagos, the President addressed Nigerians on October 1 to mark the country’s 66th Independence Day anniversary.
Later that day, he attended the national premiere of MKO, a documentary chronicling the life, political struggle, and legacy of the late Chief Moshood Kashimawo Olawale Abiola, as well as the historic June 12 pro-democracy struggle.
Powered by VidCrunch
The premiere was held at the Wole Soyinka Centre for Culture and Creative Arts in Lagos.
Special Adviser to the President on Information and Strategy, Bayo Onanuga, confirmed the President’s return to Abuja in a State House statement issued on Monday.
“President Bola Ahmed Tinubu will depart Lagos for Abuja this evening after his six-day visit to the former seat of government,” Onanuga said.
……Era of shared prosperity begins, Tinubu assures
Nigeria has reached a turning point in its economic recovery, President Bola Ahmed Tinubu declared.
He said the period of painful reforms has accomplished its purpose, and the country is now entering what he described as an “age of prosperity”.
Tinubu, in his Independence Day address to Nigerians marking the country’s 66th anniversary this morning, said the central task of his administration would henceforth shift from correcting structural economic distortions to ensuring that the gains of the reforms translate into lower living costs, jobs, increased production and broadly shared prosperity.
“The age of reform has done its work. Now begins the age of prosperity.
“An age in which the promise of this great nation must finally become the lived experience of Nigerians from all walks of life”, the President said.
He said the government’s immediate priority in the new phase would be to bring down the cost of living by reducing the cost of producing and transporting food and other goods consumed by Nigerians.
Tinubu, who likened the state of the economy his administration inherited in 2023 to a cancer patient requiring painful treatment, said the government had completed what he called the “emergency treatment” of the economy and repaired its foundations.
“My fellow Nigerians, we have reached a turning point.
“The emergency treatment is over. The foundation has been repaired. The central economic task before us has changed. For three years, our overriding purpose was to correct our nation’s course.
“Now, our purpose is simple: shared and widespread prosperity,” he said.
The President said the prosperity being envisaged was not merely about headline economic growth or improved statistics, but about creating conditions under which Nigerians could afford food and transportation, access education and healthcare, secure productive employment and confidently plan their future.
He said his administration would pursue increased agricultural production through mechanised irrigation, dry-season farming, improved access to seeds and fertiliser, greater mechanisation and investment in storage and transportation.
According to him, ongoing investments in roads, railways and ports would also reduce the cost of moving produce and manufactured goods from farms and factories to markets.
“Our logic is simple. When a farmer produces more cheaply, when fewer crops are lost between the farm and the market, when a manufacturer spends less on electricity, when a truck reaches its destination faster, and when the business environment fosters fair competition, all those savings will ultimately find their way into the price of goods in the market,” he said.
Tinubu said job creation, enterprise development and industrial expansion would also be placed at the centre of government policy, with greater emphasis on gas-powered industries, revival of manufacturing centres, digital connectivity and improved access to infrastructure and finance.
The President said the country must convert its huge youthful population into an engine of economic production by equipping young people with skills demanded by employers and creating conditions for Nigerian businesses to expand.
“I want to see more Nigerians making things. I want to see more Nigerian farms feeding our cities and supplying our factories. I want to see Nigerian businesses selling Nigerian goods to the whole world. I want young Nigerians building unicorns and creating opportunities for others here at home,” he said.
Defending the economic reforms undertaken since his assumption of office, Tinubu rejected calls for a reversal of some of the policies, particularly subsidies, arguing that the measures did not create Nigeria’s economic weaknesses but were introduced to confront them.
The President compared previous economic management approaches to administering painkillers to a cancer patient instead of treating the underlying disease.
“For too long, Nigeria’s leaders chose morphine while praying for a miracle that never came.
“They focused on symptoms while allowing the disease to take hold deep within the fabric of our society. We spent enormous sums sustaining inefficient arrangements that were never intended to last. We hid from difficult truths and passed the consequences from one generation to the next,” he said.
Tinubu acknowledged that the reforms imposed hardship on Nigerians, saying their “side effects were real,” but insisted that Nigerians must distinguish between what he described as the medicine and the disease.
“Our reforms did not create the weaknesses in our economy. They confronted them.
“Now, as certain influential but regressive voices would have us abandon the treatment and return ourselves to the abuse of addictive subsidies, we must resist their siren song. We must remember why we began this journey and how far we have already come,” he said.
The President said three and a half years after the reforms began, the country’s economic outlook had improved, citing economic growth of more than four per cent this year, contributions from both oil and non-oil sectors, declining oil theft, falling inflation, improved foreign reserves and greater stability in the foreign exchange market.
He also said Nigeria recorded its highest non-oil export revenue in 2025, exceeding $6 billion, adding that increased foreign direct investment and private sector activity reflected improving confidence in the economy.
While acknowledging that millions of Nigerians were still struggling with food, school fees, healthcare, transportation and other basic needs, Tinubu said the government would continue strengthening support for vulnerable households while pursuing policies capable of lifting people permanently out of poverty.
He said the National Social Register was being improved to ensure assistance reached those genuinely in need, while programmes such as the Nigerian Education Loan Fund and the Nigerian Consumer Credit Corporation, CREDICORP, were designed to broaden access to education and essential assets.
According to him, the government would also work with states and local governments to strengthen primary healthcare, basic education and other public services relied upon by low-income Nigerians.
“These programmes are not substitutes for prosperity. They are a bridge to aid our nation’s citizens on their path towards it. Our objective is not to manage poverty more efficiently.
“We will defeat it,” Tinubu declared.
He admitted that reversing decades of poverty, low productivity, inadequate infrastructure and weak institutions would take time, discipline, sustained economic growth and the creation of millions of productive opportunities.
“We cannot erase in four years what accumulated over generations. But we can change its course. We can build an economy that steadily lifts people out of poverty while ensuring that those who remain vulnerable are not abandoned along the way,” he said.
Reflecting on Nigeria’s 66 years of independence, Tinubu paid tribute to generations of Nigerians who had kept faith with the country despite war, military rule, economic crises, insecurity and political upheavals.
He also praised farmers, traders, teachers, entrepreneurs and members of the Armed Forces and security agencies, saying their sacrifices had sustained the country through difficult periods.
The President said Nigeria’s founding fathers fought not merely for a flag, anthem or international recognition, but for Nigerians to have the freedom to determine their destiny and build a country capable of providing opportunity, dignity and a better life.
He urged Nigerians not to retreat from the difficult choices already made, expressing confidence that the sacrifices of recent years would eventually translate into improved living standards.
“Nigeria has corrected its course. We have passed through our own Red Sea. This is not the time to look back. Let us go forward together, with faith in ourselves, faith in our country, and faith that the sacrifices we have made will yield their reward,” Tinubu said.
Describing the country’s desired destination as a “Promised Land” of abundance, opportunity and broadly shared prosperity, the President said the foundations for that future had already been laid.
“Our destination is in sight. Our foundations are strong. Our direction is clear. So let us go forward. No looking back,” he declared.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 entertainment2 years ago
Ashny Set for Valentine Special and new Album ‘ Femme Fatale’
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title