news
More Trouble As Facebook, Twitter Suspended Trump amid Capitol Hill violence

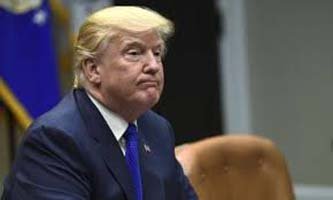
Twitter and Facebook suspended Donald Trump’s accounts for the first time, finally escalating their crackdown on the president’s social media posts after he encouraged and supported rioters at the US Capitol.
Twitter required Mr Trump to delete certain posts after “repeated and severe” violations of its rules on election misinformation, including a video sending love to the violent uprising in Washington protesting his November loss to Joe Biden.
The same video was also removed by Google’s YouTube and helped tip the scales at Facebook, which said it’s banning Mr Trump’s page from posting for 24 hours.
“As a result of the unprecedented and ongoing violent situation in Washington, DC, we have required the removal of three @realDonaldTrump Tweets that were posted earlier today for repeated and severe violations of our Civic Integrity policy,” Twitter wrote in a post on its site.
Once the tweets are deleted, Mr Trump will get his account back after a 12-hour lock is lifted.
For years, social media — especially Twitter — has been Mr Trump’s preferred way to disseminate information directly to the public. Since November, Mr Trump has posted regularly without evidence that the presidential election was “rigged.” Twitter has labelled dozens of Mr Trump’s posts as disputed or misleading and Facebook flagged misleading election posts by pointing users to trusted news sites, but Wednesday was the first time the president has been kicked off either platform even temporarily. Twitter threatened to ban Mr Trump entirely if he continues to break the rules.
“Future violations of the Twitter Rules, including our Civic Integrity or Violent Threats policies, will result in permanent suspension of the @realDonaldTrump account,” the company tweeted from its @TwitterSafety handle.
Most of Mr. Trump’s Twitter messages appear simultaneously on Facebook, where they are spread widely among followers through sharing and commenting. The company recently started labelling misleading Trump posts with links to further context, such as information about Mr Biden’s election win, but has generally allowed users to continue to share and react to his posts until Wednesday’s temporary ban.
The video that Mr Trump was asked to remove on Twitter showed the president addressing rioters at the US Capitol. Mr Trump told them to “go home,” but also called the election result “fraudulent.
Facebook, the world’s largest social network, said it was appalled by the riots and would remove all praise of the insurrection at the Capitol, calls to bring weapons to certain locations across the US, and videos and photos from Capitol protesters.
“At this point they represent promotion of criminal activity which violates our policies,” the company said in a blog post. Facebook’s Instagram photo-sharing service also said it would lock Mr Trump’s account for 24 hours.
Another Trump tweet that was blocked, which appeared as the violence unfolded, read, “These are the things and events that happen when a sacred landslide election victory is so unceremoniously & viciously stripped away from great patriots who have been badly & unfairly treated for so long.”
Twitter has been under pressure for years to take a tougher stance against Mr Trump’s account, which he often uses to spread inflammatory attacks and misinformation. Calls for Twitter chief executive Jack Dorsey to ban the president were widespread on Wednesday. Mr Trump’s supporters had gathered in Washington for a speech in which he encouraged them to demand the election be overturned.
In the past, Twitter has come up with other rules to limit the spread of Mr Trump’s incendiary posts without removing them entirely, including warning labels that obscure the content of messages, arguing against their removal on the grounds of news value coming from a world leader. But Twitter has also taken a firmer line against Mr Trump in recent months. Executives have said that Mr Dorsey is not the final word on punishing elected leaders and that decision falls to its top policy executive, Vijaya Gadde.
Twitter first flagged a handful of Mr Trump’s tweets for misinformation in May, setting off a more aggressive approach to the president’s posts in the midst of nationwide racial justice protests triggered by George Floyd’s death. Since November, dozens of Mr Trump’s tweets have been hidden or labelled for mischaracterising the election results. Shortly after the election, Twitter confirmed that when Mr. Trump leaves office in January, he will not be considered a world leader, and could be punished more severely for his violations.
Twitter shares fell about 2 per cent.
Ok
The Federal Government has announced ten new measures to reduce the pain Nigerians feel from high fuel prices. It insists, however, that none of them brings back the old fuel subsidy for everyone.
The measures were presented by the Federal Ministry of Finance at a press briefing on Thursday, 8 October 2026, titled “Fuel Prices and the Subsidy Question.” The government admitted its earlier steps fell short. According to the presentation, “These measures do not fully relieve the pressure households feel today, so the government is going further.”
The government described the new package as “Help that is targeted, temporary and affordable.” In plain terms, the help is meant for those who need it most, will not last forever, and is designed so that the country can pay for it.
Cheaper petrol and more cash support
The first measure is a discount on petrol sold at NNPC filling stations. The discount will last for the next 30 days, and public transporters, such as commercial bus and taxi operators, will get priority. The government hopes this will help keep transport fares from rising further.
The government also plans to increase cash transfers to vulnerable households. Small businesses will get cheaper loans, known as subsidised credit, to help them cope with higher running costs.
Steps to keep pump prices steady
To protect Nigerians from sudden jumps in world oil prices, the government will sell crude oil in advance to local refineries. This is expected as oil production rises and crude previously committed to other purposes becomes available. The presentation says this will shield “pump prices from global swings.” ShopAfrican Art
The government will also introduce what it calls price modulation. Under this plan, a negotiated limit of ₦1,350 per litre will apply to the ex-gantry price (the price at the depot) or the landing cost (the cost of bringing the fuel into the country). The limit will be reviewed every month, so it can change as conditions change.
A National Strategic Fuel Reserve will also be set up. Fuel from the reserve will be released “under published rules when disruption or hoarding threatens supply.” This means the government can step in when fuel becomes scarce or when marketers hold back products to push up prices.
Lowering the cost of transport and doing business
The government says part of what Nigerians pay for transport comes from illegal charges on the roads. It will work with state governments under the 2025 tax laws to rein in road taxes that push up fares.
It will also speed up the rollout of compressed natural gas (CNG) as a cheaper alternative to petrol, again working with the states. Transporters who benefit from cheaper fuel are expected to “pass savings on in lower fares” to passengers.
Other steps target the cost of goods and services more broadly. The government will cut regulatory costs, described as red tape, that “feed into the price of goods and services.” It will also ease traffic in cities to save fuel, and it will use NIPOST address codes to reduce the cost of moving goods from one place to another.
One measure has not yet been decided. The government is considering an excess profit tax on operators it says exploit consumers. If it goes ahead, the money raised will fund transport support and vouchers for low-income earners.
No return to blanket subsidy
The ministry ended the presentation with a clear message, “None of these measures restores a blanket subsidy.” The government is therefore not returning to the old system, where fuel was sold cheaply to everyone. It says its new approach will reach “the people who need help without putting the wider economy at risk.”
The announcement comes as many households as possible, and businesses struggle with the high cost of transport, food, and other goods linked to fuel prices. How much relief Nigerians feel will depend on how quickly and effectively these measures are carried out, and whether transporters and marketers pass the benefits on to consumers.
news
Nigeria Emerges as Africa’s Biggest Climber in Investment Risk Ranking on Back of Tinubu’s Economic Reforms
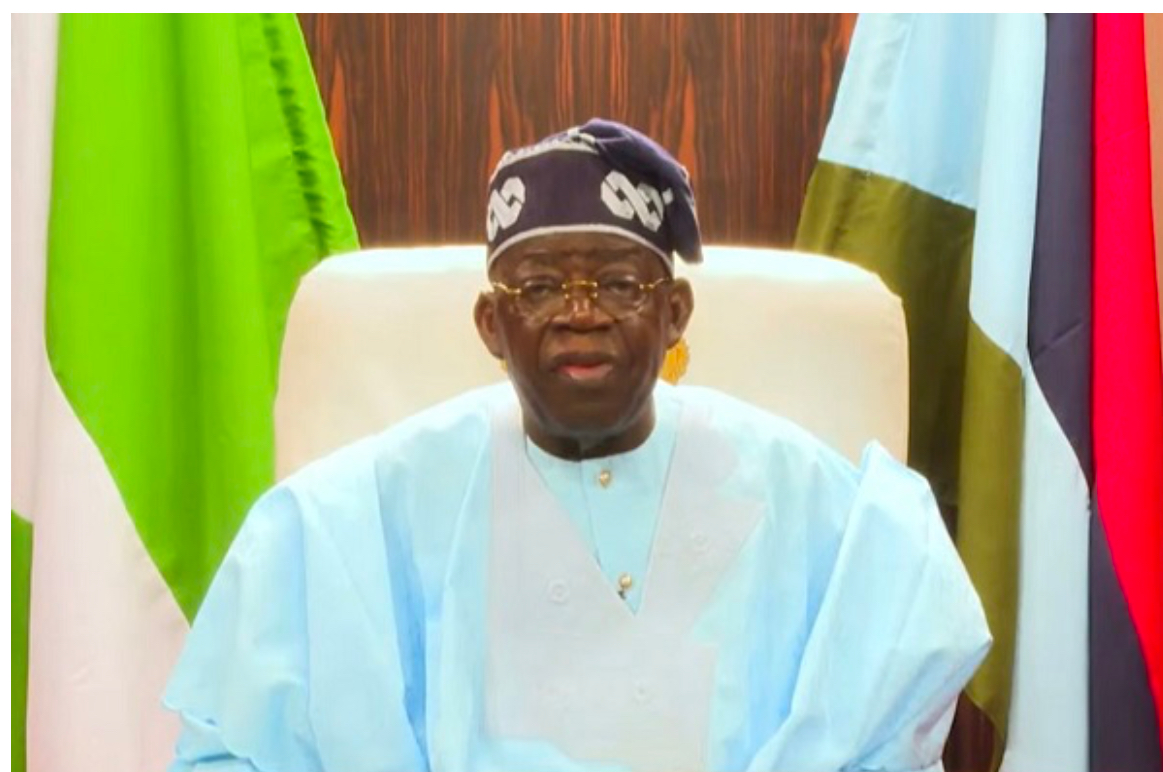
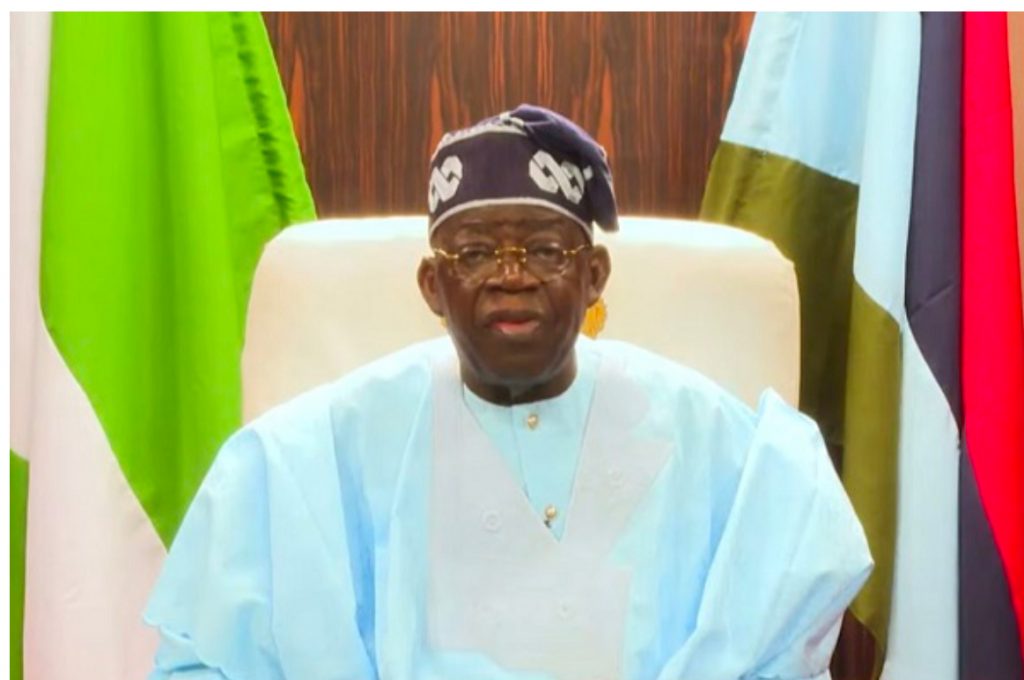
Nigeria has emerged as the biggest climber in Africa’s latest investment risk ranking, rising four places to eighth position as economic reforms implemented by President Bola Tinubu improved the country’s relative attractiveness to investors, a new report by Bloomberg has stated.
Nigeria overtook Rwanda, Tanzania, Kenya and Namibia in the 2026 Bloomberg Economics Investment Risk-O-Meter, which assesses the relative investability of 19 African economies.
Bloomberg, in the report released on Monday, said Nigeria’s improvement was driven by stronger performance in three of the five indicators used in the assessment: economic strength, fiscal strength and external vulnerability.
“Nigeria was the biggest climber in a ranking of Africa’s most investable markets, propelled by President Bola Tinubu’s economic reforms, according to the findings of the latest edition of An Investor’s Guide to Africa.
“The continent’s biggest oil producer and refiner rose four places to eighth in the 2026 Bloomberg Economics Investment Risk-O-Meter, overtaking Rwanda, Tanzania, Kenya and Namibia as it improved in three of the five metrics assessed by the gauge: economic strength, fiscal strength and external vulnerability,” Bloomberg reported.
The development puts Nigeria among the biggest gainers on the continent, despite ongoing concerns about the country’s high public debt, cost of living, inflation, infrastructure deficit and foreign exchange pressures.
Mauritius emerged as the most investable African market in the latest ranking, while Botswana fell two places. South Africa, which topped the ranking in the previous edition, also dropped one place following a weaker economic growth outlook.
Nigeria’s improved position comes more than three years after Tinubu assumed office and embarked on a series of major economic reforms aimed at restructuring the country’s fiscal and monetary environment.
Add to Preferred Sources
Among the most significant measures were the removal of the petrol subsidy, reforms to the foreign exchange market and changes to electricity tariffs.
The Federal Government has repeatedly defended the reforms as necessary to address distortions that had weighed on public finances, discouraged investment and placed pressure on foreign exchange reserves.
However, the policies have also increased economic hardship for households and businesses, particularly through higher transport, food and energy costs. Despite the adjustment pains, Nigeria’s economy has continued to expand during the period under review.
Real Gross Domestic Product growth rose from 2.54 per cent in the third quarter of 2023 to 3.46 per cent in the fourth quarter of that year.
The economy subsequently grew by an average of 3.19 per cent in 2024 before accelerating to 3.85 per cent in 2025, its strongest annual performance within the period covered by the assessment.
Growth stood at 3.89 per cent in the first quarter of 2026, bringing the average quarterly growth between the third quarter of 2023 and the first quarter of 2026 to about 3.46 per cent.
The stronger growth performance has come alongside efforts by the government to increase revenue, reduce fiscal leakages and attract investment into critical sectors of the economy.
Nigeria’s improved position in the Bloomberg ranking, however, comes against the backdrop of a substantial increase in public debt.
Data from the Debt Management Office showed that Nigeria’s total public debt stood at N87.38tn as of June 30, 2023, shortly after Tinubu took office. By December 31, 2025, the figure had risen to N159.28tn. This represents an increase of N71.90tn, or about 82.3 per cent, in two and a half years.
The increase was driven by new borrowing, foreign exchange adjustments and the securitisation of certain legacy obligations, according to the DMO.
The development is significant for a country that has struggled for years to attract sufficient foreign capital because of concerns over exchange-rate instability, policy uncertainty, weak infrastructure, insecurity and limited fiscal space.
The reforms under the Tinubu administration have sought to address some of these constraints by allowing market forces a greater role in determining fuel prices, foreign exchange rates and electricity tariffs.
The foreign exchange reforms, in particular, were designed to reduce multiple exchange rates and improve transparency in the currency market, while the removal of the petrol subsidy was intended to reduce the government’s fiscal burden.
The electricity tariff reforms were also aimed at improving the financial viability of the power sector and encouraging investment by allowing electricity prices for some customer categories to better reflect supply costs.
Nigeria’s rise in the Bloomberg ranking therefore marks an improvement in its relative position among African investment destinations, even as investors continue to monitor the sustainability of its reforms, debt burden and economic growth.
President Bola Ahmed Tinubu is expected back in Abuja this evening after concluding a six-day stay in Lagos, the Presidency announced on Monday.
The President will depart Lagos for the Federal Capital Territory after a visit during which he participated in activities marking Nigeria’s 66th Independence Day anniversary and held other engagements. SahelSecurity Report
Tinubu arrived in Lagos on Tuesday, September 29, following his annual holiday in London and Paris.
While in Lagos, the President addressed Nigerians on October 1 to mark the country’s 66th Independence Day anniversary.
Later that day, he attended the national premiere of MKO, a documentary chronicling the life, political struggle, and legacy of the late Chief Moshood Kashimawo Olawale Abiola, as well as the historic June 12 pro-democracy struggle.
Powered by VidCrunch
The premiere was held at the Wole Soyinka Centre for Culture and Creative Arts in Lagos.
Special Adviser to the President on Information and Strategy, Bayo Onanuga, confirmed the President’s return to Abuja in a State House statement issued on Monday.
“President Bola Ahmed Tinubu will depart Lagos for Abuja this evening after his six-day visit to the former seat of government,” Onanuga said.
-
 news6 years ago
UPDATE: #ENDSARS: CCTV footage of Lekki shootings intact – Says Sanwo – Olu
-
 lifestyle6 years ago
Former Miss World: Mixed reactions trail Agbani Darego’s looks
-
 health6 years ago
Chairman Agege LG, Ganiyu Egunjobi Receives Covid-19 Vaccines
-
 lifestyle5 years ago
Obateru: Celebrating a Quintessential PR Man at 60
-
 news1 year ago
BREAKING: Tinubu swears in new NNPCL Board
-
 health6 years ago
UPDATE : Nigeria Records 790 new cases of COVID-19
-
 entertainment2 years ago
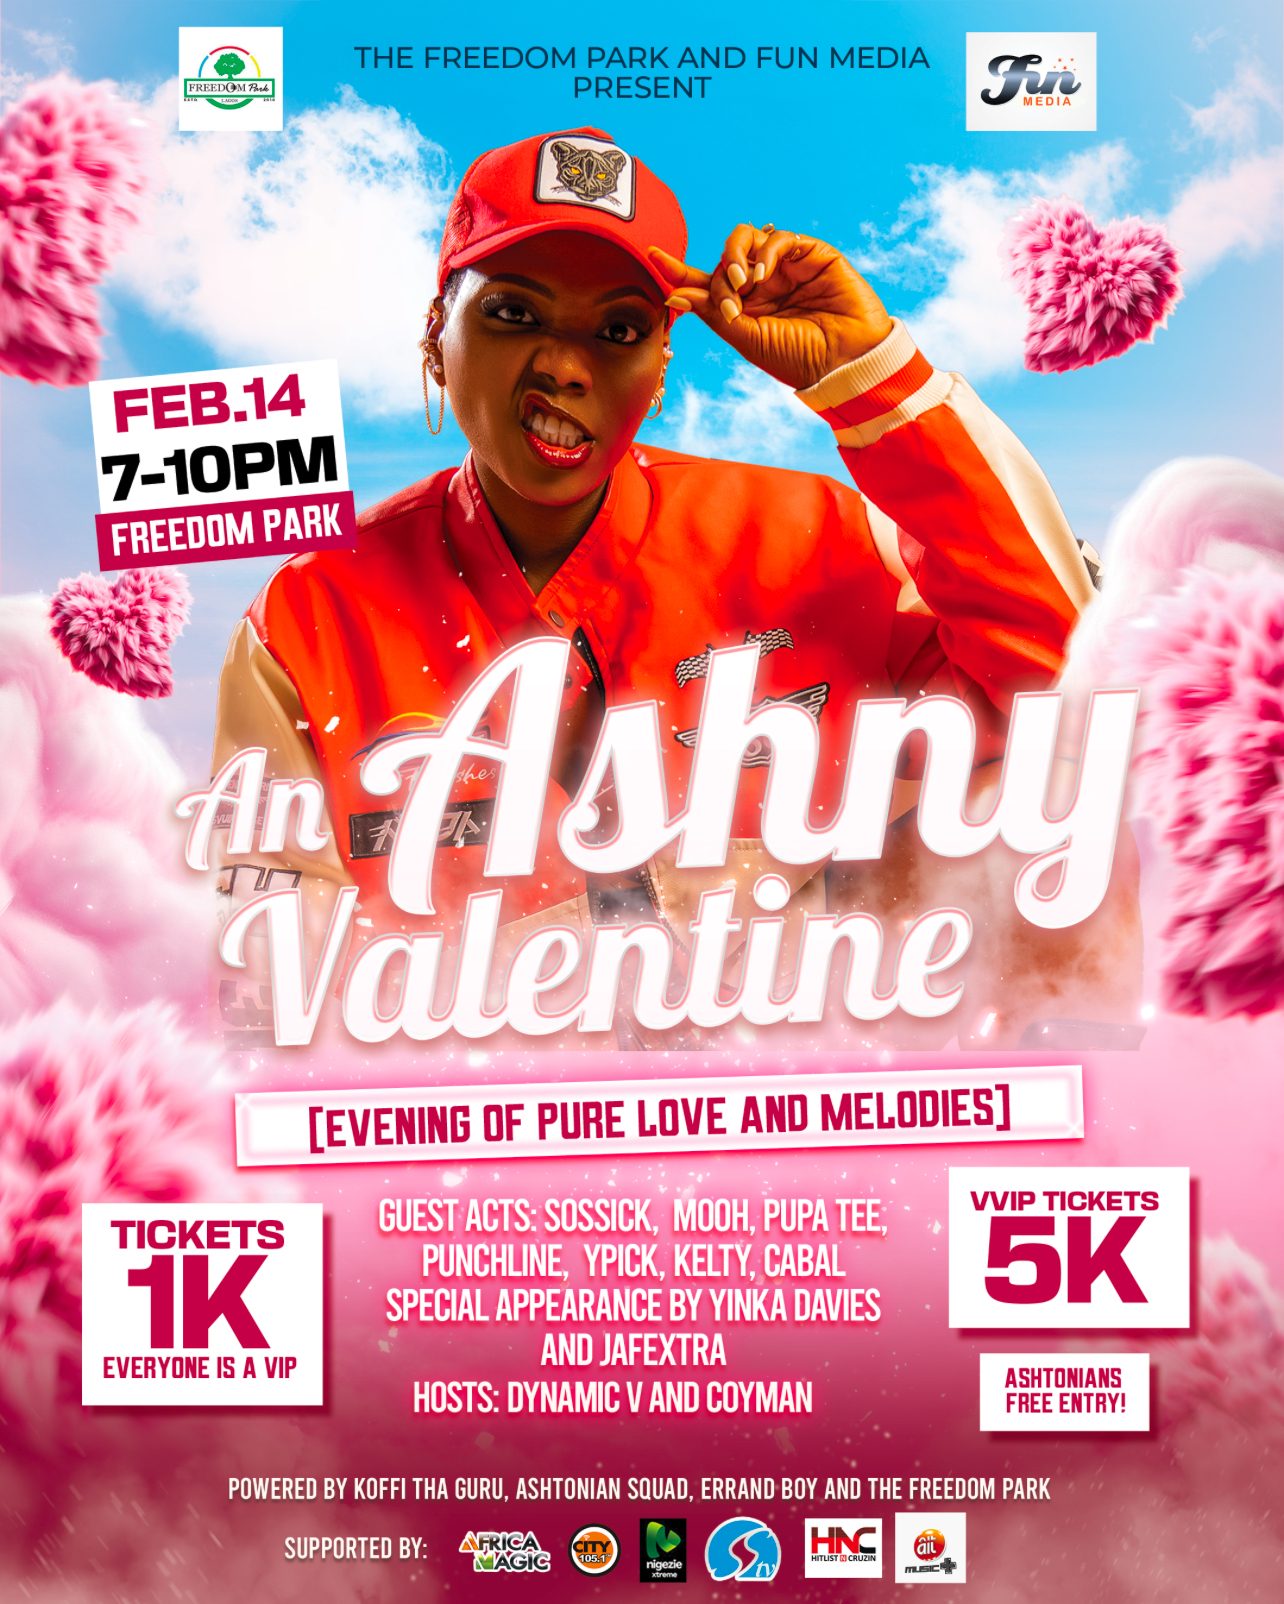
Ashny Set for Valentine Special and new Album ‘ Femme Fatale’
-
 society3 years ago
Bisbam CEO, Abisola Bamidele, Bags Owu Chieftaincy Title