Connect with us

news

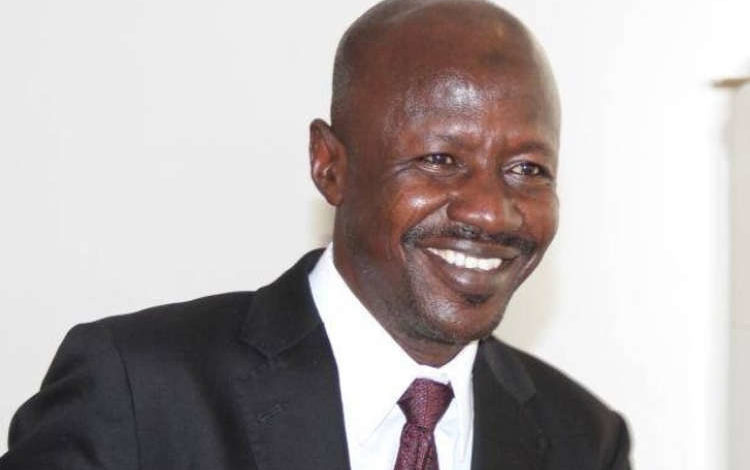
EFCC recovers N473b, $98.2m, £294,851 in 2017, says Magu

Published

on


EFCC recovers N473b, $98.2m, £294,851 in 2017, says Magu

The Economic and Financial Crimes Commission (EFCC) was able to recover crime – related funds amounting to N473b in addition to $98,258,124.97; £294,851.82; €7,247,363.75; 443,400 Dirham and 70,500 Rand, the Commission’s acting Chairman, Ibrahim Magu has said.

Magu also confirmed that identified whistle blowers, including the Osborne Towers, Ikoyi whistle blower were being paid timely to encourage other Nigerians buy into the policy.

During the course of 2017, the Commission also succeeded in securing final forfeiture of the Osborne Towers, Ikoyi cash of $43m as well as N32b; $5m recovered from a former Petroleum Resources Minister and N449m discovered at Legico Plaza in Victoria Island, Lagos, he said.

While defending the Commission’s 2017 budget before the Kayode Oladele-led House of Representatives Committee on Financial Crimes yesterday, Magu said the $43m Osborne Towers cash got forfeited to the Federal government because no one came forward to claim it.

The Committee had asked Magu whether the Osborne cash was ever traced to anyone.

In response, Magu explained that the document recovered from the property from where the money was recovered showed that it belonged to a company owned by the wife and son of a former Director General of the National Intelligence Agency (NIA).

However, after due diligence and no one coming forward to calm it, the court had to pronounce it’s final forfeiture, he said.

Among other recoveries and forfeitures from proceeds of crime, Magu said over N329b was recovered from petroleum marketers by the Kano office of the Commission; withholding tax recovery of over N27.7b from banks; €6.6m recovered from Nigerian Ports Authority (NPA); recoveries of about N1.1b on behalf of AMCON; and recovery of subsidy fraud funds of over N4b.

Magu however reiterated government commitment to the whistle blowing policy, saying, promised incentives are being paid timely.

Saying that the Ikoyigate whistle blower has also been paid, Magu noted the payment policy was meant to encouraged more Nigerians to join in the campaign against corruption.

On the 2017 budget implementation, the EFCC boss complained of delay in fund releases which he said affected operations of the Commission

“Delayed and irregular release of the overhead component of the recurrent vote affected the commission’s investigation and prosecution activities especially in the Zones.

“Out of the total sum of total sum of N17,202,253,360 appropriated in 2017, only N11,737,492,342.07 or 68 percent has so far been released out of which N9,759,277,008.53 has been utilized.

“From the sum of N7,127,316,354 appropriated for Personnel, N6,533,373,324 was released; from N3,000,713,298 appropriated for Overhead only N1,667,007,163.70 has been released while from N7,074,223,708 appropriated for Capital expenditure, only N3,537,111,853.87 was released to the commission so far,” he added.

He also complained that the Commission’s 2018 budget proposal of N45b was reduced to about N21b, which is capable of hampering the activities of the Commission for the year.

Magu also informed the Committee that Nigerian Financial Intelligence Unit (NFIU) has been granted autonomy.

“In the course of the outgoing financial year, the NFIU was granted self-accounting status by both the Office of the Accountant General of the Federation and the Budget Office. Effective date of implementation is 1st January, 2018 with a budget proposal of N2.903b,” he said.

Of the sum, N339.350m was proposed for Personnel cost; N22.500m for meals and refreshment to cater for numerous sub-regional, national and internal meetings while N26.500m was proposed for publicity and advertisement for stakeholders in the financial sector.
Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

news

Update :FG Unveils Additional 10 Steps to Reduce Impact of Rising Fuel Prices

Published

on

Ok

The Federal Government has announced ten new measures to reduce the pain Nigerians feel from high fuel prices. It insists, however, that none of them brings back the old fuel subsidy for everyone.

The measures were presented by the Federal Ministry of Finance at a press briefing on Thursday, 8 October 2026, titled “Fuel Prices and the Subsidy Question.” The government admitted its earlier steps fell short. According to the presentation, “These measures do not fully relieve the pressure households feel today, so the government is going further.”

The government described the new package as “Help that is targeted, temporary and affordable.” In plain terms, the help is meant for those who need it most, will not last forever, and is designed so that the country can pay for it.

Cheaper petrol and more cash support

The first measure is a discount on petrol sold at NNPC filling stations. The discount will last for the next 30 days, and public transporters, such as commercial bus and taxi operators, will get priority. The government hopes this will help keep transport fares from rising further.

The government also plans to increase cash transfers to vulnerable households. Small businesses will get cheaper loans, known as subsidised credit, to help them cope with higher running costs.

Steps to keep pump prices steady

To protect Nigerians from sudden jumps in world oil prices, the government will sell crude oil in advance to local refineries. This is expected as oil production rises and crude previously committed to other purposes becomes available. The presentation says this will shield “pump prices from global swings.” ShopAfrican Art

The government will also introduce what it calls price modulation. Under this plan, a negotiated limit of ₦1,350 per litre will apply to the ex-gantry price (the price at the depot) or the landing cost (the cost of bringing the fuel into the country). The limit will be reviewed every month, so it can change as conditions change.

A National Strategic Fuel Reserve will also be set up. Fuel from the reserve will be released “under published rules when disruption or hoarding threatens supply.” This means the government can step in when fuel becomes scarce or when marketers hold back products to push up prices.

Lowering the cost of transport and doing business

The government says part of what Nigerians pay for transport comes from illegal charges on the roads. It will work with state governments under the 2025 tax laws to rein in road taxes that push up fares.

It will also speed up the rollout of compressed natural gas (CNG) as a cheaper alternative to petrol, again working with the states. Transporters who benefit from cheaper fuel are expected to “pass savings on in lower fares” to passengers.

Other steps target the cost of goods and services more broadly. The government will cut regulatory costs, described as red tape, that “feed into the price of goods and services.” It will also ease traffic in cities to save fuel, and it will use NIPOST address codes to reduce the cost of moving goods from one place to another.

One measure has not yet been decided. The government is considering an excess profit tax on operators it says exploit consumers. If it goes ahead, the money raised will fund transport support and vouchers for low-income earners.

No return to blanket subsidy

The ministry ended the presentation with a clear message, “None of these measures restores a blanket subsidy.” The government is therefore not returning to the old system, where fuel was sold cheaply to everyone. It says its new approach will reach “the people who need help without putting the wider economy at risk.”

The announcement comes as many households as possible, and businesses struggle with the high cost of transport, food, and other goods linked to fuel prices. How much relief Nigerians feel will depend on how quickly and effectively these measures are carried out, and whether transporters and marketers pass the benefits on to consumers.

Continue Reading

news

Nigeria Emerges as Africa’s Biggest Climber in Investment Risk Ranking on Back of Tinubu’s Economic Reforms

Published

on

Nigeria has emerged as the biggest climber in Africa’s latest investment risk ranking, rising four places to eighth position as economic reforms implemented by President Bola Tinubu improved the country’s relative attractiveness to investors, a new report by Bloomberg has stated.

Nigeria overtook Rwanda, Tanzania, Kenya and Namibia in the 2026 Bloomberg Economics Investment Risk-O-Meter, which assesses the relative investability of 19 African economies.

Bloomberg, in the report released on Monday, said Nigeria’s improvement was driven by stronger performance in three of the five indicators used in the assessment: economic strength, fiscal strength and external vulnerability.

“Nigeria was the biggest climber in a ranking of Africa’s most investable markets, propelled by President Bola Tinubu’s economic reforms, according to the findings of the latest edition of An Investor’s Guide to Africa.

“The continent’s biggest oil producer and refiner rose four places to eighth in the 2026 Bloomberg Economics Investment Risk-O-Meter, overtaking Rwanda, Tanzania, Kenya and Namibia as it improved in three of the five metrics assessed by the gauge: economic strength, fiscal strength and external vulnerability,” Bloomberg reported.

The development puts Nigeria among the biggest gainers on the continent, despite ongoing concerns about the country’s high public debt, cost of living, inflation, infrastructure deficit and foreign exchange pressures.

Mauritius emerged as the most investable African market in the latest ranking, while Botswana fell two places. South Africa, which topped the ranking in the previous edition, also dropped one place following a weaker economic growth outlook.

Nigeria’s improved position comes more than three years after Tinubu assumed office and embarked on a series of major economic reforms aimed at restructuring the country’s fiscal and monetary environment.

Add to Preferred Sources
Among the most significant measures were the removal of the petrol subsidy, reforms to the foreign exchange market and changes to electricity tariffs.

The Federal Government has repeatedly defended the reforms as necessary to address distortions that had weighed on public finances, discouraged investment and placed pressure on foreign exchange reserves.

However, the policies have also increased economic hardship for households and businesses, particularly through higher transport, food and energy costs. Despite the adjustment pains, Nigeria’s economy has continued to expand during the period under review.

Real Gross Domestic Product growth rose from 2.54 per cent in the third quarter of 2023 to 3.46 per cent in the fourth quarter of that year.

The economy subsequently grew by an average of 3.19 per cent in 2024 before accelerating to 3.85 per cent in 2025, its strongest annual performance within the period covered by the assessment.

Growth stood at 3.89 per cent in the first quarter of 2026, bringing the average quarterly growth between the third quarter of 2023 and the first quarter of 2026 to about 3.46 per cent.

The stronger growth performance has come alongside efforts by the government to increase revenue, reduce fiscal leakages and attract investment into critical sectors of the economy.

Nigeria’s improved position in the Bloomberg ranking, however, comes against the backdrop of a substantial increase in public debt.

Data from the Debt Management Office showed that Nigeria’s total public debt stood at N87.38tn as of June 30, 2023, shortly after Tinubu took office. By December 31, 2025, the figure had risen to N159.28tn. This represents an increase of N71.90tn, or about 82.3 per cent, in two and a half years.

The increase was driven by new borrowing, foreign exchange adjustments and the securitisation of certain legacy obligations, according to the DMO.

The development is significant for a country that has struggled for years to attract sufficient foreign capital because of concerns over exchange-rate instability, policy uncertainty, weak infrastructure, insecurity and limited fiscal space.

The reforms under the Tinubu administration have sought to address some of these constraints by allowing market forces a greater role in determining fuel prices, foreign exchange rates and electricity tariffs.

The foreign exchange reforms, in particular, were designed to reduce multiple exchange rates and improve transparency in the currency market, while the removal of the petrol subsidy was intended to reduce the government’s fiscal burden.

The electricity tariff reforms were also aimed at improving the financial viability of the power sector and encouraging investment by allowing electricity prices for some customer categories to better reflect supply costs.

Nigeria’s rise in the Bloomberg ranking therefore marks an improvement in its relative position among African investment destinations, even as investors continue to monitor the sustainability of its reforms, debt burden and economic growth.

Continue Reading

news

Update : Tinubu Expected Back in Abuja Today After Six-Day Stay in Lagos

Published

on


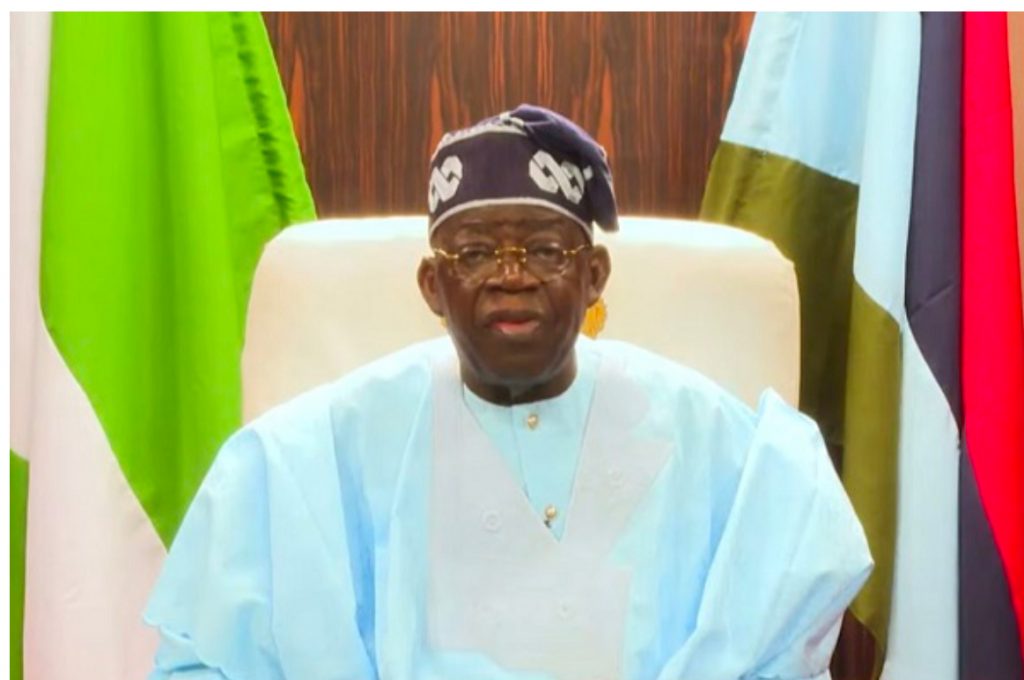
President Bola Ahmed Tinubu is expected back in Abuja this evening after concluding a six-day stay in Lagos, the Presidency announced on Monday.

The President will depart Lagos for the Federal Capital Territory after a visit during which he participated in activities marking Nigeria’s 66th Independence Day anniversary and held other engagements. SahelSecurity Report

Tinubu arrived in Lagos on Tuesday, September 29, following his annual holiday in London and Paris.

While in Lagos, the President addressed Nigerians on October 1 to mark the country’s 66th Independence Day anniversary.

Later that day, he attended the national premiere of MKO, a documentary chronicling the life, political struggle, and legacy of the late Chief Moshood Kashimawo Olawale Abiola, as well as the historic June 12 pro-democracy struggle.

Powered by VidCrunch
The premiere was held at the Wole Soyinka Centre for Culture and Creative Arts in Lagos.

Special Adviser to the President on Information and Strategy, Bayo Onanuga, confirmed the President’s return to Abuja in a State House statement issued on Monday.

“President Bola Ahmed Tinubu will depart Lagos for Abuja this evening after his six-day visit to the former seat of government,” Onanuga said.


Continue Reading

Trending

Copyright © 2025 Newsthumb Magazine | All rights reserved